The same AI boom is making Taiwan richer and South Korea's households pay more to borrow
Both economies ride the memory-chip windfall. In Taiwan it bids up wages across the whole workforce; in Korea it lands on two chaebols, then spills into inflation the central bank is cooling by raising rates on everyone.
 Richard Tangfive-minute read
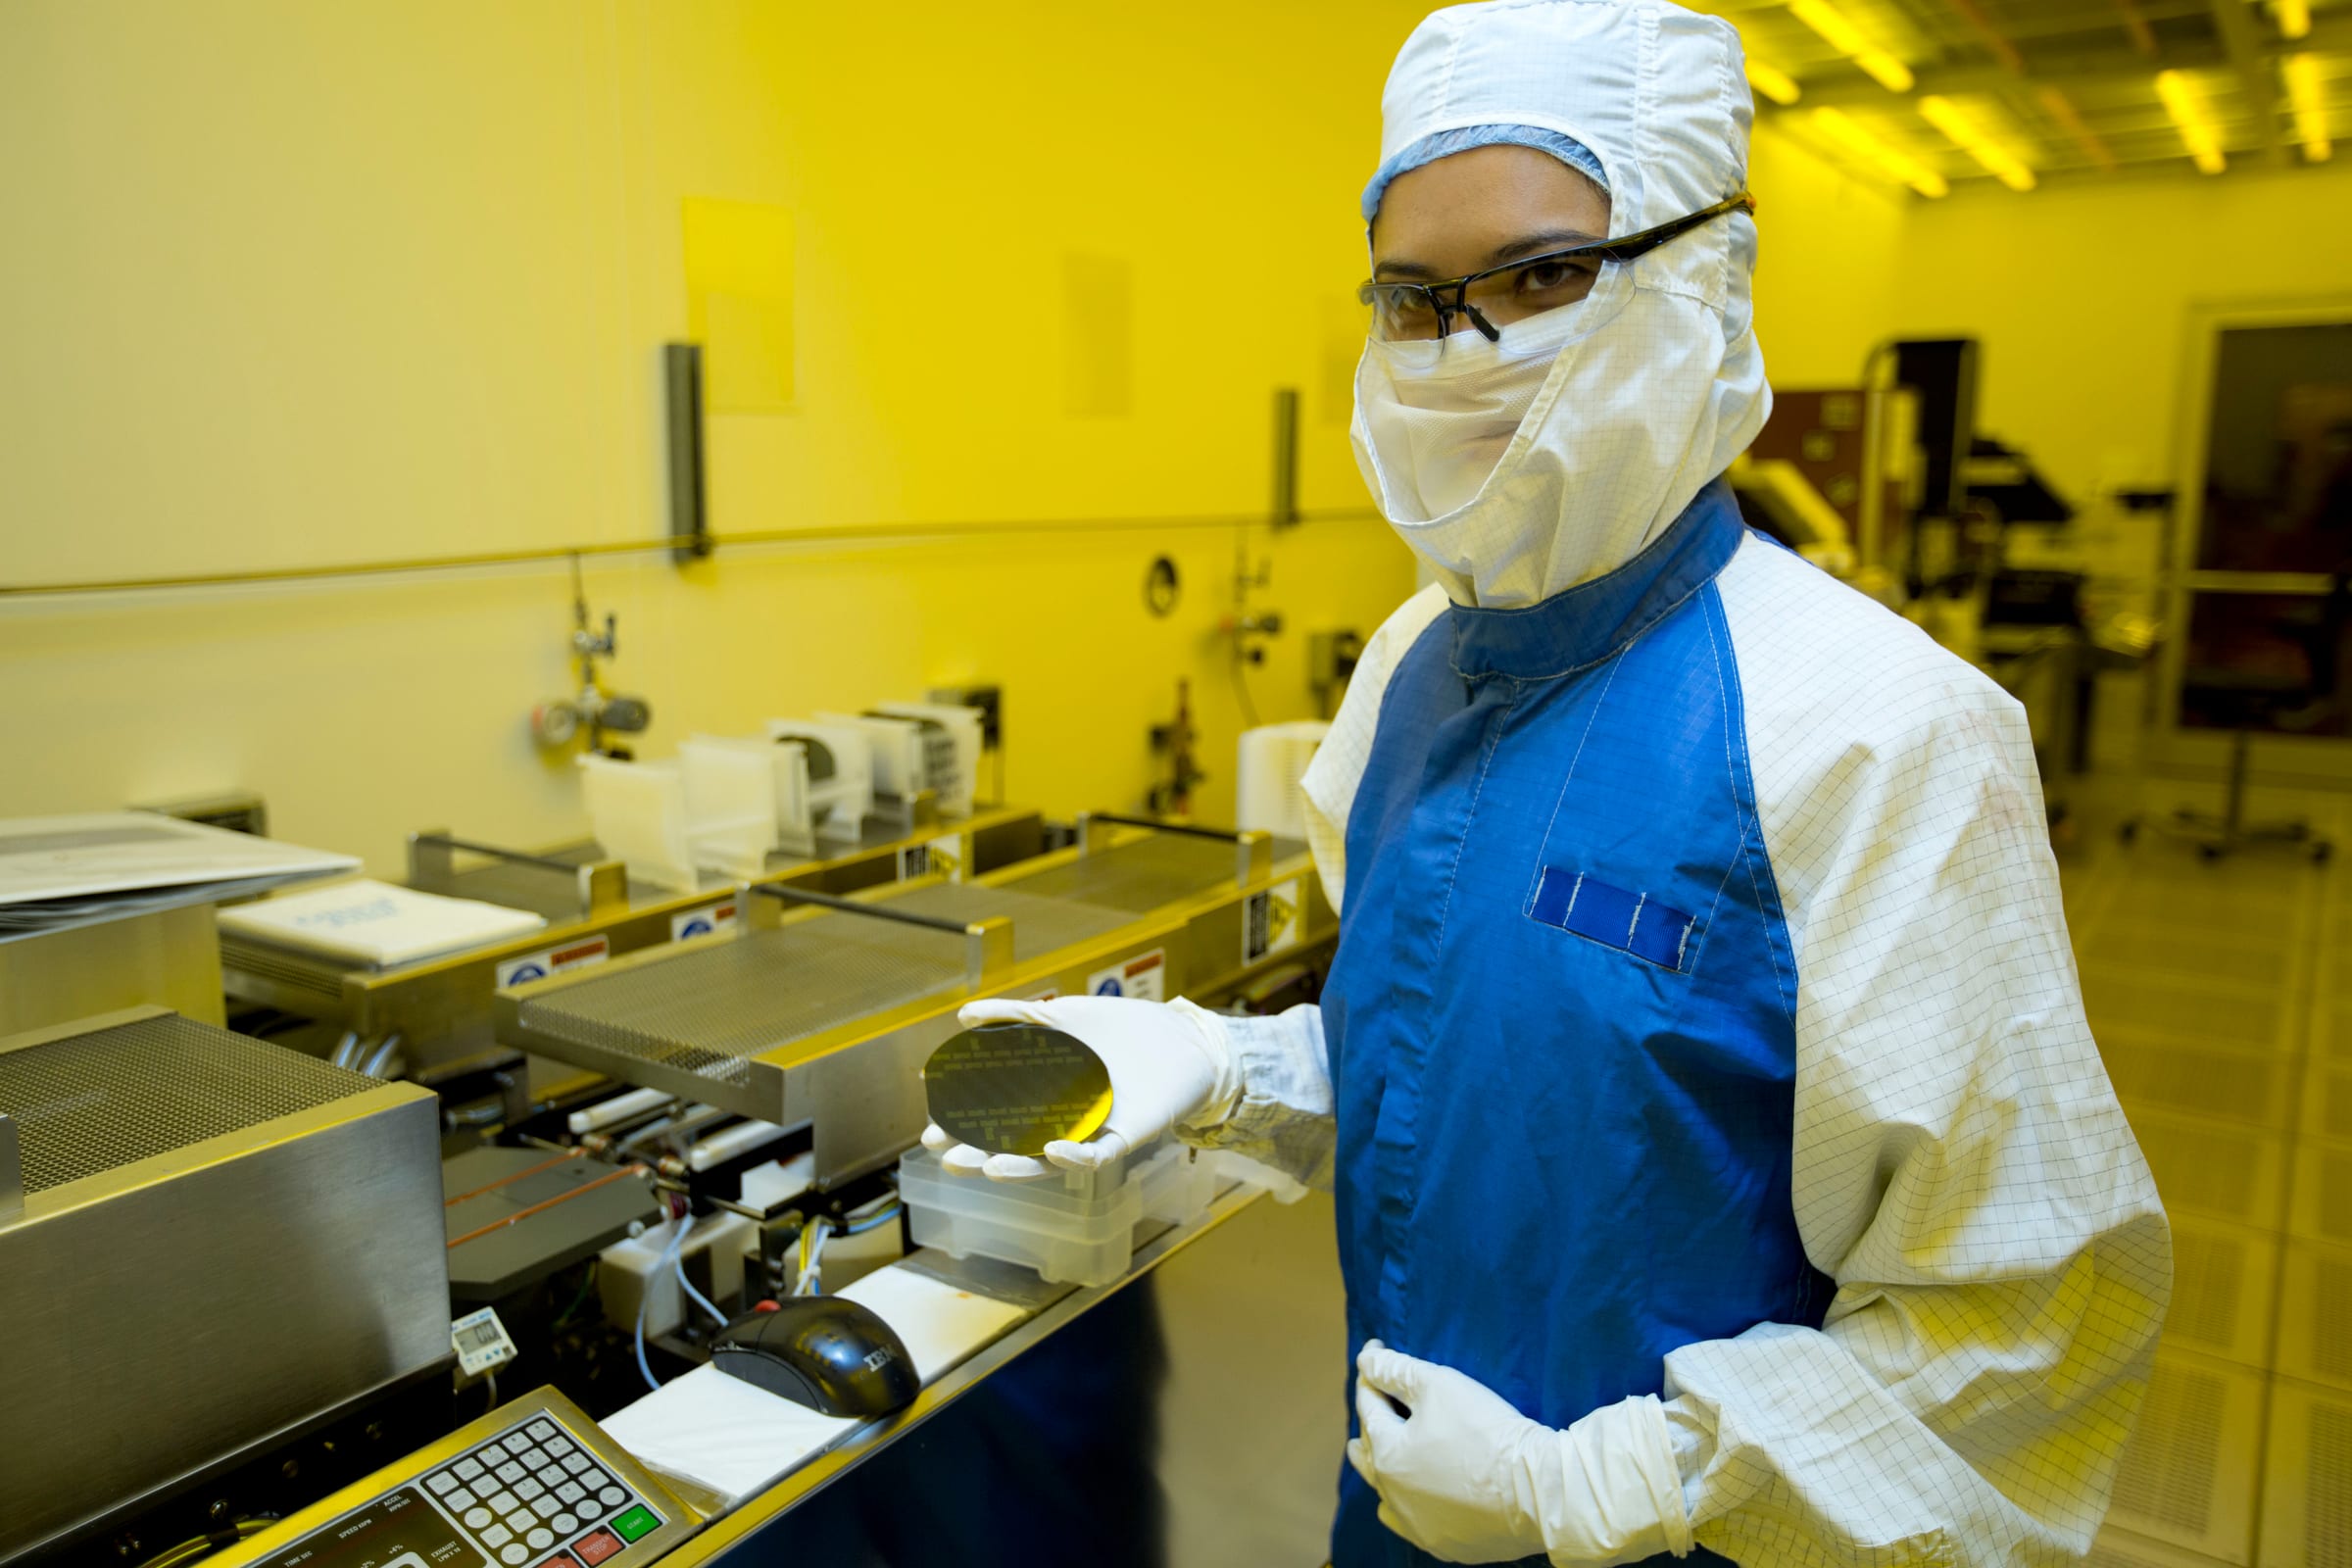
The booster's case has always been that data-centre spending finds its way to everybody. Build the fabs, buy the chips, and eventually the money becomes somebody's paycheck, somebody's pension, somebody's tax-funded handout. To see whether that actually works, forget America and Europe: too big, too diluted. Look at the two economies most exposed to AI silicon: Taiwan and South Korea. They are running what amounts to a controlled experiment in how the same boom distributes itself, and the results are already in.
The headline numbers look like the experiment succeeded twice. Taiwan grew around 12% last year, South Korea around 4%, and in both places private consumption is finally accelerating after a stagnant stretch 1. But the mechanism underneath is different in each country, and the difference is the whole story.
- Taiwan
- South Korea
Data
| Taiwan | South Korea | |
|---|---|---|
| GDP growth last year | 12% | 4% |
| Nominal wage growth now | 3% | — |
| Pre-pandemic wage trend | 1.9% | 3.5% |
Taiwan: the boom arrives as wages
Taiwan's gains come from volume. TSMC−2.68% — TSMC, down 2.68 percent today, which fabricates nearly all the world's AI chips, lifted wafer production from 10m in 2019 to 15m last year and pushed capex from $15bn to $41bn 1. Real fixed capital formation is up nearly 40% since late 2023, and nearly 11% of Taiwanese employees now make electronics or computers, the highest share since 2016 1. The money is being spent on building things, which means hiring people.
That is where the trickle-down actually shows up, and it is not magic. Pay rose first in electronics, then spread: average nominal wages now grow 3% a year, against a pre-pandemic trend of 1.9%, across the entire workforce, not just the foundry floor 1. The economist Paul Cavey names the mechanism (the Balassa-Samuelson effect) by which productivity in a tradable sector bids up the price of labour everywhere else, because a barista competes with TSMC for the same rent and the same workers 1. Volume produces competition for labour, and competition for labour raises wages even for people who never touch a wafer.
The government adds a second channel. The tax take from the silicon goose is so large that Taiwan proposed paying every citizen a roughly $300 "AI dividend" ($7bn total) on top of social-welfare spending set to rise 40% in 2027 1. Crucially, this is not a one-off: Taiwan paid the same 10,000 TWD per citizen in 2025 too, and the 2027 version drew predictable opposition complaints that it is election-year populism 2. Populism or not, the money goes to everyone rather than to whoever holds the stock.
South Korea: the boom arrives as a price, then as a rate hike
Korea's version is the mirror image. Instead of a gradual build of volume, demand arrived all at once, and the windfall showed up as price, not quantity: economy-wide export prices rose 57% over the past year 1. Because investment lagged (Samsung actually trimmed capex between 2023 and 2025 while SK Hynix tripled from a small base), the immediate benefit is confined to the under-1% of workers in the chip industry and to shareholders of the two memory makers 1. Economy-wide wage growth has fallen below its pre-pandemic 3.5% pace 1.
The customs data makes the concentration stark. In July, large enterprises (the chaebols) took 75.2% of Korea's exports, up 10.9 percentage points in a year, while mid-sized firms' chip exports actually fell 13.4% 3. High-bandwidth memory needs capex at a scale only Samsung and SK Hynix can deploy; the tier below them cannot chase the boom 3. The trickle stops two companies short of the workforce.
And here is the part that turns a lopsided distribution into an active cost imposed on ordinary Koreans. The boom is now inflationary. Consumer prices ran above 3% for two straight months, on top of strong growth, and the Bank of Korea responded by *tightening*: hiking its base rate to 2.75% in July and 3% in August, with the governor explicitly saying the cycle could last longer if chip prices stay high 4. The wealth effect is muted, because a KOSPI dollar of gains translates to only about one cent of Korean consumer spending 1. So the memory windfall inflates rents and services in Seoul, the central bank raises borrowing costs for everyone to cool it, and the two companies whose chips caused the heat pay the higher financing costs on their next fabs 4. The people who benefit least carry the rate.
The government knows the distribution is broken (it launched a ₩5 trillion fund in August aimed explicitly at chip *suppliers*, not the two champions 3), but its windfall policy is to save about 70% of the projected 50% revenue jump rather than hand it out 1. That may be the wiser choice. Booms built on price are reversible, and Korea is saving for the turn.
What to take from the experiment
Trickle-down is not a law of nature; it is a mechanism with preconditions. The boom redistributes broadly when it runs through *volume* (hiring, investment, competition for labour) and it stays bottled up when it runs through *price*, which rewards whoever already owns the scarce asset. Taiwan built the volume; Korea's companies repriced the scarcity.
The actionable difference is this: if you want to know whether an AI-windfall economy will spread its gains, don't look at GDP growth or the headline export number. Ask two questions. Is capex translating into fixed investment that hires people, or into margin that lands on shareholders? And is the government cycling the tax take back toward citizens, or holding it against the cycle? Taiwan answered both one way, Korea the other. The growth rates differ by a factor of three, but the lived difference is bigger than that. Borrowers in Seoul are now paying to cool a boom they were never really inside.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.
Reader comments
0 comments