Tower Semiconductor is up 99.97% this year on an AI photonics shipment with no disclosed volume
Tower slid from about $248 to $228.71 this week, the first wobble in a stock up 99.97% this year on an AI photonics shipment whose volume neither company discloses. The 6.4T chipset behind the multiple begins volume shipment no earlier than the first half of 2027.
 Vincent Jiang · 3 min read
The first wobble in a one-way trade
Tower Semiconductor−0.33% — Tower Semiconductor, down 0.33 percent today closed at $228.71 on Friday, October 9, down nearly 8% in two sessions from about $248 on October 7 81, in a week when the optical names moved on Marvell's+0.02% — Marvell, up 0.02 percent today guidance rather than their own news 8. It is the first wobble in a one-way year. Tower is up 99.97% in 2026 to a $25.85 billion market cap 2, and the run was bought on a shipment announcement that still carries no number.
One startup is the whole proof point
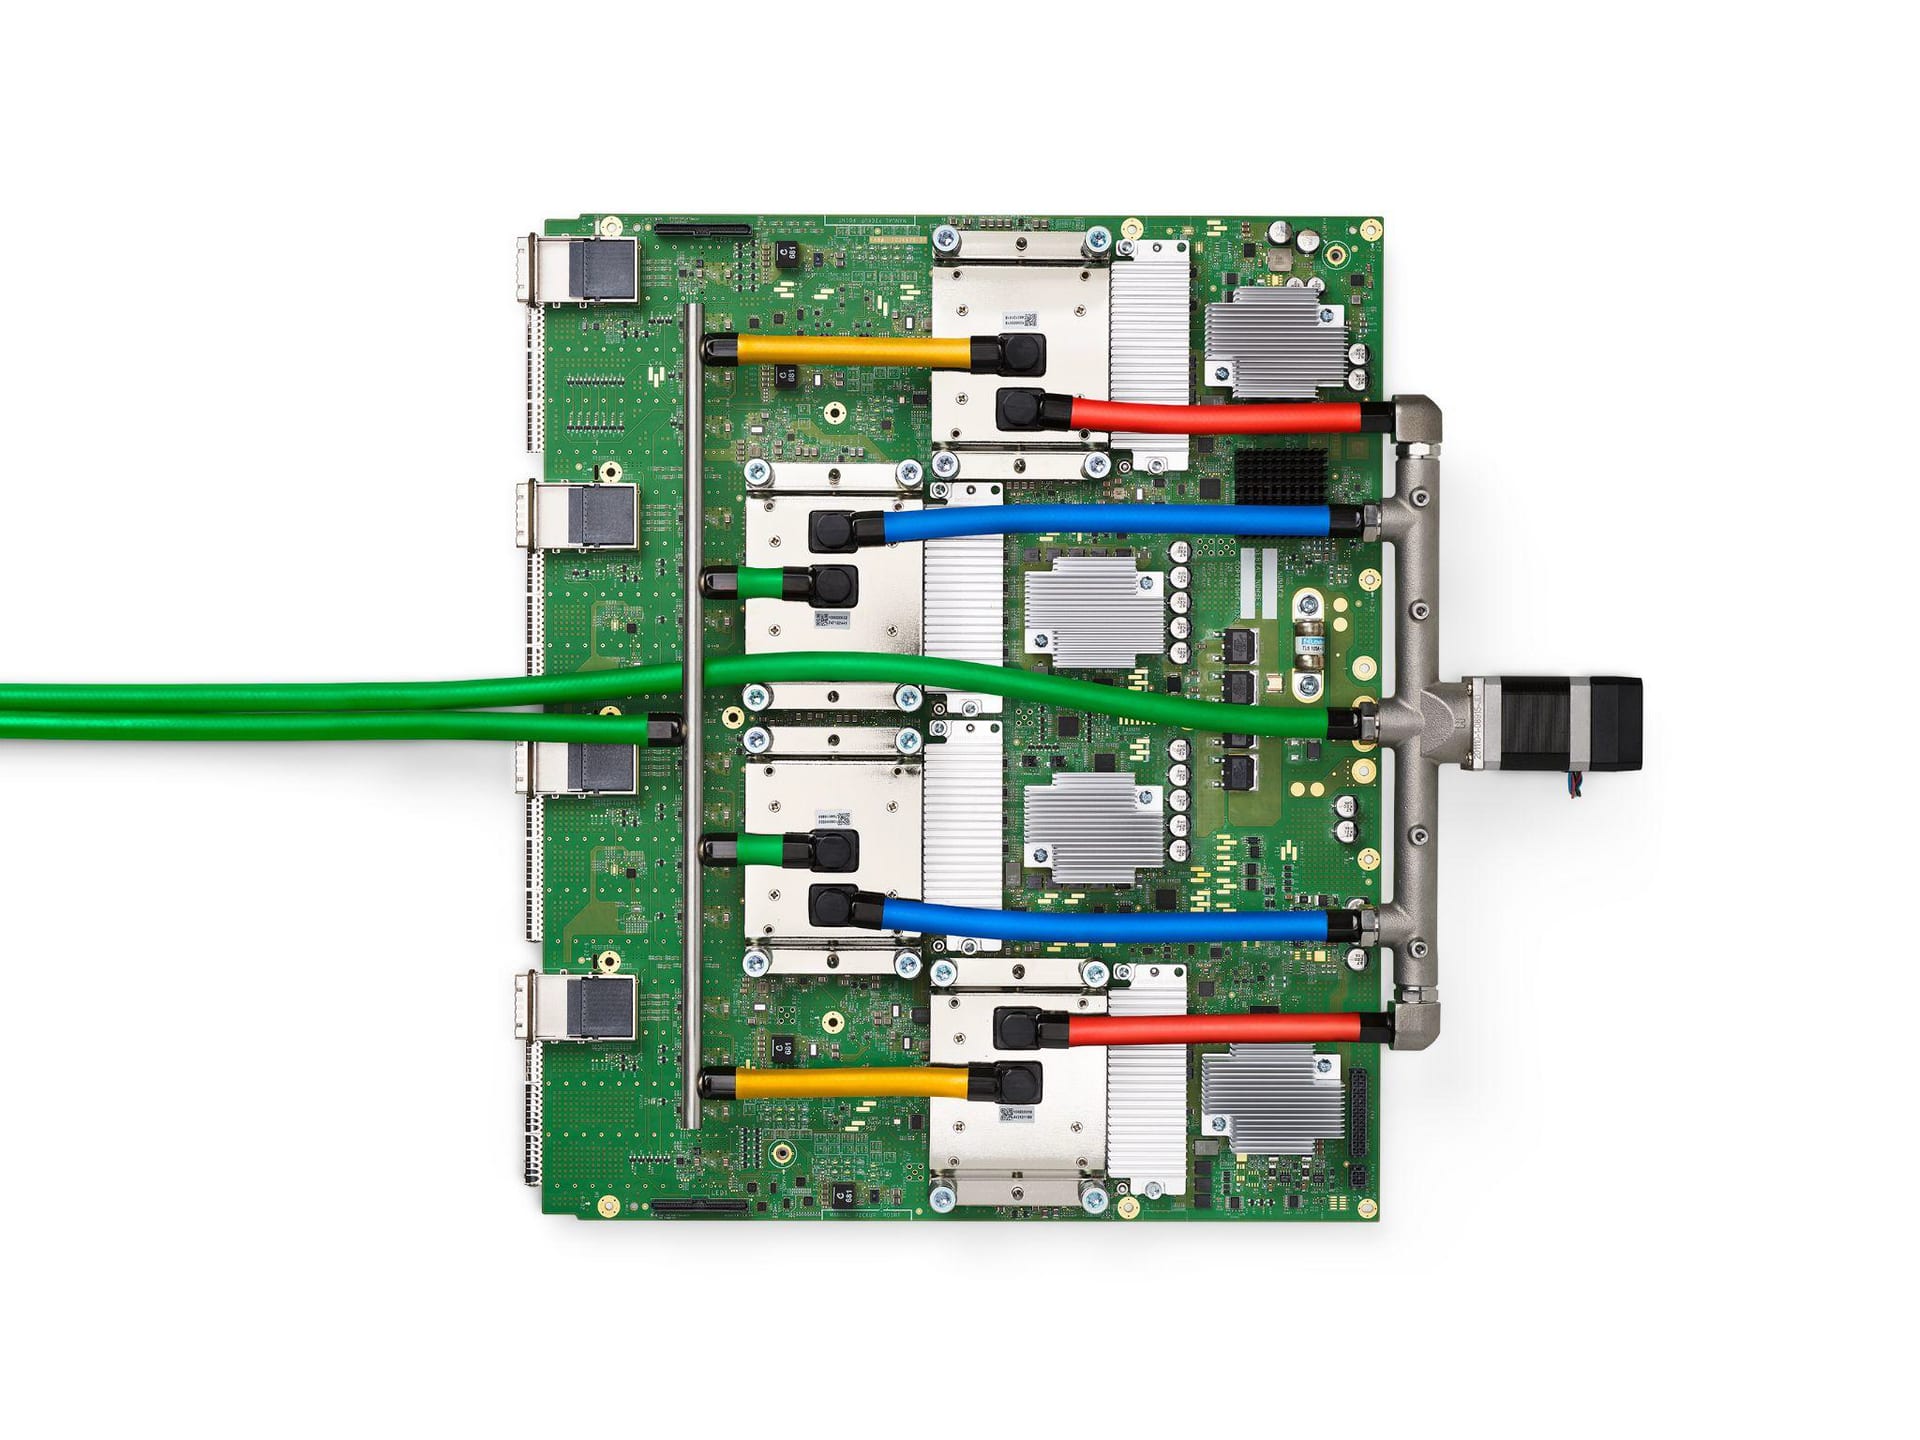
On September 17, 2026, Tower and the Israeli fabless chipmaker NewPhotonics said laser-integrated optical engines are shipping in high volume off Tower's PH18DA photonics platform: single chips carrying the laser, amplifiers, modulators and detectors that move AI cluster data as light 1. NewPhotonics is, by Tower's own account, the first customer to bring heterogeneously laser-integrated engines on PH18DA into volume production 1. The release names no unit count and no dollar figure. The only dedicated write-up since, an Insider Monkey promotional post that closes by pitching a different stock 2, adds none.
The product behind the multiple ships in 2027
What ships today covers data rates from 800G to 1.6T 1. The 6.4T NPC505 chipset, the piece that matches the interconnect future investors are paying for, begins volume shipment no earlier than the first half of 2027 1. The premium is a 2027 promise wearing 2026 prices.
Ninety-one times earnings for an unpriced ramp
The market cap carries a 91.11x trailing price-to-earnings ratio and a 38.46x forward multiple, on 9.98% trailing return on equity 2. Trailing revenue is $1.71 billion 8, which puts the stock near 15 times sales 2. The market has paid 91 times trailing earnings for a shipment neither company will put a number on. The contracted money sits elsewhere: about $1.3 billion of silicon photonics contracts for 2027, with $290 million already collected in prepayments 34.
Revenue set a record last quarter, and the market cap pays 15 times sales for it
- Revenue
- Operating income
Data
| Revenue | Operating income | |
|---|---|---|
| Q3 '24 | $370.51M | $55.76M |
| Q4 '24 | $387.19M | $46.42M |
| Q1 '25 | $358.17M | $32.9M |
| Q2 '25 | $372.06M | $39.87M |
| Q3 '25 | $395.67M | $50.58M |
| Q4 '25 | $440.21M | $70.83M |
| Q1 '26 | $413.63M | $64.57M |
| Q2 '26 | $460.08M | $90.29M |
The ramp underneath is real
Second-quarter revenue hit a record $460.08 million, up 23.7% year over year, on a 19.6% operating margin 9. A $3 billion capacity expansion in Japan, backed by roughly $1 billion in METI grants, underpins a company model of $3.6 billion revenue and $1.2 billion net profit in 2028 4. Hedge fund holders rose from 54 to 64 in the second quarter, a cohort worth about $2.57 billion 28, even as Senvest cut its stake 20% while Polar Capital raised its own 598% 3.
The street is long; one model is not
Stifel holds Buy with a $270 target 5. Mizuho initiated Outperform at $300, sizing the photonics transceiver market at $8.5 billion by fiscal 2029, and seven of eight analysts rate the stock Buy or better 6. Simply Wall St's fair-value model puts the right multiple at 53.3x against the stock's 90x, with the US semiconductor industry average at 47.7x 7. Short interest is about 2.2% of shares 3: almost nobody is positioned for the multiple to be wrong.
Tower trades at 91 times trailing earnings, near twice the industry average
Data
| Value | |
|---|---|
| Tower trailing P/E | 91.11x |
| Simply Wall St fair value | 53.3x |
| US industry average | 47.7x |
What would settle it
Three dates matter more than any rating. Prepayments on 2028 capacity fall due in January 2027 4, the NPC505 is promised for the first half of 2027 1, and the Arai fab in Japan is due production-ready in the fourth quarter of that year 4. Longs need a disclosed number and an on-time chipset; the 64-fund cohort 2 is the crowded exit if it slips. If the shipment still carries no figure by then, the multiple is running on faith.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.