Western Digital's $1.5 billion revolver allows 3.75 times leverage after a deal it has not named
The 8-K's covenant lets leverage rise to 3.75 times after an acquisition, the board's only public hint it is preparing to buy something, while the CEO's $6.2 million sale ran on a schedule adopted in February. The market is pricing a peak; the paperwork is pricing a plan.
 Vincent Jiangthree-minute read
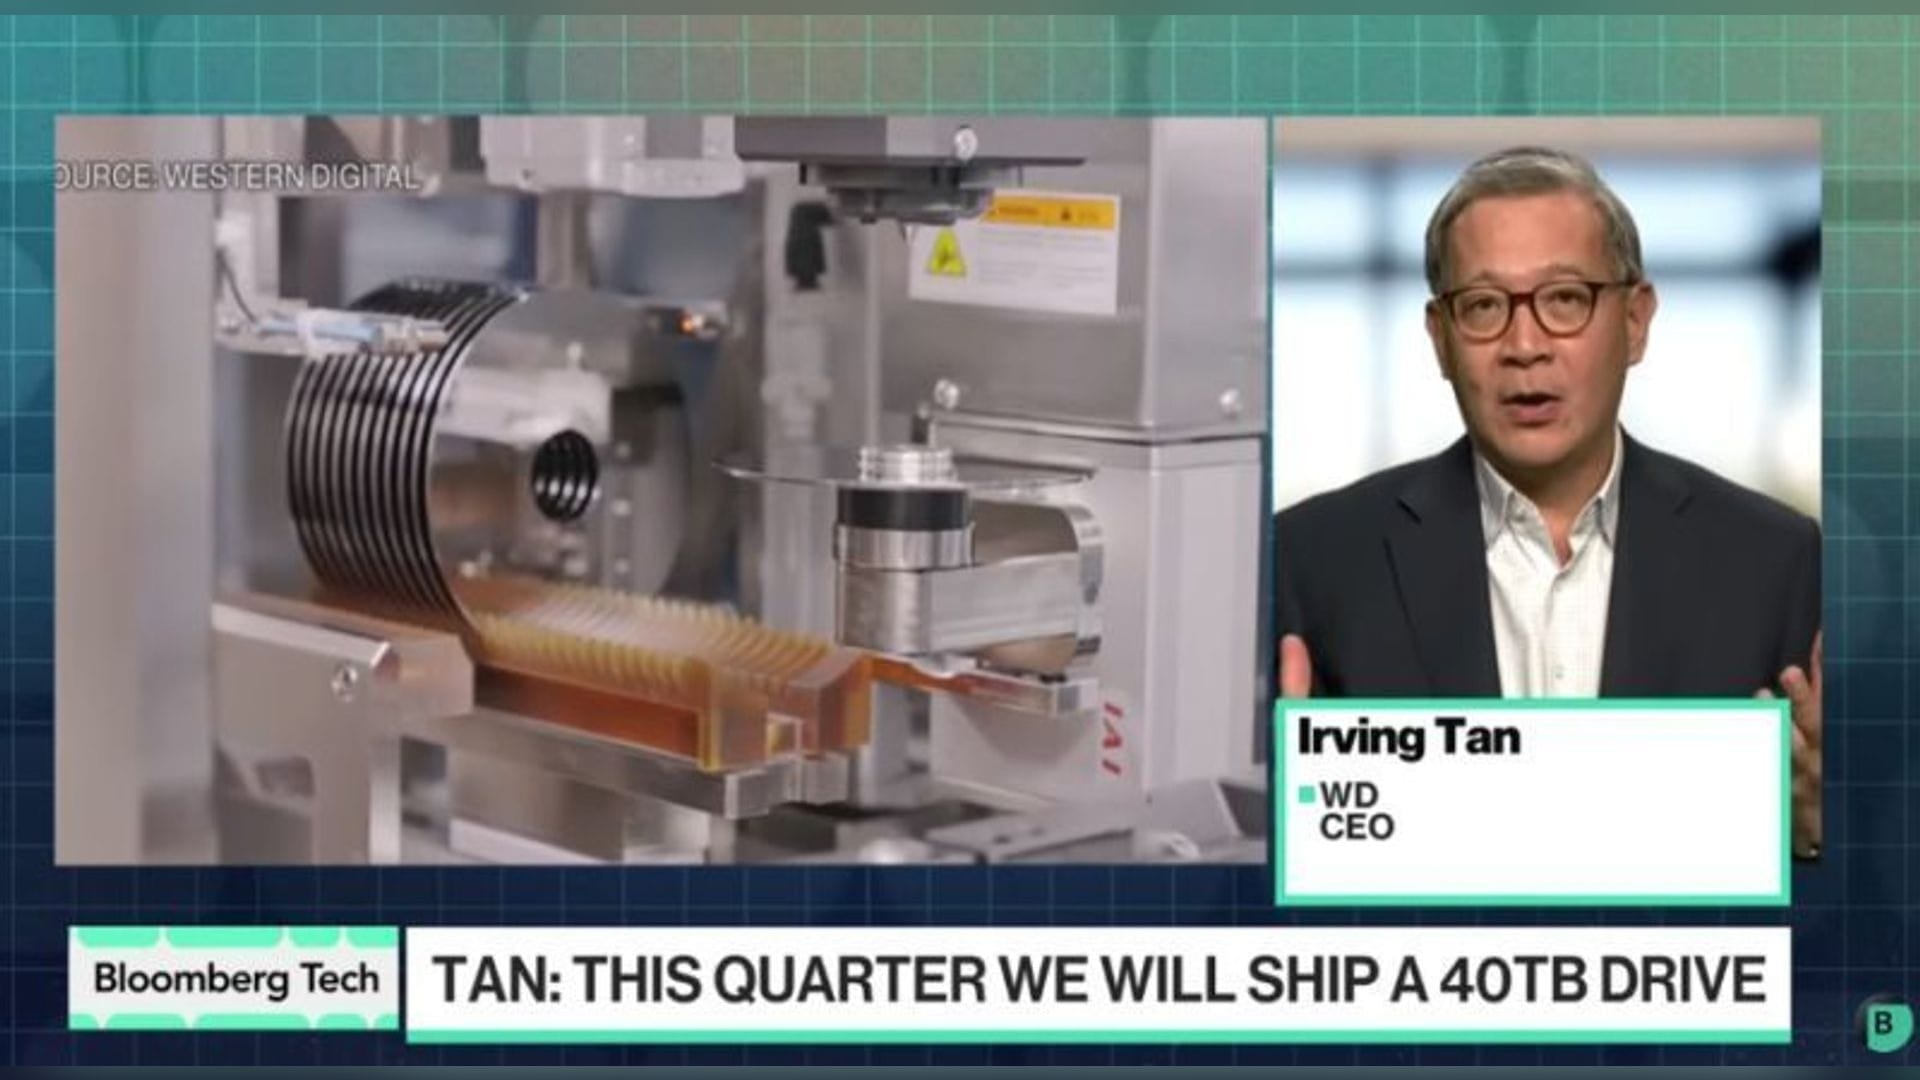
On November 13, 2026, Western Digital's−1.46% — Western Digital, down 1.46 percent today board signed a $1.5 billion, five-year senior unsecured revolving credit line maturing in 2031 and terminated the January 2022 loan agreement, paying off everything outstanding under it 1. The same day, chief executive Irving Tan sold 20,000 shares at a weighted average $308.51, collecting $6.2 million and keeping 245,613 2. Both filings landed on November 16; three days earlier, Yahoo Finance reported the stock had dropped nearly 8% in early November on a flash maker's cautious outlook, even though Western Digital sells hard drives 3.
The clause nobody has read
The new facility caps net leverage at 3.25 times, but the agreement lets that ceiling rise to 3.75 times for four consecutive quarters after a material acquisition, and lets subsidiaries join as borrowers 1. That is the only public signal the board has sent about buying something. Priced at Term SOFR plus 1.25% initially, fully unsecured with no collateral or subsidiary guarantees, the facility reads like a company expecting to use debt capacity, not defend it 1.
Debt has fallen from $8.4 billion to $789 million, less than Western Digital's cash
- Total debt
- Cash
Data
| Total debt | Cash | |
|---|---|---|
| Q4 '23 | $8.39B | $2.48B |
| Q1 '24 | $7.77B | $1.89B |
| Q2 '24 | $7.43B | $1.55B |
| Q3 '24 | $7.4B | $1.71B |
| Q4 '24 | $7.37B | $2.29B |
| Q1 '25 | $7.33B | $3.48B |
| Q2 '25 | $4.71B | $2.11B |
| Q3 '25 | $4.68B | $2.05B |
| Q4 '25 | $4.66B | $1.98B |
| Q1 '26 | $1.58B | $2.05B |
| Q2 '26 | $1.05B | $1.58B |
| Q3 '26 | $0.79B | $1.31B |
The sale that was not a signal
Tan's sale looks like a verdict and is not: the Form 4 footnote shows the sales ran under a 10b5-1 plan adopted February 5, 2026, and modified August 14, a schedule written before the drawdown 2. The market's signal is stronger where it comes from institutions. Whale Rock Capital, a $13 billion fund, exited its entire 400,687-share position, worth $256 million on June 30, and the stock has fallen 54% since that date 3.
The cycle the filings bet against
The business behind the sell-off keeps compounding. Revenue in the fiscal first quarter, ended October 2, came in at $4.38 billion, up 55% year on year, with non-GAAP gross margin up 14 points to 58.1% 4. Guidance calls for roughly $5.1 billion of revenue at 60% to 61% gross margin, and the dividend rose 17% to 175 cents 4. Analysts' average target stands at $613, 107% above the price, near 10 times forward earnings 3.
Revenue is up 55% and free cash flow up 130% from a year ago, with a $5.1 billion quarter guided
- Revenue
- Free cash flow
- Estimate
Data
| Revenue | Free cash flow | |
|---|---|---|
| Q4 '23 | $3.03B | -$0.24B |
| Q1 '24 | $1.75B | -$0.04B |
| Q2 '24 | $2B | $0.25B |
| Q3 '24 | $2.21B | -$0.06B |
| Q4 '24 | $2.41B | $0.29B |
| Q1 '25 | $2.29B | $0.38B |
| Q2 '25 | $2.61B | $0.68B |
| Q3 '25 | $2.82B | $0.6B |
| Q4 '25 | $3.02B | $0.65B |
| Q1 '26 | $3.34B | $0.98B |
| Q2 '26 | $3.75B | $1.28B |
| Q3 '26 | $4.38B | $1.38B |
| Q4 '26 guide (estimate) | $5.1B | — |
Two readings of the same facts, covered here two weeks apart: our November 3 piece reported cloud revenue up 54% on a 28% price per terabyte while the stock fell 7.5%, and our October 7 piece counted insiders cashing out of the rally Wall Street still says to buy.
The falsifier is nearline drive pricing
The filings' read, on this evidence, beats the market's: a board that terminates its old loan and signs unsecured debt capacity with an acquisition step-up is betting margins hold, not that they have peaked. What would falsify it is nearline drive pricing, the 28% price-per-terabyte gain that did the margin work; if that turns, margin compresses faster than the 10 times multiple re-rates 4. The next reading is the fiscal second-quarter report in late January, where the $5.1 billion revenue guide and the 60% to 61% margin guide get their first test 4.
What the covenant is underwriting
Cyclicals at 10 times forward earnings can be cheap or peak-priced; the covenant math says the board is underwriting the cheap case, with debt it has not yet drawn 1. The open question the 8-K leaves: what acquisition, and when 1.
Sources: 1. SEC Form 8-K, Western Digital Corp, filed November 16, 2026 (credit agreement dated November 13, 2026) — https://www.sec.gov/Archives/edgar/data/106040/000119312526463554/0001193125-26-463554-index.htm 2. SEC Form 4, Western Digital Corp (Irving Tan), filed November 16, 2026 — https://www.sec.gov/Archives/edgar/data/106040/000126682426000221/0001266824-26-000221-index.htm 3. Yahoo Finance, A $13 Billion Hedge Fund Dumps These 3 Stocks, November 14, 2026 — https://finance.yahoo.com/markets/stocks/articles/13-billion-hedge-fund-dumps-114943050.html 4. Yahoo Finance UK, Up 80%, are Western Digital shares an AI trade hiding in plain sight?, November 15, 2026 — https://uk.finance.yahoo.com/news/80-western-digital-shares-ai-100500178.html
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.
Reader comments
0 comments