Zebra Technologies has $2.58 billion of debt against $182 million of cash, with $1.95 billion due May 2027
Zebra sells the scanners and handhelds the AI buildout runs on, and its filing of November 3 shows who gets paid first: $2.58 billion of debt, mostly due on May 25, 2027, against $182 million of cash, with refinancing promised this quarter and debt service coming out of cash until it closes. The buyback fell to $75 million in the third quarter from $568 million in the first half, so ZBRA shareholders and the lender now compete for the same cash.
 Vincent Jiangthree-minute read
On November 3, Nathan Winters, chief financial officer of Zebra Technologies−1.63% — Zebra Technologies, down 1.63 percent as of its last quote, buried a date in the third-quarter earnings call: "later this month we plan to refinance our credit facility, which is supposed to mature in May of 2027" 1.
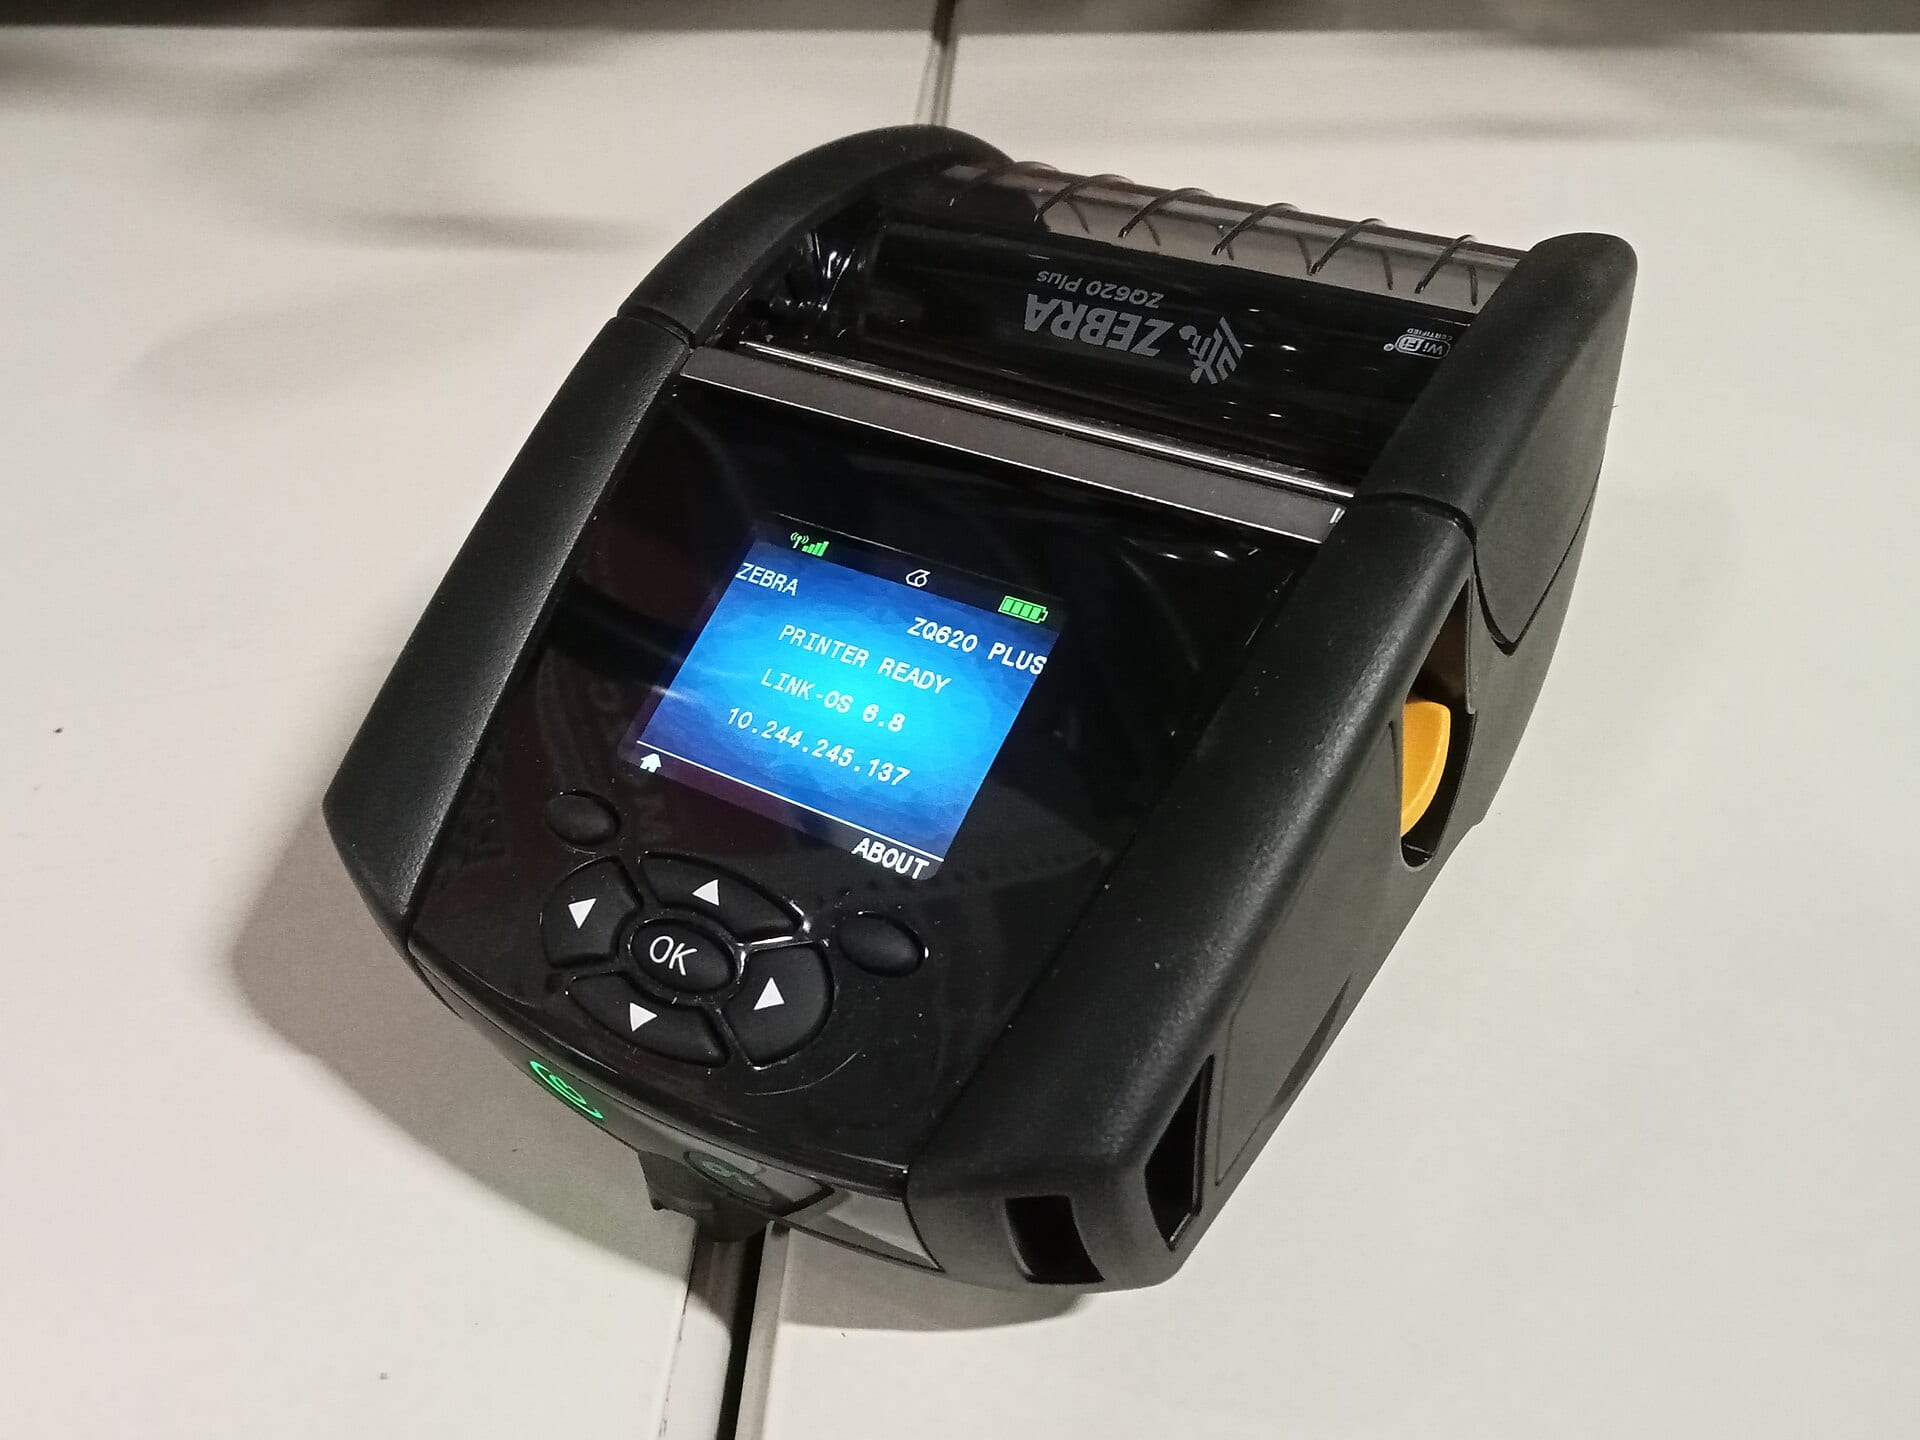
Zebra makes the barcode scanners and handheld computers that warehouses and hospitals run on, and it had just reported a record quarter and raised its outlook 2. The shares fell about 9% to $329.50 anyway 3; the memory bill behind that drop was covered here on November 4. What nobody wrote up is the balance sheet under the quarter.
The bill comes due in May 2027
Zebra closed the quarter with $2,578 million of debt and $182 million of cash 24. Its Term Loan A and revolver, $1,954 million combined, mature on May 25, 2027, and the filing says the company will refinance them this quarter and meet debt payments from cash on hand and operations until the deal closes 2. As the maturity came within twelve months, $1.9 billion of debt moved into the current column, to $2,077 million from $141 million at the end of December 2.
Zebra moved $1.9 billion of debt into current liabilities as May 2027 approached
Debt due within a year rose from $141 million to $2,077 million
- December 31, 2025
- October 3, 2026
Data
| December 31, 2025 | October 3, 2026 | Change | |
|---|---|---|---|
| Current portion of debt | $141M | $2,077M | +1373.0% |
| Long-term debt | $2,361M | $494M | -79.1% |
The buyback slowed and no one said why
Zebra generated $661 million of free cash flow in the first nine months and spent $643 million of it on 2,697,227 of its own shares 2. Only $75 million of that, 229,206 shares, landed in the third quarter, against $568 million in the first two 2. A filing records 1,593,819 shares for $385.31 million repurchased under the February 12 authorization 5, so the program is funded and only the pace changed. On the call, management took a question on capital allocation and never mentioned the slowdown 1.
Cash generation did not become cash
Free cash flow rose to $661 million from $504 million a year earlier 2, yet cash ended at $182 million, down from $1.05 billion 4, with inventory up to $851 million from $729 million at year-end 6.
Zebra's cash fell to $182 million even as free cash flow stayed positive every quarter
Cash is down 83% year over year despite positive free cash flow every quarter
- Cash and equivalents
- Free cash flow
Data
| Cash and equivalents | Free cash flow | |
|---|---|---|
| Q4 2023 | $137M | $102M |
| Q1 2024 | $127M | $111M |
| Q2 2024 | $411M | $278M |
| Q3 2024 | $676M | $277M |
| Q4 2024 | $901M | $288M |
| Q1 2025 | $879M | $158M |
| Q2 2025 | $872M | $130M |
| Q3 2025 | $1,053M | $216M |
| Q4 2025 | $125M | $327M |
| Q1 2026 | $114M | $163M |
| Q2 2026 | $157M | $198M |
| Q3 2026 | $182M | $300M |
The pressure behind those balances is the AI buildout: industry DRAM revenue jumped 369% year over year to nearly $200 billion last quarter, and "buyers are now competing for supply rather than negotiating on price," says Counterpoint Research 7. Zebra's own share of that scarcity is the $145 million of extra memory cost it expects this year, company figures say 1.
The bulls call the debt modest
The MarketBeat note on the sell-off told investors to expect Zebra to "sustain the aggressive pace" of buybacks and called the debt "modestly high", fixable by "diverting free cash flow from buybacks for a short period" 8. Management backs the shrug with leverage of 1.6 times, more than $1 billion of credit capacity and full-year free cash flow guided to at least $1 billion 1.
Sixteen analysts average a $415.25 target against a $322.02 close on November 6 9; since the print, Truist+0.14% — Truist, up 0.14 percent as of its last quote sits at Hold and $375, TD Cowen at Buy and $450 910. The comfort assumes the roll is routine: the filing calls its timing and terms subject to debt-market conditions 2, and the diversion the note prescribed is the one the quarter already shows.
Analyst price targets sit up to 40% above the November 6 close
Data
| Price target | |
|---|---|
| Nov 6 close | $322.02 |
| Truist | $375 |
| 16-analyst average | $415.25 |
| TD Cowen | $450 |
The rate comes first
The facility prices this quarter 2, and its rate will set 2027's interest expense. Tight pricing with the buyback back at its old pace would keep compounding earnings that a nearly 7% smaller share count already helped 8. Wide pricing with repurchases stuck near $75 million a quarter makes the last quarter's 28% adjusted EPS growth harder to repeat 1. The filing and the transcript are linked below. When the facility prices, it will say whose cash this is.
Get Applications by email, free
How AI is changing the software people and companies use. In our daily email, every weekday.