Zoom guided 6% to 8% growth for 2030, but enterprise customers still spend 99 cents of last year's dollar
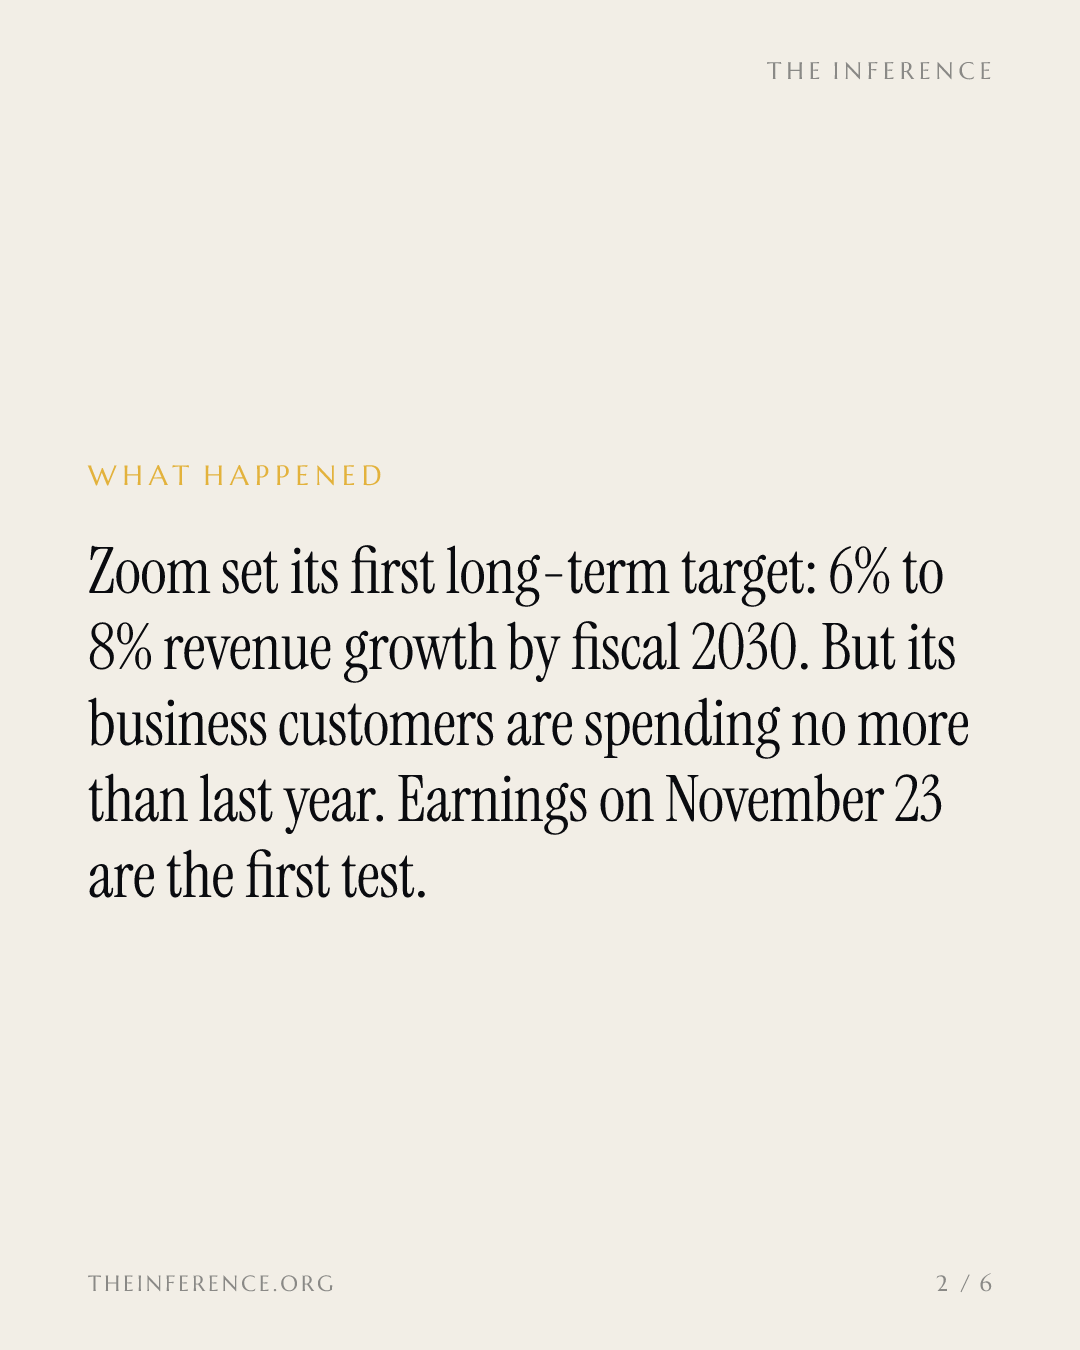
At Zoomtopia on October 27 Zoom guided 6% to 8% revenue growth in fiscal 2030 with a 40% operating margin; the missing fuel is the 71% of enterprise accounts without Zoom Phone and a net dollar expansion rate stuck at 99%.
 Vincent Jiang · 3 min read
Zoom finally put a number on its second act
Zoom−1.25% — Zoom, down 1.25 percent today, the San Jose company that grew 300% in the pandemic and then settled into low single digits, gave its first time-bound long-range target at Zoomtopia 2026 on October 27: total revenue growth of 6% to 8% in fiscal 2030, organic only, with enterprise revenue growing at double digits while online revenue stays roughly flat 1. Chief Financial Officer Michelle Chang paired it with a raised long-term non-GAAP operating margin guide of about 40%, up from 33% to 36% 1.
The first quarterly print under the target lands on November 23, when Zoom reports fiscal third-quarter results after the close 2.
The arithmetic gap sits in one metric
Enterprise net dollar expansion, the measure of how much the installed base spends year over year, stood at 99% at July 31, up one point from 98% a year earlier 3. A base that holds its spend rather than adding it cannot produce double-digit growth on its own. Last quarter total revenue grew 4.9% to $1.28 billion, with enterprise up 7.8% and online up 0.6% 3.
Zoom's revenue growth has stayed between 2% and 6% for ten straight quarters
Data
| Revenue growth YoY (%) | |
|---|---|
| Q1 '24 | 3.2 |
| Q2 '24 | 2.1 |
| Q3 '24 | 3.6 |
| Q4 '24 | 3.3 |
| Q1 '25 | 2.9 |
| Q2 '25 | 4.7 |
| Q3 '25 | 4.4 |
| Q4 '25 | 5.3 |
| Q1 '26 | 5.5 |
| Q2 '26 | 4.9 |
Guidance points down before the first checkpoint
Zoom guided fiscal third-quarter revenue to $1.275 billion to $1.280 billion 3. Against the $1.23 billion reported a year earlier, that is growth of roughly 3.7% to 4.1%, a step down from Q2's 4.9% just as the 2030 plan takes effect 4. The 40% margin, meanwhile, was already the run rate: non-GAAP operating margin printed 40.0% in Q2, so the raise commits to holding a level already achieved 3. The market treated the Q2 beat the same way, sending shares down 2% to 4% after hours 5.
The fuel is the other 71%
Zoom's case is cross-sell. Phone sits in 29% of its Meetings enterprise accounts, Webinar at 27% and Rooms at 17% 1, and dollar churn runs 43% lower for customers on three or more products 1. Contracts are lengthening first: remaining performance obligations rose 14% to about $4.5 billion, driven by a 25% jump in the non-current portion tied to larger, multi-year deals 1.
No Zoom add-on has reached a third of its Meetings enterprise accounts
Data
| Value | |
|---|---|
| Zoom Phone | 29 |
| Zoom Webinar | 27 |
| Zoom Rooms | 17 |
The bull case is real but small-base
The land-and-expand camp has receipts. AI-related contact-center SKUs are growing in the mid-100s percent, Virtual Agent customers rose more than 250% year over year, and 90% of the top 100 contact-center deals were net-new logos 1. But churn reductions and longer contracts do not lift spend per customer on their own. Only the 99% figure does, and it has not moved in either direction worth pricing 13.
What decides it on November 23
Two numbers settle the first reading under the target: whether enterprise growth holds near 8%, and whether net dollar expansion finally beats 99% 3. The Inference reported Zoom's break from per-seat billing on October 21 (link) and its 8.4-times-earnings valuation on October 7 (link); the 2030 target is what is new 3. If both numbers move, 6% to 8% is a compounding story 3. If neither does, it is cross-sell hope carried by cost cuts.
Get Applications by email, free
How AI is changing the software people and companies use. In our daily email, every weekday.