アルトマン氏とアモデイ氏が求める「時間」 その代償を払う企業たち
CoreWeave、Nebius、IREN、WhiteFiberには増設すべき設備があり、担うべき顧客がいる。最先端開発のペースが緩まれば、既存のソフトウエア企業は守られる一方、AIクラウドブームを支える資金調達が試されることになる。
 Vincent Jiang · 5 min read

創業者らが求める「猶予」
サム・アルトマン氏とダリオ・アモデイ氏は、より強力なAIの開発を前に、もう少し時間が欲しいと考えている。設備に資金を融通する投資家にとって、その時間は利払いの増加を意味しかねない。
【検証済み】9月12日、アモデイ氏は最先端AIの能力向上のペースを緩めることと、常設の外部評価者を受け入れることを提唱した。アルトマン氏はX(旧ツイッター)でこの提案を支持し、OpenAIでも同等のアクセスを認めると約束した。イーロン・マスク氏もアモデイ氏の見解を支持した。1,2
【分析】最も恩恵を受けそうなのは既存のソフトウエア企業だ。最もリスクにさらされるビジネスモデルは、計算能力を貸し出す専門事業者「ネオクラウド(neocloud)」である。売上が入る前に拡張資金の調達が必要になる。CoreWeave、Nebius、IREN、WhiteFiberはいずれもこの時間差の問題に直面しているが、財務的な余裕の厚さはそれぞれ異なる。
市場は「誰が払うのか」の仕分けを始めた
【検証済み】9月14日の取引では半導体株が下落し、ソフトウエア株が上昇した。ただし原油や金利をめぐる懸念も相場の重しとなったため、この日の値動きだけでは減速の影響を切り分けられない。3,4
投資の観点で区別すべきは、知能の進歩が減速することと、計算能力への購買が減速することの違いだ。両者は同時に起こりうる。だが、どちらかが他方を保証するわけではない。
既存モデルを顧客のために動かす「推論(inference)」と呼ばれる仕事は、最先端モデルの研究者が次世代モデルの検証に長く時間をかける間も、成長を続けられる。そうなればAI支出の中身は変わっていく。際限なく大型化する学習を急ぐ圧力は薄れ、確実な提供がより重視されるようになるだろう。これはあくまでシナリオであり、発表済みの支出削減ではない。
何が合意され、何は合意されていないのか
【一次資料】アモデイ氏は一律の学習停止を明確に除外している。Anthropicが直ちに約束したのは評価者の社内受け入れだ。業界全体の協調や国際合意は、提案された次の段階にとどまる。学習用計算資源に上限を設ける可能性は、交渉の課題という位置づけだ。1
アモデイ氏が「6~12カ月以内に暴走したAIエージェントがインターネットを席巻する可能性がある」と警告したのは、あくまで予測であって確定した日程ではない。1
ビジネス上の推論は居心地が悪い。挑戦者の足を鈍らせ、コンプライアンスコストを押し上げる規則は、現在リードする大手AI開発企業を守りうるからだ。ただし、それが不正な動機を立証するわけではない。デビッド・サックス氏は政府が後押しする協調の要求に異を唱え、「カルテル」だと評したが、これはあくまで非難であり、法的認定ではない。5
アルトマン氏はその後、ペース緩和は停止を意味しないと説明した。この発言で、緩和と停止の線引きが一層重要になる。公の場での支持表明が裏付けるのは方向性での一致であって、拘束力のある世界規模の支出凍結ではない。6
猶予を得る銘柄、支払いを迫られる銘柄
【シナリオ分析】以下は、実効性のあるペース緩和が起きた場合の各社の事業への相対的な影響度であり、株価目標でも、対象銘柄が割安だという主張でもない。
| 銘柄 | 潜在的な影響 | 見立てが覆る要因 |
|---|---|---|
| セールスフォース(CRM)、サービスナウ(NOW)、アドビ(ADBE) | 最も明確な猶予効果。より強力なAIエージェントが既存のワークフローを置き換える前に、顧客維持、AIの組み込み、サブスクリプション価格の防衛に充てる時間が増える。 | 現行モデルが、既にこれらの企業を破壊できるだけの能力を備えている可能性がある。進歩の鈍化は、各社自身のAI製品の競争力をも弱めかねない。17 |
| クラウドストライク(CRWD)、パロアルト・ネットワークス(PANW) | 企業がネットワークの堅牢化を進め、AIエージェントのアクセスを統制すれば、セキュリティ支出がさらに膨らむ可能性がある。 | モデルのアライメント研究が、そのままエンドポイントやファイアウォールの売上になるわけではない。契約の伸びで見立てを裏付ける必要がある。7 |
| CoreWeave(CRWV) | 将来のGPUレンタルが弱り、確定した資本支出と大幅な利息費用が重くのしかかる場合に、直接的な影響を受ける。10 | 既存契約と推論需要で稼働率を維持できる。8,9 |
| Nebius(NBIS) | 急速な拡大を進めるため、新規設備の稼働、課金、顧客からの入金のタイミングが死活的に重要になる。11 | 見込み段階の顧客前払い金と契約済み需要で、設備建設費の一部を賄える。11 |
| IREN(IREN)、WhiteFiber(WYFI) | 次回のGPU配備では、受注の減少や不利な資金調達条件に直面しかねない。20,22 | IRENは2026年分の処理能力がほぼ完売と発表。WhiteFiberは複数年のクラウド契約を抱える。20,22 |
| エヌビディア(NVDA)、ブロードコム(AVGO)、Vertiv(VRT) | 顧客がアクセラレーター(AI半導体)やネットワーク、電源・冷却装置の発注を削れば影響が出る。15,16 | 安全性の研究にも推論にもインフラは必要だ。エヌビディアのデータセンター売上のすべてを、最先端モデルの学習に分類することはできない。12 |
| アルファベット(GOOGL)、マイクロソフト(MSFT) | 資本支出の圧縮で既存の収益を維持できれば、キャッシュフローの負担が軽くなる可能性がある。 | 両社はクラウド容量やAI製品も販売している。成長の逸失やインフラの遊休化が、節約効果を上回りかねない。 |
| ソフトバンクグループ(9984.T) | 別のリスク。アルトマン氏が2026年のOpenAIの新規株式公開(IPO)を否定したことで、同社に出資する投資家にとっての潜在的な換金の機会が遠のいた。4,18 | 上場の先送りは、OpenAIの基礎的な価値が下がったことを裏付けるものではない。 |
ネオクラウドには、それぞれの時計がある
資金負担の実態を最もはっきり示すのはCoreWeaveだ。6月30日に終了した四半期について会社側が報告した未監査の決算では、売上高25億8000万ドルに対して設備投資は約94億ドルで、約3.6倍に達した。8,9
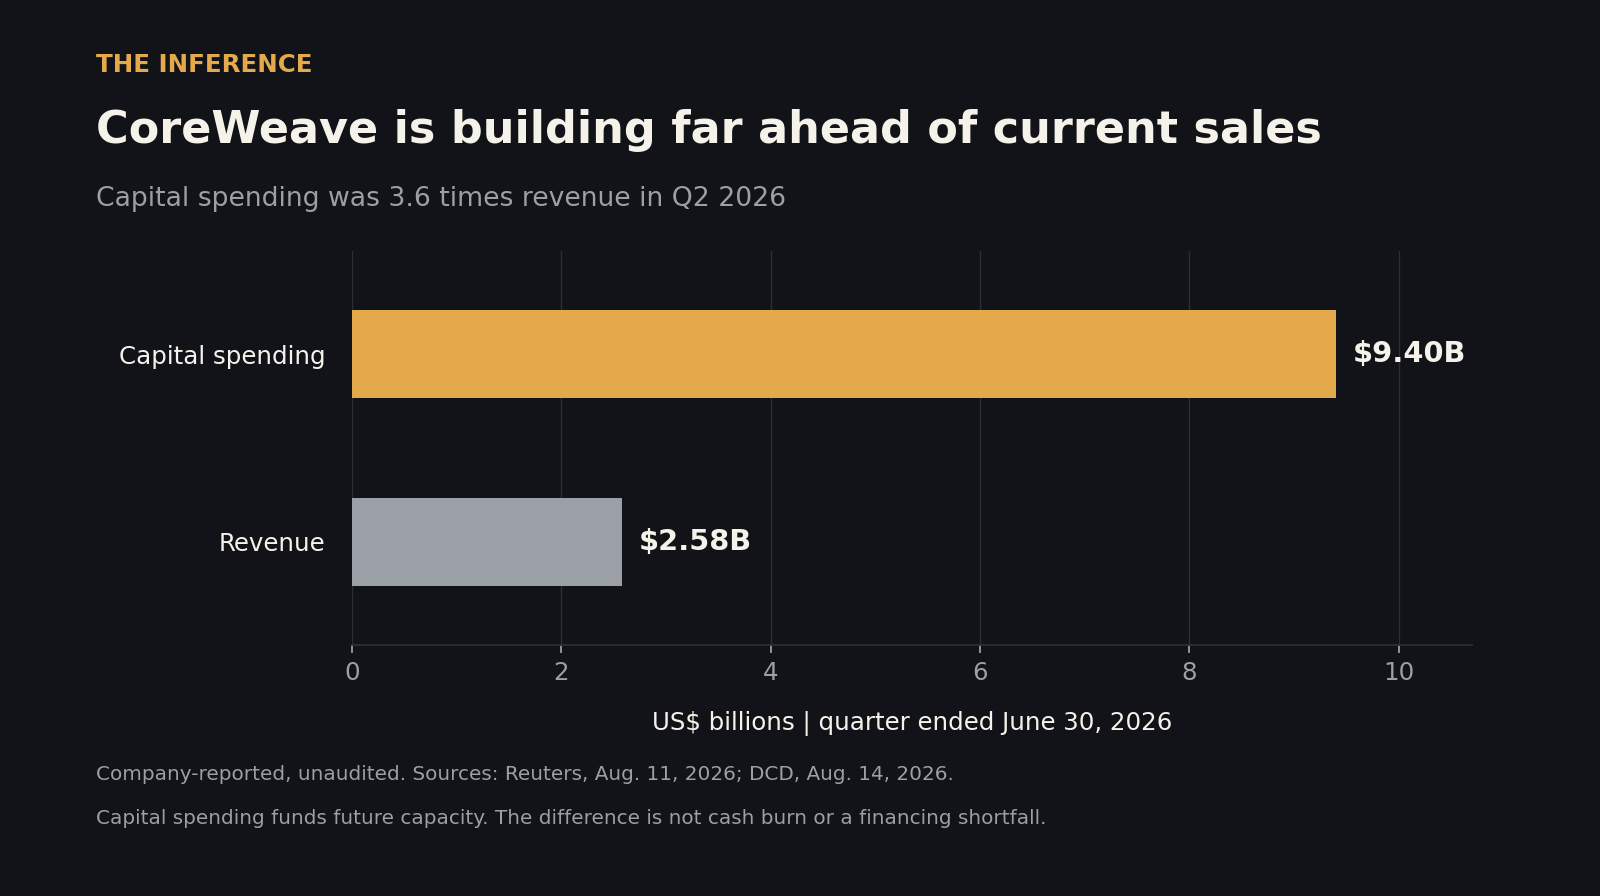
未監査の提出書類によると、同社の四半期の純支払利息は6億4000万ドルで、売上高の約25%に相当する。あくまで費用どうしの比較であって、債務償還余裕比率を示すものではない。10,14
つまり、既存契約が消えるよりずっと前に、将来の受注の減少は株式価値を傷つけうる、ということだ。本稿は、本メディアが先に検証したCoreWeaveの資金負担の考察をさらに進めたものである。
Nebiusは売上に先行して設備を積み上げている。6月に終了した四半期の未監査の数値では、設備投資は約57億ドルに対し、売上高は5億8230万ドルで、四半期売上高の約10倍に当たる。これは現在の売上高に対する投資規模の指標であり、キャッシュバーンや支払不能リスクを測るものではない。11,19
Data
| Value | |
|---|---|
| CoreWeave | 3.6x |
| Nebius | ~10x |
肝心なのは資金余力の厚みだ。Nebiusは8月、2026年の顧客の前払い金が90億ドル超になるとの見通しと、400億ドル超の顧客契約(コミットメント)を確保していることを明らかにした。見込みの前払い金は、すでに回収した現金ではない。11 弱気シナリオが現実となるには、新規契約、入金時期、将来のレンタル採算のどこかが悪化しなければならない。最先端の進歩が緩んでも、既存モデルを顧客に提供する仕事は残り、Nebiusは忙しくあり続けられるだろう。
IRENは新規事業を融資で支えている。同社はビットコインのマイニングからAIクラウドサービスへと事業の軸足を移しつつある。ロイターが8月28日に報じたところでは、同社はAIチップの購入に充てる28億ドルの新規融資を確保し、社名を明かしていない最先端AI開発企業との複数年契約を結んだ。IRENは、2026年の計算能力はほぼ売り切れていると明らかにしている。20,21 ここでリスクにさらわれるのは、その後に続く設備の需要だ。既存顧客の支払いが続いていても、受注が鈍れば次の増強の資金調達は難しくなり得る。
WhiteFiberは契約を課金できる設備に変えていかなければならない。GPUクラウドとコロケーション(データセンター内の設置スペース貸し)を手がける同社は8月、5月以降に総額5億4000万ドル超の複数年のクラウド契約を新たに結んだと発表した。一部の配備は2027年の稼働を目指す。22,23 これは複数年に分散した契約額であって、現在の売上高ではない。8月の提出書類には、残る資金調達と設備提供の節目が記されていた。23 契約で確保した需要は守りになる。それでも将来のレンタル需要が弱れば、追加拡張の採算を損ないかねない。
共通するリスクは、売上高が入る前に支出を確定させていることだ。CoreWeaveは支払利息の形でこの負担がとりわけ見えやすい。残る3社は、資金調達、設備の提供、顧客からの入金をそれぞれ個別に評価する必要がある。
急落への最有力の反論
安全性を巡る主張には、それ自体の重みがある。アモデイ氏は、安全策がAIの能力向上に追いつかなくなっていると主張する。重大な事故を避けられれば、顧客の信頼と、業界が事業を続けられる基盤を守れる可能性がある。氏の提案は、中国に後れを取らないまま減速する難しさも認めている。1
しかも、インフラ擁護論には裏付けの数字がある。CoreWeaveは6月30日時点の受注残が1042億ドルに達したと発表。経営陣は、推論需要が拡大しているほか、旧世代チップへの需要も続いていると説明した。ただし、これらはあくまで会社側の主張であり、将来の1ドルのすべてが必ず入る証拠ではない。8,9
既存のモデルがより安全で、より有用になれば、普及の拡大が最先端モデルの学習にはもう不要となる計算能力を吸収できるかもしれない。ハードウエアの弱気シナリオが成り立つには、支出か価格のどちらかが悪化する必要がある。Xでの支持表明は、そのいずれも裏付けるものではない。
講演の次は受注を注視
アルトマン氏は9月15日、Dreamforceで講演する予定で、実施内容を具体化する直近の機会となる。13
そのうえで見極めるのは、評価者の任命、実際に課される能力制限、設備投資予算の見直し、レンタル契約の更新だ。ネオクラウド各社については、顧客の前払い金の入金、配備の時期、資金調達の条件も加えて見る必要がある。ソフトウエア側で恩恵を受ける企業は、顧客の維持と価格の持ちこたえが前提となる。インフラ供給企業は、受注なくして生き残れない。
最先端は待てる。利息のメーターは待てない。
How this brief was made
01Gathered & sourced356 channels · 1,829 articles▾
Agents swept 356 channels and ingested 1,829 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated23 claims · 33 data feeds▾
Every one of 23 load-bearing claims was checked against primary sources, with 33 live data feeds reconciling the figures and charts.
- 1Dario Amodei's pacing proposal, Sep 12 2026 (primary personal essay: evaluator commitment, the distinction from a training halt, possible future compute limits, and a six-to-twelve-month risk forecast that is his projection, not an established timetable; the site's month-only date is cross-checked against contemporaneous reporting).
- 2Bloomberg on Amodei, Altman and Musk backing slower development, Sep 12 2026 (Kevin Whitelaw and Seth Fiegerman; corroborates Altman's evaluator pledge and Musk's endorsement. The link is a Bloomberg syndication, not a second independent outlet).
- 3Reuters on the chip-versus-software rotation, Sep 14 2026 (direction of the intraday move only; the analyst interpretations are opinion, and no closing return or causal decomposition is claimed).
- 4Associated Press on AI shares, oil and bond yields, Sep 14 2026 (independent corroboration of the broader market pressures; only the oil and rates context is used, and intraday figures move).
- 5David Sacks on X, Sep 12 2026 (primary opinion, corroborated by The Stack's Sep 13 report; a regulatory-capture accusation, not a finding that any firm broke competition law. Direct X retrieval was restricted).
- 6Axios on Altman's clarification that pacing is not stopping, Sep 14 2026 (used for that narrow statement only; direct-post retrieval remains restricted).
- 7Business Insider on investor views of cybersecurity spending, Sep 10 2026 (Jennifer Sor's reporting, syndicated by Yahoo; named investor opinion supporting the security-budget mechanism, not an earnings forecast).
- 8Reuters on CoreWeave's Q2 results and raised spending plan, Aug 11 2026 (company-claimed and unaudited: $2.58B revenue, $9.4B capex, $104.2B backlog, quarter ended June 30. The 3.6x ratio is computed here).
- 9Data Center Dynamics on the Q2 neocloud results, Aug 14 2026 (independent reporting of the same company figures, not independent measurement: CoreWeave capex and revenue, management's inference-growth and older-GPU claims, and Nebius concentration).
- 10CoreWeave SEC Form 10-Q for the quarter ended Jun 30 2026 (primary, unaudited: revenue $2,575M and net interest expense $640M. $640M / $2,575M = 24.85%, rounded to 25%. Net interest expense is neither cash interest nor a coverage ratio).
- 11Reuters on Nebius's expansion and prepayments, Aug 12 2026 (company-claimed and unaudited June-quarter revenue of $582.3M against capex near $5.7B; forecast of more than $9B of 2026 customer prepayments and more than $40B of commitments. Forecast prepayments are not cash collected).
- 12Nvidia SEC Form 10-Q for the quarter ended Jul 26 2026 (primary record that both training and inference drive demand; no numerical split between them is disclosed).
- 13Fortune on Altman's safety discussion and Dreamforce appearance, Sep 12 2026 (single-source schedule detail for Sep 15; an appearance is not a promised announcement).
- 14The Motley Fool transcript of CoreWeave's Aug 11 earnings call, published Aug 18 2026 (management statements corroborating the filed interest expense; a record of what was said, not separate measurement).
- 15Yahoo Finance on Broadcom's results and AI semiconductor business, Sep 2 2026 (Ines Ferre's reporting, supporting the custom-accelerator and networking exposure; no figure or return is reproduced).
- 16Vertiv SEC earnings exhibit for the quarter ended Jun 30 2026, filed Jul 29 (primary record of the power and cooling supplier's role; no financial figure is used).
- 17Reuters on ServiceNow's AI-driven subscription growth, Jul 22 2026 (independent reporting behind the two-sided software thesis; the stock implication remains our analysis).
- 18Business Insider on Altman ruling out a 2026 OpenAI IPO, Sep 12 2026 (Truman Dickerson on the Fortune interview, syndicated by Yahoo and corroborated by source 4; it establishes no 2027 date and no guaranteed SoftBank secondary).
- 19Nebius SEC results exhibit for the quarter ended Jun 30 2026, filed Aug 12 (primary cross-check: revenue $582.3M and purchases of property, equipment and intangibles of $5,657.4M. The 9.72x ratio is a scale comparison, not cash burn; capex definitions are not normalized across companies).
- 20Reuters on IREN's frontier-lab contract and chip financing, Aug 28 2026 (Anzar Mehraj and Deborah Sophia, syndicated by The Economic Times: company-reported $2.8B of new AI chip financing, an unnamed lab agreement and largely sold-out 2026 capacity. Financing secured is not all drawn debt).
- 21IREN SEC FY26 results exhibit, Aug 27 2026 (primary corroboration of source 20, covering both training and inference services; it does not identify the unnamed customer, and contracted annualized revenue is not realized revenue).
- 22Zacks Equity Research on WhiteFiber's cloud contracts, Aug 13 2026 (earnings-call coverage syndicated by Yahoo; company-claimed agreements above $540M since the May call, some targeting 2027 deployment. Aggregate multiyear values, not current revenue).
- 23WhiteFiber SEC Form 10-Q for the quarter ended Jun 30 2026, filed Aug 12 (primary corroboration of the new agreements and deployment dates; financing documents were not definitive as of that filing, and no claim is made about their status on Sep 14. The $28.8M quarterly revenue included a $12.3M termination fee, so it is not used as recurring-growth evidence).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.