奥特曼与阿莫代伊呼吁放缓AI进程,这些公司却要为此买单
CoreWeave、Nebius、IREN和WhiteFiber手握待建产能与待服务客户。前沿AI进展放缓或可保护软件业现有巨头,同时考验AI云服务繁荣背后的融资逻辑。
 Vincent Jiang · 5 min read

两位创始人呼吁留出喘息空间
山姆·奥特曼与达里奥·阿莫代伊希望在构建更强大AI之前获得更多时间。对为设备融资的投资者而言,更多时间可能意味着更多利息。
事实核查: 9月12日,阿莫代伊提议放缓前沿能力提升速度,并引入常设外部评估员。奥特曼在X平台上支持该提议,并承诺在OpenAI提供同等访问权限。埃隆·马斯克也对阿莫代伊的立场表示赞同。1,2
分析: 最明确的潜在受益者是成熟的软件供应商。风险最高的商业模式是新兴云服务商(neocloud):这类专业公司租赁计算产能,其扩张需要在收入到账前完成融资。CoreWeave、Nebius、IREN和WhiteFiber都面临这一时间问题,但各自的财务缓冲垫不同。
市场开始厘清账单
事实核查: 9月14日交易时段,芯片股下跌,而软件股上涨。油价与利率担忧同样对市场构成压力,因此当日盘面无法单独归因于放缓效应。3,4
关键的区别在于:智能提升放缓与计算能力采购放缓。两者可能同时发生,但彼此并不保证。
为客户运行现有模型(即推理)的需求可能持续增长,而前沿研究者则需花费更长时间测试后续版本。这将使AI支出的结构发生变化:对更大规模训练运行的需求紧迫性降低,对可靠部署的重视提升。这是一种情景推演,并非已宣布的开支削减。
X平台(指推特)上同意了什么,未同意什么
原始记录: 阿莫代伊明确排除了全面暂停训练。Anthropic的立即承诺是关于嵌入式评估员;行业协调与国际协议仍是下一步的提案。对训练算力的潜在限制则是谈判议题。1
他关于“流氓智能体”可能在六到十二个月内覆盖互联网的警告,是一项预测,而非既定时间表。1
由此得出的商业推论令人不安:那些放慢挑战者步伐并提高合规成本的规则,可能保护了当今的领先实验室。但这并不能证明存在不当动机。大卫·萨克斯曾质疑政府协调的需求;他提出的“卡特尔”定性是项指控,并非法律裁定。5
奥特曼随后澄清,“调整节奏”不等于“停止”,这使得边界至关重要。公开表态确立的是方向上的一致,而非具有强制力的全球支出冻结。6
有时间收益、也有账单要付的股票
情景分析: 以下是在有意义的“调整节奏”发生时,相关企业面临的相对业务风险,并非股价目标或认为股票便宜的论断。
| 股票 | 潜在影响 | 可能推翻的因素 |
|---|---|---|
| 赛富时(CRM)、赛维铁科(NOW)、奥多比(ADBE) | 最明确的喘息机会:在更强大的智能体能取代现有工作流程前,有更多时间留住客户、整合AI并捍卫订阅定价。 | 当前模型可能已足够强大足以颠覆它们。进步放缓也可能削弱它们自身的AI产品。17 |
| CrowdStrike(CRWD)、帕洛阿尔托网络(PANW) | 随着企业加固网络并监控智能体访问,可能带来额外的安全支出。 | 模型对齐研究不会自动转化为终端或防火墙收入。合同增长必须证实这一逻辑。7 |
| CoreWeave(CRWV) | 若未来GPU租赁需求减弱,与资本承诺及高额利息支出形成碰撞,将直接暴露风险。10 | 现有合同和推理需求或可维持设备利用率。8,9 |
| Nebius(NBIS) | 快速扩张使得新产能、计费与客户付款的时间点至关重要。11 | 预期的客户预付款和已签约需求可为部分扩张提供资金。11 |
| IREN(IREN)、WhiteFiber(WYFI) | 下一轮GPU部署可能面临更弱的订单或更差的融资条件。20,22 | IREN报告2026年产能基本售罄;WhiteFiber拥有多年期云协议。20,22 |
| 英伟达(NVDA)、博通(AVGO)、维谛技术(VRT) | 若客户削减加速器、网络、电力或冷却设备订单,将面临风险。15,16 | 安全工作与推理仍需要基础设施。英伟达的数据中心销售不能全部归类为前沿训练。12 |
| 字母表(GOOGL)、微软(MSFT) | 若资本支出降低能保全现有收入,可能带来现金流改善。 | 它们同时也销售云产能和AI产品。增长损失或基础设施闲置可能抵消节省的资金。 |
| 软银集团(9984.T) | 另有一重风险:奥特曼排除了OpenAI在2026年进行IPO的可能,这将推迟该公司一位投资者潜在的流动性事件。4,18 | 上市推迟并不表明OpenAI的基本面价值已经下跌。 |
新兴云服务商自有其时间表
CoreWeave提供了融资负担最清晰的证据。其截至6月30日的季度公司报告、未经审计的业绩显示,资本支出约94亿美元,而收入为25.8亿美元,前者约为后者的3.6倍。8,9
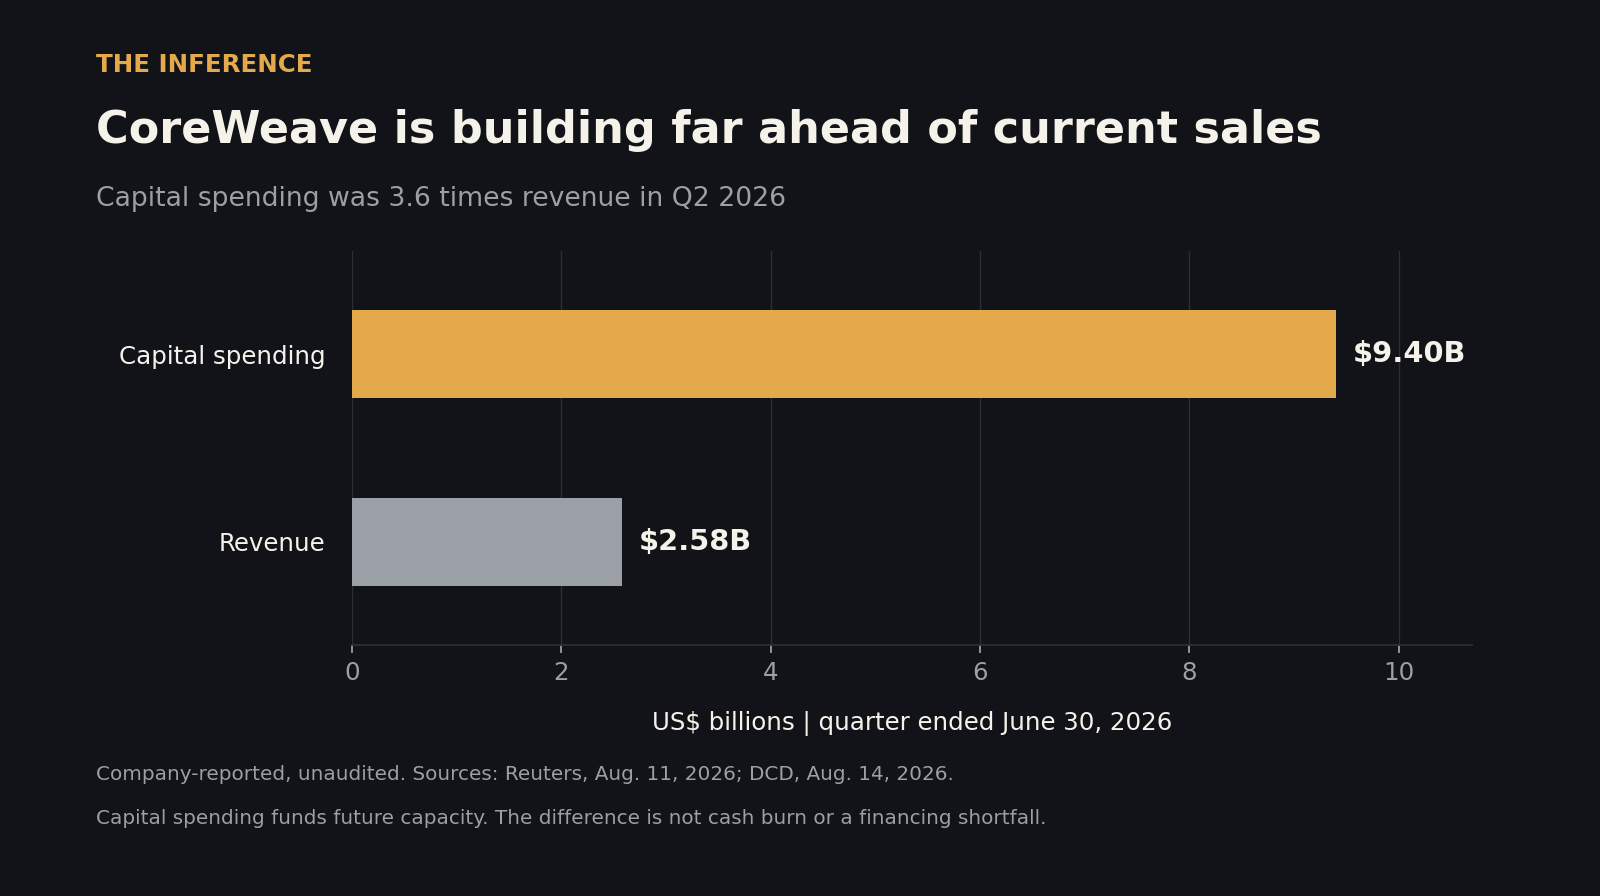
根据其未经审计的申报文件,季度净利息支出为6.4亿美元,约占收入的25%。这是一项支出对比,并非偿债覆盖率。10,14
这意味着,未来订单减少可能远在现有合同到期之前就已损害股权价值。这延续了我们此前对CoreWeave融资负担的审视。
Nebius正在收入到来前进行建设。 其未经审计的6月季度数据显示,资本支出约57亿美元,而收入为5.823亿美元,约为季度销售额的十倍。这衡量的是相对于当前销售额的投资,而非现金消耗或破产风险。11,19
Data
| Value | |
|---|---|
| CoreWeave | 3.6x |
| Nebius | ~10x |
缓冲垫很重要:Nebius在8月表示,预计2026年将收到超过90亿美元的客户预付款,并已获得超过400亿美元的客户承诺。预期的预付款并非已到账现金。11 看空其股票的论点需要假设新合同、付款时间或未来租赁经济性出现恶化。即便前沿发展放缓,Nebius仍可能忙于服务现有模型。
IREN正在为一项新业务融资。 该公司正从比特币挖矿转向AI云服务。路透社8月28日报道称,其已获得280亿美元的新融资用于购买AI芯片,并与一家未具名的前沿实验室签署了多年协议。IREN称其2026年计算产能已基本售罄。20,21 暴露的风险变量是对后续产能的需求:更弱的订单可能使下一轮扩张融资变得困难,即便现有客户仍在付费。
WhiteFiber必须将合同转化为可计费产能。 这家GPU云及托管服务提供商在8月报告称,自5月以来已签署价值超过5.4亿美元的多年期新云协议,部分部署目标定在2027年。22,23 这些是分摊至数年的合同金额,并非当前收入。其8月申报文件描述了待完成的融资和交付里程碑。23 已签署的需求提供了一定保护;但更弱的未来租赁需求仍可能削弱进一步扩张的经济效益。
共同的风险在于:支出承诺先于收入到来。CoreWeave的利息支出使这一负担尤为明显;其他公司则需要就其融资、交付和客户付款情况做各自评估。
反对抛售的最有力论据
安全理由应被充分重视:阿莫代伊认为,安全措施正落后于能力发展。避免一次严重事故,或可维护客户信任及行业的持续运营能力。他的提案也承认,在放慢脚步的同时不落后于中国存在困难。1
而基础设施需求的辩护有据可查。CoreWeave报告称,截至6月30日,积压订单达1042亿美元,管理层同时描述了推理需求的增长以及对旧款芯片的持续需求。这些仍是公司的说法,并非未来每一分钱都会到账的证明。8,9
如果现有模型变得更安全、更有用,其采用可能会吸收前沿训练不再需要的产能。硬件股看空论点要求支出或定价走弱;X平台上的一个表态并不能确立其中任何一项。
演讲之后,盯紧订单
奥特曼计划于9月15日在Dreamforce大会上发表演讲,这是一个阐明具体实施细节的即时机会。13
此后,请关注评估员任命、实际的能力限制措施、修订后的资本预算和租赁续约情况。对于新兴云服务商,还需关注客户预付款到账情况、部署日期和融资条款。软件受益方需要留住客户并维持定价。基础设施供应商则需要订单来支撑业绩。
前沿发展可以等待;利息计时器却不能。
How this brief was made
01Gathered & sourced356 channels · 1,829 articles▾
Agents swept 356 channels and ingested 1,829 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated23 claims · 33 data feeds▾
Every one of 23 load-bearing claims was checked against primary sources, with 33 live data feeds reconciling the figures and charts.
- 1Dario Amodei's pacing proposal, Sep 12 2026 (primary personal essay: evaluator commitment, the distinction from a training halt, possible future compute limits, and a six-to-twelve-month risk forecast that is his projection, not an established timetable; the site's month-only date is cross-checked against contemporaneous reporting).
- 2Bloomberg on Amodei, Altman and Musk backing slower development, Sep 12 2026 (Kevin Whitelaw and Seth Fiegerman; corroborates Altman's evaluator pledge and Musk's endorsement. The link is a Bloomberg syndication, not a second independent outlet).
- 3Reuters on the chip-versus-software rotation, Sep 14 2026 (direction of the intraday move only; the analyst interpretations are opinion, and no closing return or causal decomposition is claimed).
- 4Associated Press on AI shares, oil and bond yields, Sep 14 2026 (independent corroboration of the broader market pressures; only the oil and rates context is used, and intraday figures move).
- 5David Sacks on X, Sep 12 2026 (primary opinion, corroborated by The Stack's Sep 13 report; a regulatory-capture accusation, not a finding that any firm broke competition law. Direct X retrieval was restricted).
- 6Axios on Altman's clarification that pacing is not stopping, Sep 14 2026 (used for that narrow statement only; direct-post retrieval remains restricted).
- 7Business Insider on investor views of cybersecurity spending, Sep 10 2026 (Jennifer Sor's reporting, syndicated by Yahoo; named investor opinion supporting the security-budget mechanism, not an earnings forecast).
- 8Reuters on CoreWeave's Q2 results and raised spending plan, Aug 11 2026 (company-claimed and unaudited: $2.58B revenue, $9.4B capex, $104.2B backlog, quarter ended June 30. The 3.6x ratio is computed here).
- 9Data Center Dynamics on the Q2 neocloud results, Aug 14 2026 (independent reporting of the same company figures, not independent measurement: CoreWeave capex and revenue, management's inference-growth and older-GPU claims, and Nebius concentration).
- 10CoreWeave SEC Form 10-Q for the quarter ended Jun 30 2026 (primary, unaudited: revenue $2,575M and net interest expense $640M. $640M / $2,575M = 24.85%, rounded to 25%. Net interest expense is neither cash interest nor a coverage ratio).
- 11Reuters on Nebius's expansion and prepayments, Aug 12 2026 (company-claimed and unaudited June-quarter revenue of $582.3M against capex near $5.7B; forecast of more than $9B of 2026 customer prepayments and more than $40B of commitments. Forecast prepayments are not cash collected).
- 12Nvidia SEC Form 10-Q for the quarter ended Jul 26 2026 (primary record that both training and inference drive demand; no numerical split between them is disclosed).
- 13Fortune on Altman's safety discussion and Dreamforce appearance, Sep 12 2026 (single-source schedule detail for Sep 15; an appearance is not a promised announcement).
- 14The Motley Fool transcript of CoreWeave's Aug 11 earnings call, published Aug 18 2026 (management statements corroborating the filed interest expense; a record of what was said, not separate measurement).
- 15Yahoo Finance on Broadcom's results and AI semiconductor business, Sep 2 2026 (Ines Ferre's reporting, supporting the custom-accelerator and networking exposure; no figure or return is reproduced).
- 16Vertiv SEC earnings exhibit for the quarter ended Jun 30 2026, filed Jul 29 (primary record of the power and cooling supplier's role; no financial figure is used).
- 17Reuters on ServiceNow's AI-driven subscription growth, Jul 22 2026 (independent reporting behind the two-sided software thesis; the stock implication remains our analysis).
- 18Business Insider on Altman ruling out a 2026 OpenAI IPO, Sep 12 2026 (Truman Dickerson on the Fortune interview, syndicated by Yahoo and corroborated by source 4; it establishes no 2027 date and no guaranteed SoftBank secondary).
- 19Nebius SEC results exhibit for the quarter ended Jun 30 2026, filed Aug 12 (primary cross-check: revenue $582.3M and purchases of property, equipment and intangibles of $5,657.4M. The 9.72x ratio is a scale comparison, not cash burn; capex definitions are not normalized across companies).
- 20Reuters on IREN's frontier-lab contract and chip financing, Aug 28 2026 (Anzar Mehraj and Deborah Sophia, syndicated by The Economic Times: company-reported $2.8B of new AI chip financing, an unnamed lab agreement and largely sold-out 2026 capacity. Financing secured is not all drawn debt).
- 21IREN SEC FY26 results exhibit, Aug 27 2026 (primary corroboration of source 20, covering both training and inference services; it does not identify the unnamed customer, and contracted annualized revenue is not realized revenue).
- 22Zacks Equity Research on WhiteFiber's cloud contracts, Aug 13 2026 (earnings-call coverage syndicated by Yahoo; company-claimed agreements above $540M since the May call, some targeting 2027 deployment. Aggregate multiyear values, not current revenue).
- 23WhiteFiber SEC Form 10-Q for the quarter ended Jun 30 2026, filed Aug 12 (primary corroboration of the new agreements and deployment dates; financing documents were not definitive as of that filing, and no claim is made about their status on Sep 14. The $28.8M quarterly revenue included a $12.3M termination fee, so it is not used as recurring-growth evidence).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.