AppLovin平台开放了,广告主的功课还没做完
亚当·福鲁吉说,AppLovin广告系统最难的一环,仍是把广告做出来。对一家同比增速53%、正试图拓展游戏广告主之外客户的公司来说,这就是扩张路上的约束。
 Vincent Jiang · 2 min read
8月5日,亚当·福鲁吉(Adam Foroughi)对分析师表示,AppLovin广告系统中最大的难关,仍然是把广告做出来。4
标题背后的营收
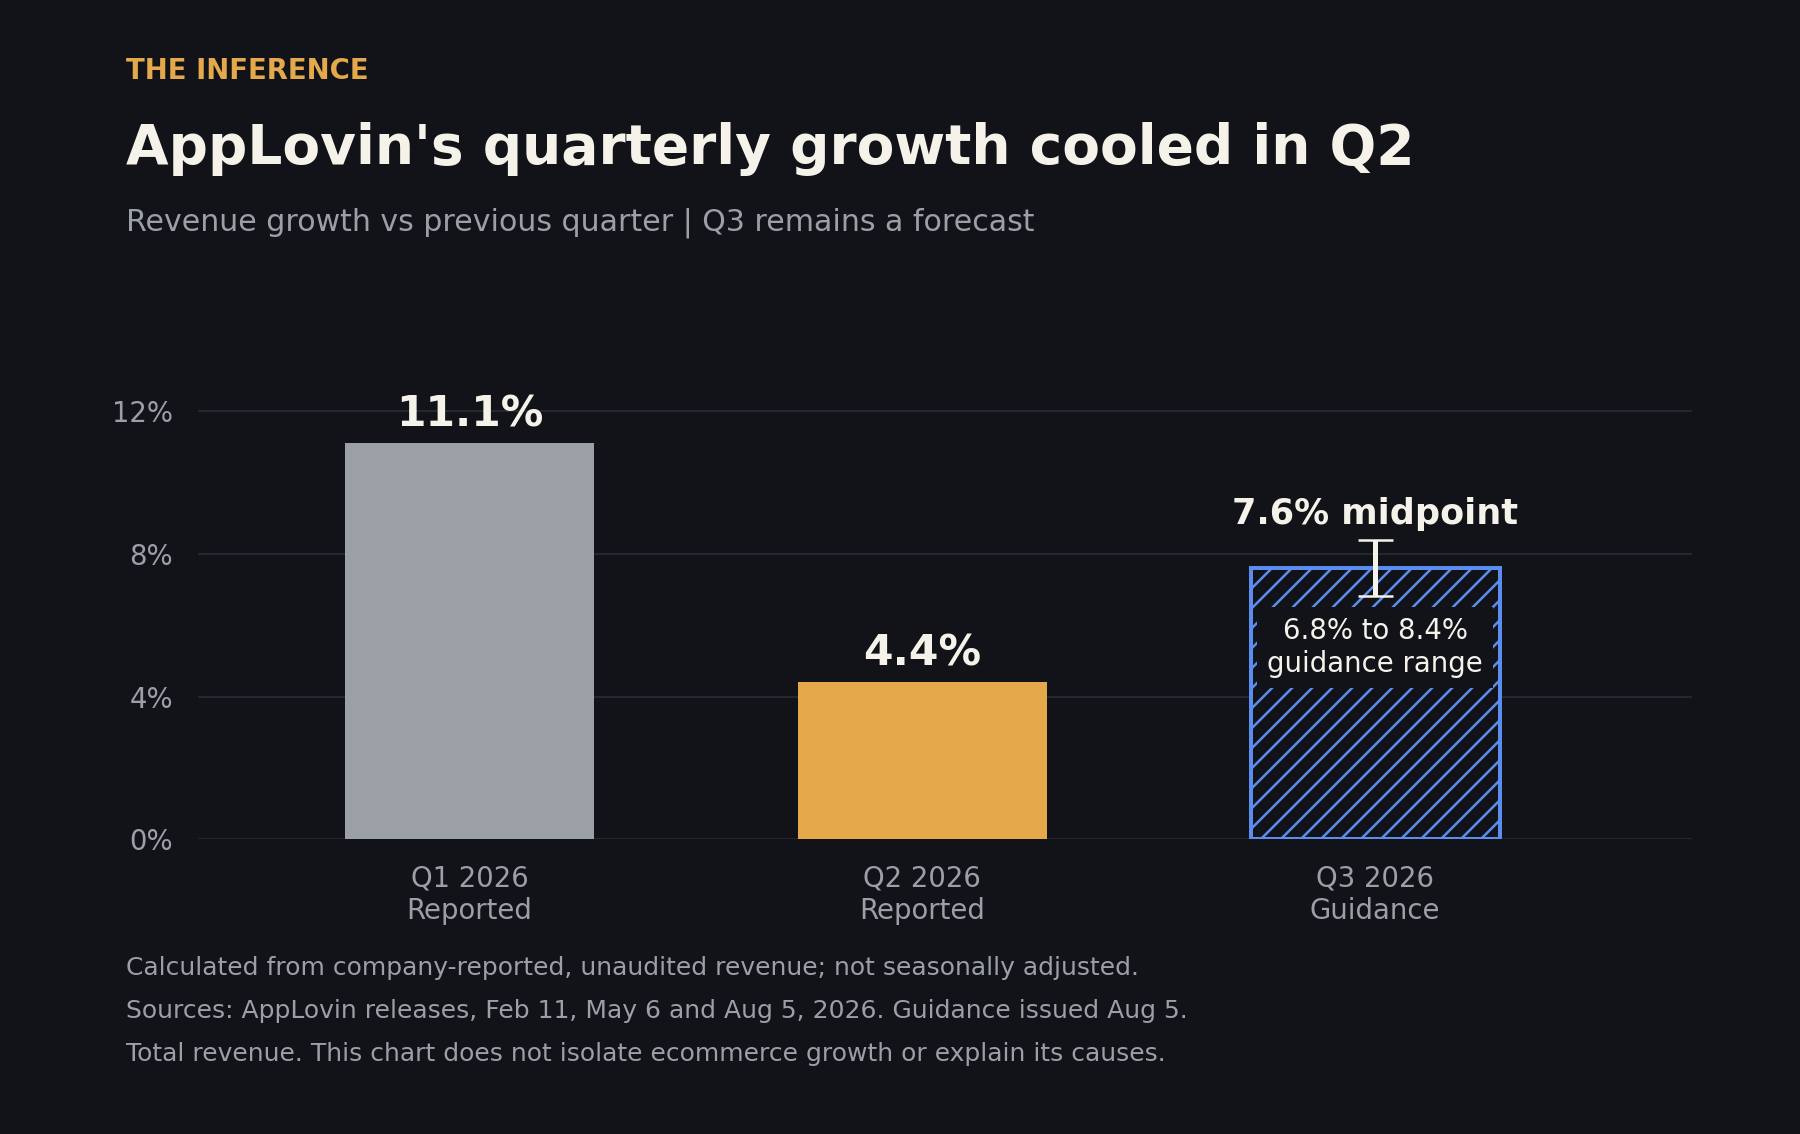
这句话对一门季度营收19.24亿美元、同比增长53%的生意来说分量不轻。上述数字是AppLovin 8月5日发布的未经审计业绩;将业务拓展到游戏广告主之外,是其下一个增长机会的一部分。1
分析师已在给这个故事"打折"
9月14日,摩根士丹利将AppLovin目标价从650美元下调至450美元,同时维持“增持”评级。此前,Evercore已于9月1日下调目标价,并承认其对电商广告主历史投放支出的估算偏高。以上均属分析师的判断,并非新的经营业绩。7,8
广告主先要完成什么
真正有价值的问题是:在AppLovin赚到下一美元之前,广告主必须先完成什么。
在6月22日的开放公告中,福鲁吉宣布取消推荐准入要求,并称平台正接近实现一键创建广告活动。AppLovin Ads依托Axon推荐系统,把广告主与手机游戏中的潜在买家连接起来。平台自此向所有人开放。5
但到了8月,福鲁吉表示,系统仍无法开箱即用地、稳定地向广告主交付高质量的30秒至60秒视频。小型商家在有限的测试预算下,也难以达到回报目标。管理层因此把重心放在中型品牌上。这些是公司方面对瓶颈的描述,并非独立测算出的失败率。4
当前的上线清单把剩余功课列得清清楚楚:验证购买追踪,投入足够预算、带来足量转化供系统学习,并持续测试改编后的视频广告。在算法证明自身价值之前,网店必须先拿出资金、素材和精力。6
这是扩张层面的约束。管理层将二季度增长疲软主要归因于游戏模型改进的时点。若把整体放缓一概归为电商业务的失败,就超出了证据能支撑的范围。4
采用AI的成本,还包括客户仍要完成的功课。
看多阵营手握实据
看多的理由确实有据可查。Triple Whale在9月3日发布的报告中考察了755家在AppLovin上投放广告的店铺,发现在符合条件的店铺中,61%的店铺在AppLovin上的归因回报高于用于对比的其他渠道;在七组地域留出测试(geographic holdout test)中,有五组测得统计上显著的正向营收效应。9
这仍是单一来源的证据,出自一家与AppLovin有合作的测量服务商。它能佐证广告活动确能产生效果,却没有回答:有多少小企业能够顺利起步。10
福鲁吉下一个有用的记分牌,应当把注册、广告活动上线和持续盈利投放串联起来。值得观察的是:创意工具改进之后,小型广告主能否较少依赖外部帮助,走完这条路径。
还要看,有多少新广告主能保持盈利性投放。
How this brief was made
01Gathered & sourced307 channels · 1,871 articles▾
Agents swept 307 channels and ingested 1,871 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated10 claims · 12 data feeds▾
Every one of 10 load-bearing claims was checked against primary sources, with 12 live data feeds reconciling the figures and charts.
- 1AppLovin Q2 2026 financial results, Aug 5 2026 (company-claimed and unaudited primary disclosure: revenue of $1,923,686 thousand and Q3 guidance of $2,055M to $2,085M. The SEC copy is the same source, not a second one).
- 2AppLovin Q1 2026 financial results, May 6 2026 (company-claimed and unaudited: revenue of $1,842,449 thousand, used as a chart input).
- 3AppLovin Q4 2025 earnings exhibit, Feb 11 2026 (company-claimed and unaudited: revenue of $1,657,944 thousand, the denominator for Q1 sequential growth. Labelled unaudited, and distinct from the later audited annual statements).
- 4AppLovin Q2 2026 earnings call, Aug 5 2026 (management's own statements, read in a third-party transcription: the video-generation limitation, the focus on midsized brands, and the gaming-model explanation for slower growth. Audio was not independently transcribed).
- 5AppLovin's announcement opening the platform, Jun 22 2026 (company-claimed: the referral requirement removed and one-click creation described as an aspiration, not a completed capability. AppLovin Ads is the platform; Axon is the recommendation system).
- 6AppLovin launch checklist, accessed Sep 14 2026 (company product instructions establishing the remaining customer work: tracking, learning budget, creative adaptation and repeat testing. The video duration is guidance rather than an eligibility rule, and the documentation discloses no failure or churn rate).
- 7Morgan Stanley price-target cut to $450 from $650, Overweight retained, Sep 14 2026 (the action is corroborated across ratings trackers; the client note was not accessed, and an analyst's conclusion is not an operating result. It is a $200 reduction, not a $200 target).
- 8Evercore ISI price-target cut, reported Sep 1 2026 (single-source account of the firm describing its own historical ecommerce-spend estimates as too high; the underlying note was not accessed, and analyst estimates are not company disclosures).
- 9Triple Whale report on AppLovin advertisers, updated Sep 3 2026 (single-source provider research over a selected cohort of 755 shops: 61% of qualifying shops showed higher attributed ROAS, and five of seven geographic tests were positive and significant. Shared-channel attribution can double count credit, the tests do not all measure the same revenue, and the study does not measure signup failures).
- 10AdExchanger on AppLovin's ecommerce and consumer expansion, Aug 5 2026 (reporting of company statements; it confirms the Triple Whale relationship described on the call rather than independently verifying operating claims).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.