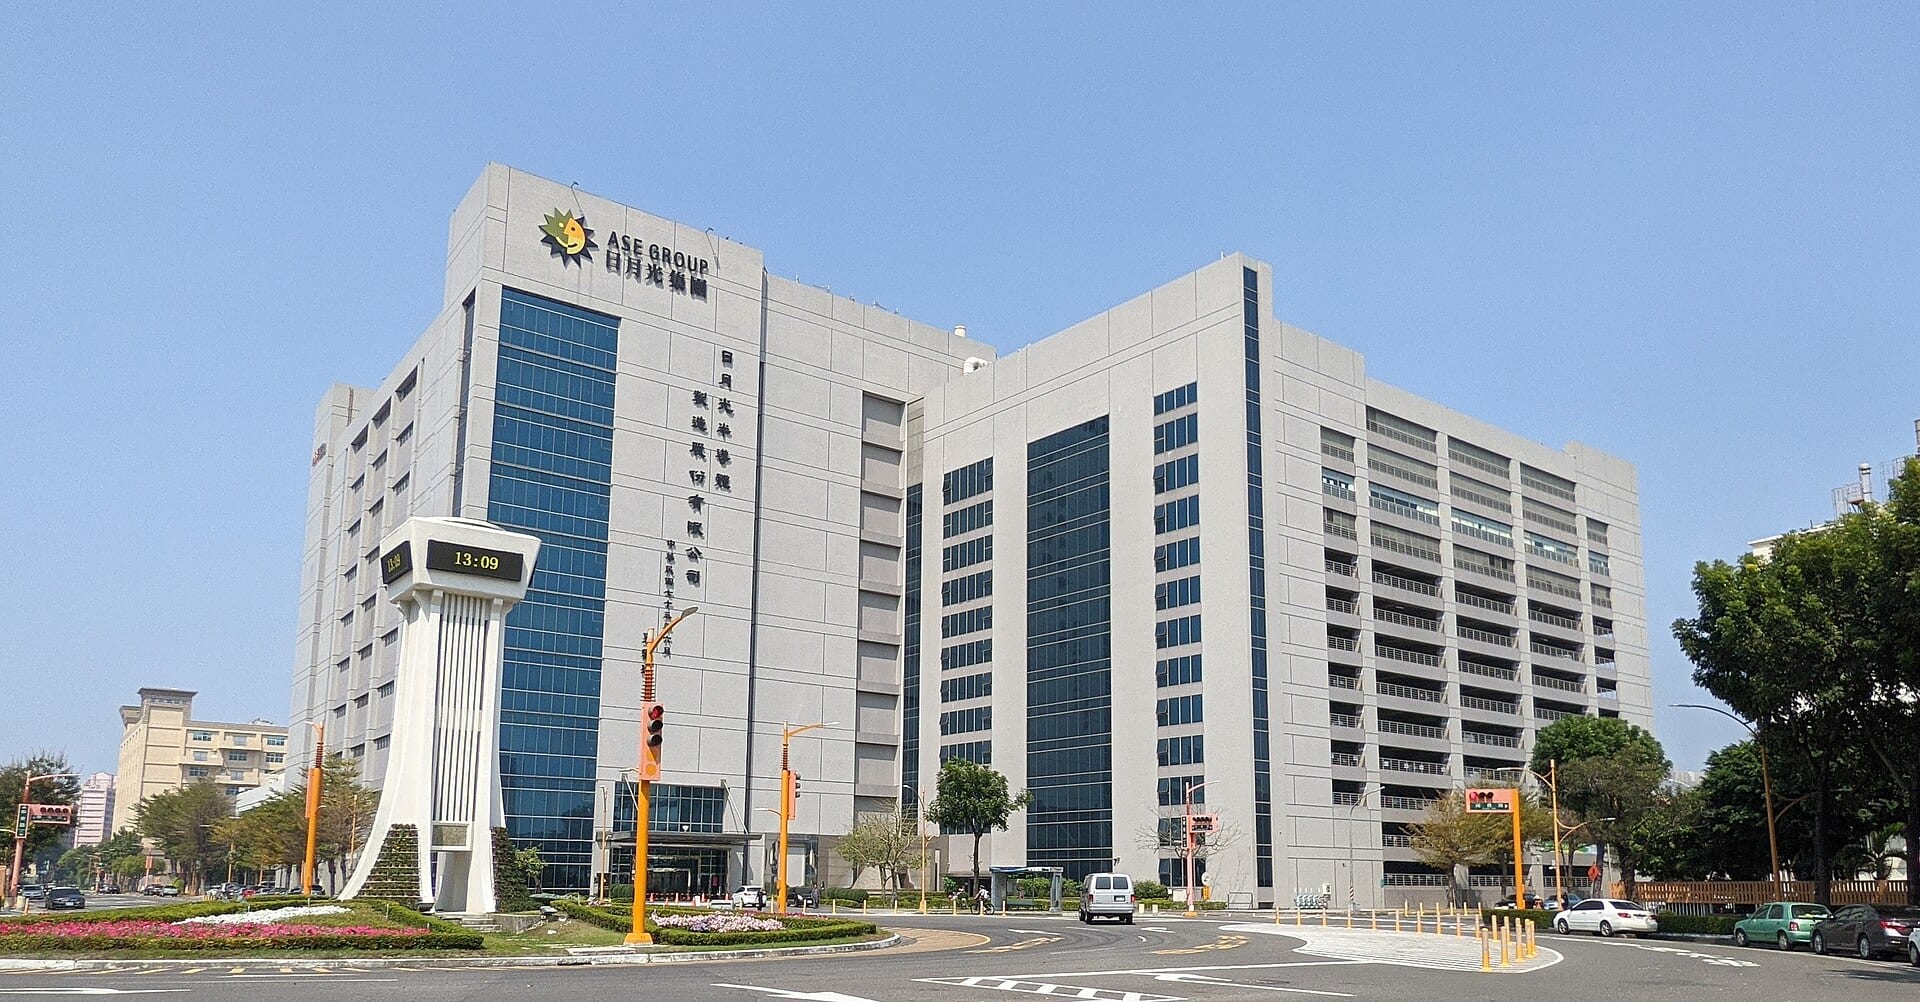
ASE spent NT$10 billion in three weeks building the packaging slots AMD cannot get
ASE units disclosed three more Taiwan contracts on October 7, the latest burst in a NT$10.2 billion three-week build behind a plan to double advanced-packaging revenue to US$7 billion in 2027. In Taipei, AMD's Lisa Su is asking rivals to share the capacity ASE is buying, and 18 analysts still price the stock below where it trades.
 Vincent Jiang · 3 min read
ASE Technology's units put three more contracts on the tape on the morning of October 7, 2026: a NT$1.4 billion facility engineering deal with Acter, a machinery purchase from Tazmo, and facility engineering contracts with United Purification Technology 123. None of the three names a customer. All three buy concrete, clean rooms or tools.
A three-week shopping list, NT$8.9 billion of it in eight days
Since September 17 the same tape has carried machinery worth over NT$1 billion, a US$48 million Teradyne equipment buy, NT$1.33 billion more of machinery, a NT$2.04 billion Acter contract, then NT$2.36 billion of facility engineering, NT$1.13 billion of machinery, a NT$1.10 billion facility deal and NT$885 million of property 1. The seven priced items alone total NT$10.2 billion, and NT$8.9 billion of that landed between September 30 and October 7 1.
ASE's priced Taiwan deals since September 22 total NT$10.2 billion, NT$8.9 billion of it in eight days
Data
| Value | |
|---|---|
| Facility contracts, 1 Oct | NT$2.36bn |
| Acter deal, 30 Sep | NT$2.04bn |
| Acter deal, 7 Oct | NT$1.4bn |
| Machinery, 22 Sep | NT$1.33bn |
| Machinery, 1 Oct | NT$1.13bn |
| Facility deal, 1 Oct | NT$1.1bn |
| Property, 2 Oct | NT$0.89bn |
The customer is standing in Taipei
The build has a buyer attached. AMD chief Lisa Su said in Taipei that demand is "even higher than our supply," promised a substantial supply increase for 2027, and now plans capacity three to five years ahead 45. Her pledge of more than US$10 billion for Taiwan covers packaging capacity through ASE and SPIL, and she says the figure will grow 46.
AMD is also developing its Elevated Fanout Bridge packaging with ASE and SPIL, and every Helios rack carries 72 of its MI455X GPUs 7. The wires reported Su asking rivals to share capacity 9, which leaves AMD on both sides of ASE's order book at once: co-developer of the packaging process, and the customer competing for the same slots.
Sold-out capacity, a record August
August was ASE's first month above NT$80 billion of revenue, and the Taipei trade press says packaging capacity is staying sold out 8. TSMC's chief had already warned that tight packaging limits how fast customers can grow 7. The filings show who is paying to add it.
Capex doubles while the price outruns the target
The spend is the plan. Management guides 2026 capital expenditure to US$10.5 billion, against US$5.5 billion in 2025, behind leading-edge advanced packaging revenue above US$3.5 billion this year and at least US$7 billion in 2027 10. The filings show the ramp running: US$2.5 billion in the second quarter alone, US$3.9 billion in the half 11.
The return is printing too. August assembly, testing and materials revenue rose 41.4% year on year to US$1.594 billion, ahead of the consolidated 34.6% gain, on a 27.3% ATM gross margin last quarter 1213.
The street's target sits below the price
Yet 18 analysts average a 727.53 TWD target, 2.21% below the 744.00 close, and the mean consensus is still Buy 1. The New York listing has traded across a 52-week range of US$11.07 to 47.93 and last changed hands at US$46.98 12.
Quarterly capex hit $2.5B in Q2 26, and the $10.5B full-year guide implies a faster second half
Data
| Capex | |
|---|---|
| Q1 '24 | $0.39B |
| Q2 '24 | $0.45B |
| Q3 '24 | $0.63B |
| Q4 '24 | $0.98B |
| Q1 '25 | $1.09B |
| Q2 '25 | $1.48B |
| Q3 '25 | $1.47B |
| Q4 '25 | $1.21B |
| Q1 '26 | $1.38B |
| Q2 '26 | $2.51B |
October 29 reads the margin
Third-quarter results land before the open on October 29, guided to revenue up 21% to 22% on the quarter and a gross margin of 20.5% to 21.5% 1210. Two lines settle the argument: whether ATM keeps outgrowing the consolidated company, and whether that margin survives a year in which capex doubles. Until then the concrete is bought, and not yet paid back.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.