Atlassian guides the year to 13.75% after a 24% quarter as Farquhar sells and Cannon-Brookes buys $250 million
The 24% September quarter and the 13.75% full-year guide describe different businesses: one migrates old customers off Data Center, the other sells more seats and Collections into existing accounts. Scott Farquhar is selling shares while Mike Cannon-Brookes buys, and the December-quarter report decides which business owns the stock.
 Richard Tangthree-minute read
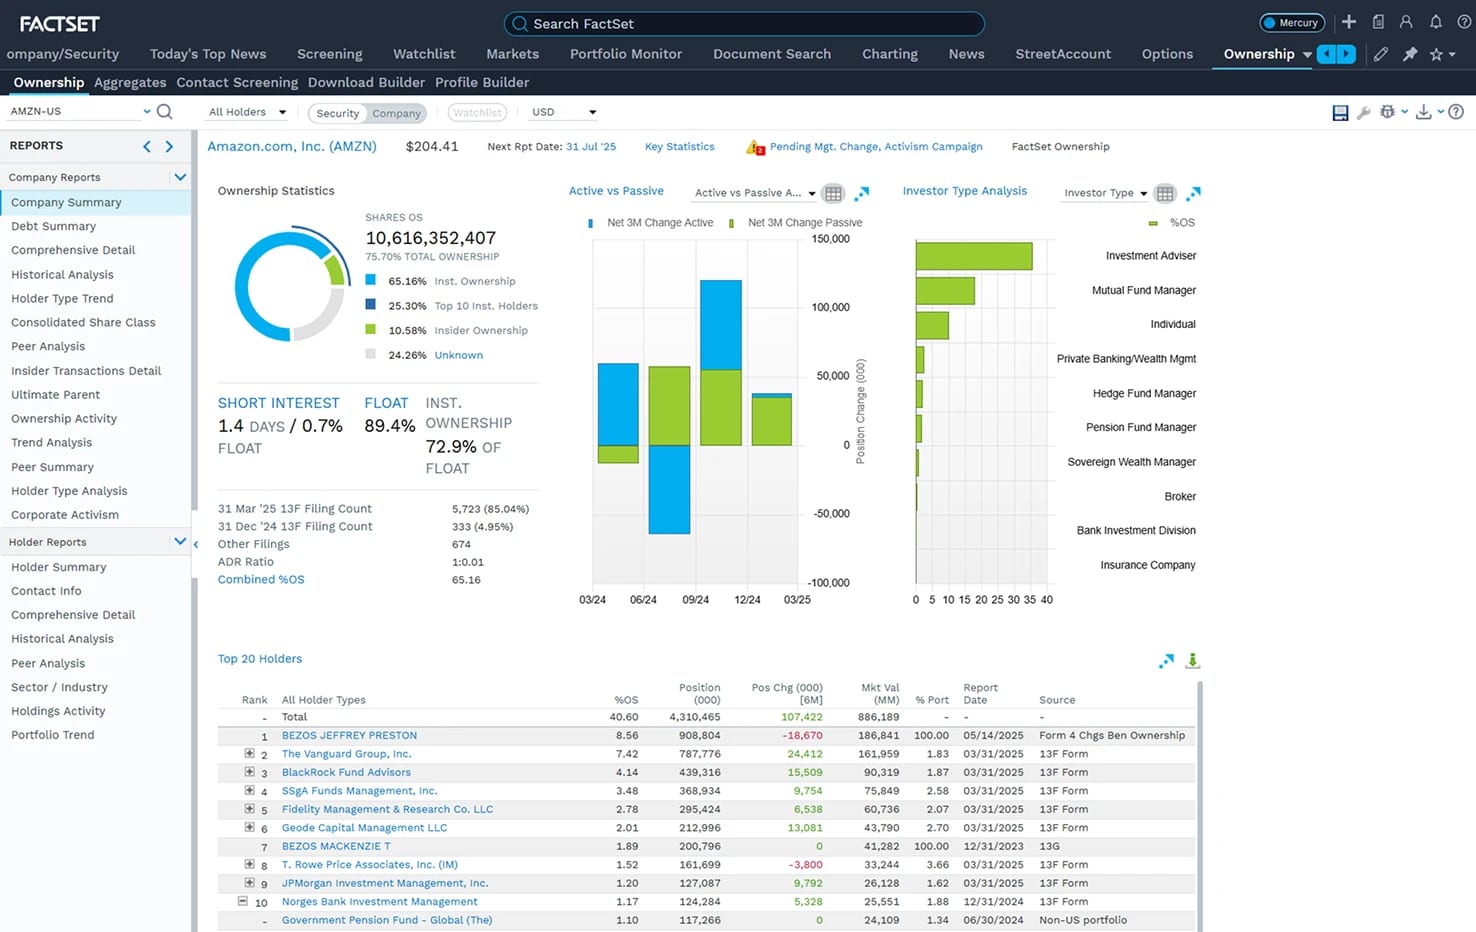
Atlassian−4.06% — Atlassian, down 4.06 percent as of its last quote printed a 24% quarter and then guided the year to 13.75% 323. That gap, not the beat, is what the stock is now pricing: the shares closed at $153.68 the day after the report 3, and the following week went to the founders trading in opposite directions and to Citi+0.56% — Citi, up 0.56 percent as of its last quote trimming its target rather than its rating 23.
The 31% cloud quarter was carried by accounts Atlassian already had: more seats, upgrades to bundled Collections, and migrations off the self-hosted Data Center product 1. Those are two different businesses wearing one headline. The migration business shrinks by design; the expansion business is the one that has to grow fast enough to cover it.
The expansion engine is real but must outrun the shrinking migration pool
The expansion evidence is genuine: Teamwork Collection customers rose sevenfold past 3,000, contracted revenue not yet recognized grew 44% to $4.7 billion, and Atlassian sits in 85% of the Fortune 500, which the CFO said is only about 10% of revenue, with Infosys+1.37% — Infosys, up 1.37 percent today, SAP−1.51% — SAP, down 1.51 percent as of its last quote, Workday−0.69% — Workday, down 0.69 percent as of its last quote and Westpac all expanding 1.
But the CFO also said Data Center migrations added mid-to-high single digits to cloud growth from a pool that shrinks as it completes, and that subscription ARR, $6.81 billion this quarter, will slow over the next three quarters 1. Strip the migration lift out and cloud still grew in the low-to-mid twenties by Business of GTM's estimate 1. That is the real question for the SaaSpocalypse camp: whether AI compresses seats faster than bundling Collections inside existing accounts offsets it.
Atlassian's total growth swung from 14% to 32% and back to 24% in two years
Data
| Revenue growth, YoY | |
|---|---|
| Q4 '23 | 21.5% |
| Q1 '24 | 29.9% |
| Q2 '24 | 20.5% |
| Q3 '24 | 21.5% |
| Q4 '24 | 21.4% |
| Q1 '25 | 14.1% |
| Q2 '25 | 22.3% |
| Q3 '25 | 20.6% |
| Q4 '25 | 23.3% |
| Q1 '26 | 31.7% |
| Q2 '26 | 27.6% |
| Q3 '26 | 23.7% |
The founders voted with their filings
Scott Farquhar, Atlassian's former co-CEO, filed to sell 3,393,500 class-A shares, spread out to December 2027; Mike Cannon-Brookes, the other co-founder and current CEO, is buying about $250 million of stock, per SEC filings 2. The SaaSpocalypse sell-off has hit Atlassian, Adobe−0.49% — Adobe, down 0.49 percent today, Xero and WiseTech 2. A founder selling for diversification while his partner buys is noise next to the numbers, but it is the week's only other news, and it cuts both ways.
What the December-quarter report has to show
Cloud needs to land near the 27% Q2 guide, and ARR needs to decelerate no faster than Atlassian promised when the report arrives in late January 1. Citi kept its Buy and cut its target to $220 from $245 against that $153.68 close; the 30-day target range runs $190 to $240 3. The analysts are underwriting the expansion business. The December print is where they find out if they were right.
Analyst targets run $190 to $240 against a $153.68 close
Every recent target sits far above the price the guide produced
Data
| Value | |
|---|---|
| Oppenheimer | $240 |
| Citigroup | $220 |
| Barclays | $210 |
| Truist | $200 |
| Wells Fargo | $200 |
| Jefferies | $190 |
| Nov 6 close | $153.68 |
Sources: 1. Business of GTM, Atlassian's 31% Cloud Growth Leaned on Accounts It Already Had, November 6, 2026 — https://businessofgtm.com/articles/atlassian-cloud-growth-existing-accounts 2. The Nightly, Atlassian co-founder Scott Farquhar to sell nearly 3.4 million shares in technology company, November 10, 2026 — https://thenightly.com.au/business/atlassian-co-founder-scott-farquhar-to-sell-nearly-34-million-shares-in-technology-company-c-23142842 3. TradingView, Citigroup maintains Atlassian at Buy, lowers price target to $220 from $245, November 10, 2026 — https://www.tradingview.com/news/tradingview:86601b8549510:0-citigroup-maintains-atlassian-at-buy-lowers-price-target-to-220-from-245/
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.