博通以290亿美元承诺为其AI繁荣背书
陈福阳在CNBC上捍卫博通的AI营收目标,对放缓争论毫不退缩。股东还持有一项更安静的承诺:一笔高达290亿美元的客户租赁兜底协议,仅在需要时启用。
 Vincent Jiang · 6 min read
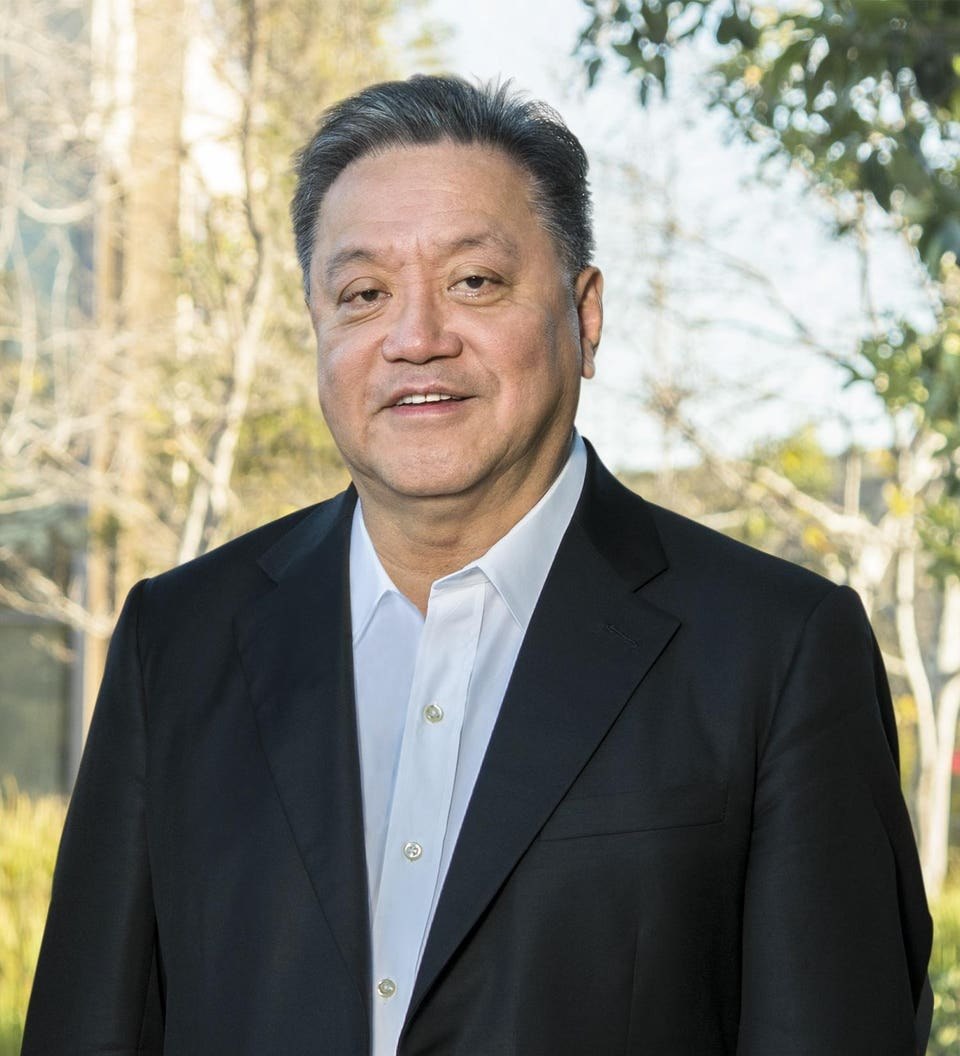
陈福阳9月14日登上CNBC,拒绝降低其AI营收目标。1
这位博通首席执行官坚持其2027财年1150亿美元、2028财年2300亿美元的营收目标,尽管市场对前沿模型开发放缓存有争论。这些是管理层预测。股东还持有一项更令人不安的承诺:一项最大潜在敞口约290亿美元的客户租赁兜底协议。1,2
其间的复杂性很直接。博通通过帮助客户降低AI成本来赚钱,同时也为他们获取设备提供融资。因此,股东既需要评估芯片的商业优势,也需要评估与之相伴的财务义务。
AI主导营收增长
博通9月2日公布的业绩显示,季度营收为295.91亿美元,其中167亿美元来自AI半导体业务(包括定制加速器和网络芯片)。上年同期的可比数据分别为159.52亿美元和52亿美元。经计算,AI贡献了约84%的营收增长额。4,5
Data
| Value | |
|---|---|
| 2025财年第三季度 | $5.2B |
| 2026财年第三季度 | $16.7B |
为买家提供融资,意味着信用判断已成为产品的一部分。
博通报告称,在支出5.32亿美元资本开支后,公司自由现金流为136.65亿美元,约占销售额的46%。当前的现金生成能力强劲;但新增融资安排的终身盈利能力尚未得到验证。4
这种区别正是投资的关键问题。一家高速增长的供应商可能在产生出色当期现金流的同时,承担着成本可能随后才显现的义务。相关的检验是:增量利润是否足以补偿股东承担这些义务。
护城河是工作关系
OpenAI的Jalapeño芯片解释了博通的重要性。在6月24日的公告中,OpenAI描述了其围绕模型和推理系统设计架构,由博通提供硅片实现和网络支持。客户了解工作负载,博通则帮助将这种知识转化为可生产硬件。6
这种关系难以替代,因为其中的工程决策相互关联。内存移动、软件、网络和芯片设计必须协同工作。采用一个不兼容的组件如果会延误整个系统集成,便是不可取的。推论是:博通最强大的保护源于其在反复开发周期和成功部署中的角色,而非任何单一组件。
OpenAI 8月25日的测试显示,其在三款公开模型上实现了更优的每瓦吞吐量。然而,生产认证和软件准备工作仍在继续,初步部署计划在年底前完成。可工作的芯片是有意义的证据;大规模盈利运营仍是另一个里程碑。7
客户也保留选择余地。迈威尔科技(Marvell)8月19日的文件描述了与谷歌扩大合作关系,涵盖围绕TPU生态系统的定制芯片,包括推理加速器和控制器。这并未表明博通失去了现有设计。但它确实表明,客户可以在扩展定制计算的同时培育额外的供应商。8
融资将客户风险带回博通
6月,阿波罗宣布为博通的AI XPV平台提供350亿美元的初步融资方案,参与方包括黑石和多家银行。该融资支持Anthropic超过1千兆瓦的算力,通过多年度提款计划实现。这是融资能力,而非350亿美元的博通营收。9
博通6月的文件披露了对五年期客户租赁的支持。敞口随着机架部署而上升,随着租赁付款到账而下降。9月的文件明确规定,在所有机架部署后,最大潜在负债约为290亿美元(未折现)。截至8月2日,该兜底承诺的公允价值微不足道,且未发生任何支付。3,2
Data
| Value | |
|---|---|
| 最大兜底负债 | $29B |
| 过去4季度自由现金流 | $39.4B |
违约后,敞口取决于未偿还受保租赁金额的85%与机架销售收入之间的差额。其他补救措施包括接手租赁和有条件的固定价格转售。最大敞口既非当前债务,也非预期损失。2
经济层面的担忧在于,偿付压力和设备价值下降可能同时出现。如果AI客户的经济性恶化,其他买家也可能对同一代硬件要求更低的价格。这将在最需要回收资金的时刻削弱回收来源。这是一种风险机制,并非违约即将发生的证据。
谷歌4月22日的公告使这种张力具体化。其声称TPU 8i的推理性价比比Ironwood高出80%。更快的改进可能刺激需求,同时也会挤压旧设备租赁的经济性。谷歌的声明并未确立转售价格,也未证明旧芯片变得无法使用。10
最强看多逻辑在训练放缓中依然成立
陈福阳9月14日的辩护聚焦于推理,即使用已训练好的模型完成工作。更强大的前沿模型发布放缓,不会自动阻止企业部署现有模型提供服务。即使没有同样快速的训练竞赛,更多的使用也可能需要更多的算力。1
这一论点背后有商业证据支持。Anthropic 5月28日的融资公告称,其年化营收运营率(run rate)已在当月早些时候超过470亿美元,并披露了650亿美元的一轮融资。这些都是公司的说法,且运营率既非已实现的年营收,也非利润。尽管如此,它们显示了一家拥有可观销售额并能获得资本的客户。11
亚马逊在4月也分别表示,已有超过10万客户在AWS上运行Claude,并宣布为Anthropic增加Trainium算力。因此,对有用AI的需求可以是真实的,即使支出分散在相互竞争的硬件平台上。12
融资支持正成为这场竞争的一部分。AMD在7月的协议将计划中的Anthropic部署与高达50亿美元的未来股权投资挂钩。英伟达与迈威尔科技在3月的合作也旨在定制芯片系统中占据一席之地。博通在工程、商业条款和资本支持等多个维度竞争客户的基础设施预算。13,14
看多逻辑是可信的:融资消除了瓶颈,部署量增长,客户从扩张的业务中偿还。但这并不能消除为博通所保留的风险定价的需要。
每股344.72美元股价已要求什么
AVGO股价在9月14日收于344.72美元。使用8月28日约47.74亿股流通股计算,意味着股权价值为1.646万亿美元。股份数基准日较早,使其成为一个估值快照,而非精确的当前市值。15,2
过去四个季度的自由现金流为394.03亿美元,使得该估值约为实际现金生成量的42倍。16,2
将最新季度的自由现金流年化为546.6亿美元。以此速度计算,估算股权价值约为其30倍,相当于3.3%的现金流收益率。这既非过去年化现金流,也非预测:它假设未来四个季度与最新业绩持平。它也将股权激励和任何未来兜底支付排除在业主成本调整之外。4
一个简单的敏感性分析说明了为何仅有增长是不够的。如果年化现金流从该水平增长25%,但投资者只愿支付25倍现金流,那么在股息前且假设股份数不变的情况下,股权价值仅会增长约4%。这些是示例性假设,而非目标股价。更低的估值倍数可以吸收大部分运营改善。
在将营收目标视为股东回报之前,需要跨越的门槛应是每股持续现金流生成能力。这家企业已赢得信誉;但估值仍要求持续的执行力。
陈福阳接下来需要证明什么
接下来的披露应连接芯片出货量、客户部署、现金收款和保留的融资敞口:Jalapeño芯片的量产进展、随着机架部署后实际未偿还的兜底金额,以及未来交易是否需要类似或更大的支持。
每股现金应与营收受到同等关注。博通可以实现雄心勃勃的销售目标,但如果融资敞口增长快于补偿它的利润,股东得到的可能是不那么有吸引力的交易。
陈福阳已捍卫了需求预测。下一个考验是,博通必须承担多少风险才能实现它。
How this brief was made
01Gathered & sourced231 channels · 2,221 articles▾
Agents swept 231 channels and ingested 2,221 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated16 claims · 26 data feeds▾
Every one of 16 load-bearing claims was checked against primary sources, with 26 live data feeds reconciling the figures and charts.
- 1CNBC interview with Hock Tan, Sep 14 2026 (Tan defends the $115B fiscal 2027 and $230B fiscal 2028 AI revenue targets against the frontier-slowdown debate; a reproduction exists elsewhere and counts as the same report, not a second source).
- 2Broadcom Form 10-Q for the quarter ended Aug 2, filed Sep 10 2026 (primary issuer filing, unaudited: the roughly $29B maximum backstop exposure, the 85%-of-outstanding-lease-amount default mechanic, approximately 4.774 billion shares outstanding at Aug 28, and nine months of cash flow).
- 3Broadcom Form 10-Q for the quarter ended May 3, filed around Jun 9 2026 (primary issuer filing: the original disclosure of five-year customer-lease backstop support, before the September update quantified the maximum exposure).
- 4Broadcom third-quarter fiscal 2026 results, Sep 2 2026 (company-reported, unaudited: $29.591B revenue including $16.7B AI semiconductor revenue, and $13.665B free cash flow after $532M of capital spending).
- 5Broadcom third-quarter fiscal 2025 results, Sep 4 2025 (company-reported, unaudited prior-year comparison: $15.952B revenue including $5.2B AI semiconductor revenue).
- 6OpenAI's Jalapeño chip announcement, Jun 24 2026 (primary customer and partner account of the engineering split: OpenAI on architecture and serving systems, Broadcom on silicon implementation and networking).
- 7OpenAI's Jalapeño first results, Aug 25 2026 (company-tested throughput-per-watt results across three public models; production qualification and software preparation remained prospective, with initial deployment planned by year-end).
- 8Marvell Form 8-K, Aug 19 2026 (primary competitor filing describing an expanded Google partnership across custom chips in the TPU ecosystem, including inference accelerators and controllers).
- 9Apollo's announcement of a $35B capital solution for Broadcom's AI XPV platform, Jun 9 2026 (primary financing participant account, alongside Blackstone and banks, supporting more than one gigawatt of Anthropic capacity on a multiyear draw schedule).
- 10Google's TPU 8t and TPU 8i technical explanation, Apr 22 2026 (vendor performance claim of up to 80% better inference performance per dollar than Ironwood; a hardware-economics claim, not an independent resale valuation).
- 11Anthropic's Series H financing announcement, May 28 2026 (company-reported: annualized revenue run rate exceeding $47B earlier that month and a $65B funding round; run rate is neither realized annual revenue nor profit).
- 12Amazon's announcement of additional Anthropic investment and Trainium capacity, Apr 20 2026 (primary cloud-provider account: more than 100,000 customers running Claude on AWS).
- 13AMD's strategic partnership announcement with Anthropic, Jul 22 2026 (primary competitor account: planned deployment of up to 2 gigawatts of AMD Instinct MI450-series GPUs, paired with up to $5B of future equity investment).
- 14Nvidia's announcement of Marvell joining the NVLink Fusion ecosystem, Mar 31 2026 (primary competitor account of a custom-chip systems partnership; not a measured share gain against Broadcom).
- 15Stock Analysis historical prices for AVGO, Sep 14 2026 close (market data: $344.72, cross-checked against Google Finance's live quote).
- 16Broadcom fourth-quarter and fiscal-year 2025 results, Dec 11 2025 (company-reported, unaudited prior fourth-quarter free cash flow, combined with the September 10-Q's latest nine months for the trailing four-quarter calculation).
03Reviewed & edited1 human editor▾
One editor read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.


