Commvault's resilience premium now rides on its SaaS conversion
Commvault's Q2 FY27 beat this morning: subscription ARR of $1.1 billion, retention at 113% and a raised full-year guide. The filing's own tables show the price of that story: perpetual licenses down 40%, leaving SaaS to carry a stock trading near 108 times trailing earnings with no analyst-implied upside left.
 Richard Tang · 2 min read
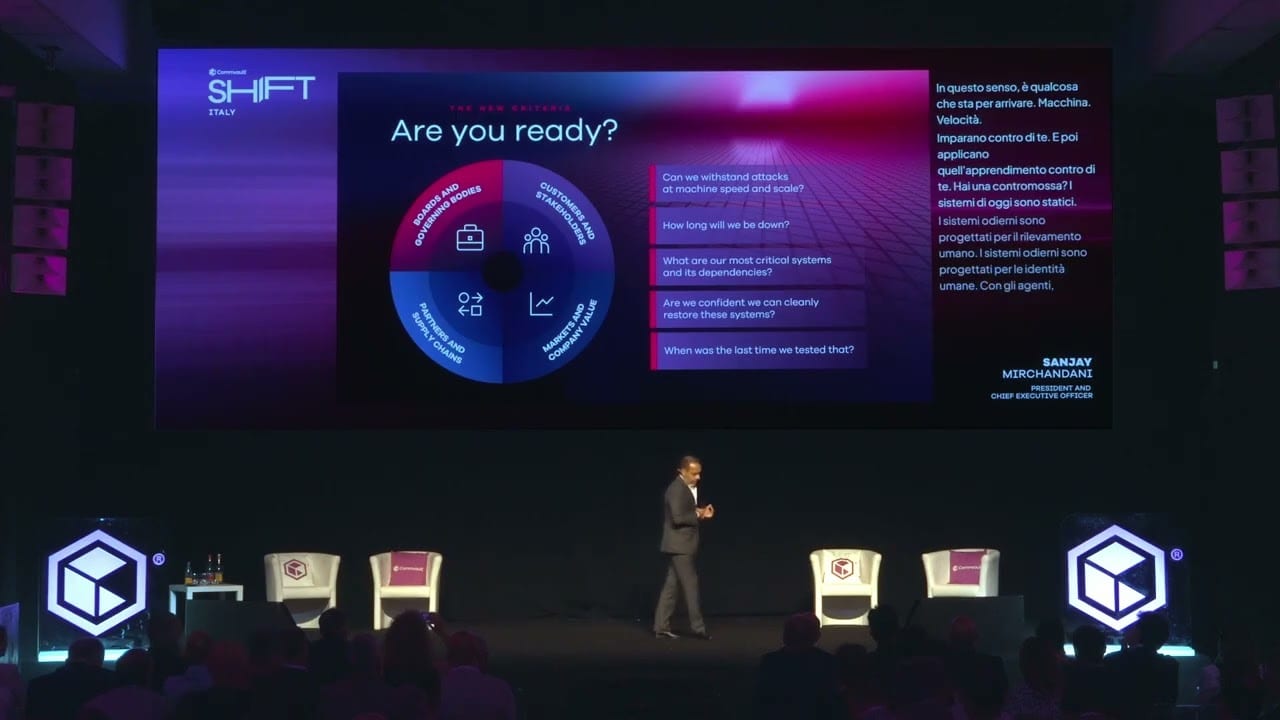
Commvault+1.90% — Commvault, up 1.90 percent today beat this morning, and the print confirms what the AI chain has been saying all along: when models accelerate both what enterprises build and what can go wrong, someone has to guarantee the data comes back clean, and enterprises pay up for that. Q2 subscription revenue rose 21% to $269 million, subscription ARR hit $1,104 million, net dollar retention held at 113%, and the full-year ARR guide moved to a $1,210 million midpoint on a real operational raise, not just currency 124. CEO Sanjay Mirchandani framed it plainly: AI is accelerating innovation and risk, and resilience is the business imperative 1.
But the filing's own tables show the transition under the headline.
License decay is the fixed headwind SaaS must outrun
SaaS revenue grew 33% to $106 million, while perpetual license revenue fell 40% to $7.2 million and perpetual support fell 23% 12. That is the whole story of this business in two lines: customers are moving from owned licenses to cloud-hosted subscriptions, and Commvault is winning that move. The open question is pace, because license decay is a fixed headwind while SaaS compounding must keep accelerating just to hold the overall growth rate.
SaaS keeps compounding while perpetual license revenue decays
- SaaS revenue
- Perpetual license revenue
Data
| SaaS revenue | Perpetual license revenue | |
|---|---|---|
| Q2'26 | 80M | 12.1M |
| Q3'26 | 87.4M | 13.7M |
| Q4'26 | 93.1M | 10.1M |
| Q1'27 | 100.6M | 8.7M |
| Q2'27 | 106.2M | 7.2M |
Geography shows the same lag: International revenue grew 9% against 15% in the Americas, meaning the SaaS conversion, and the resilience spend attached to it, is running ahead in the US market and has yet to arrive elsewhere 12.
The premium is already priced
Analysts lifted targets into the print, Jefferies to $170 on a hold, Cantor to $171 neutral, yet consensus sits at $163.19 against a Monday open of $169, leaving essentially no implied upside 3. At roughly 108 times trailing earnings, buyers are paying a resilience premium; the cash engine is real, about $259 million of trailing free cash flow 5.
For investors, the check is simple: watch whether net-new ARR keeps rising and SaaS holds its growth rate. If it does, the decay lines are noise. Commvault sits in the right link of the AI chain, recovery for the AI era, and is executing the conversion.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.