Fermi reports a $200 million hyperscaler down payment and no signed leases
A $200 million hyperscaler prepayment for 600 MW at Project Matador landed in the same filing as the terminated TensorWave lease, leaving Fermi with customer money but no signed tenant, and $315.5 million of cash against a buildout it funds quarter by quarter.
 Richard Tangtwo-minute read
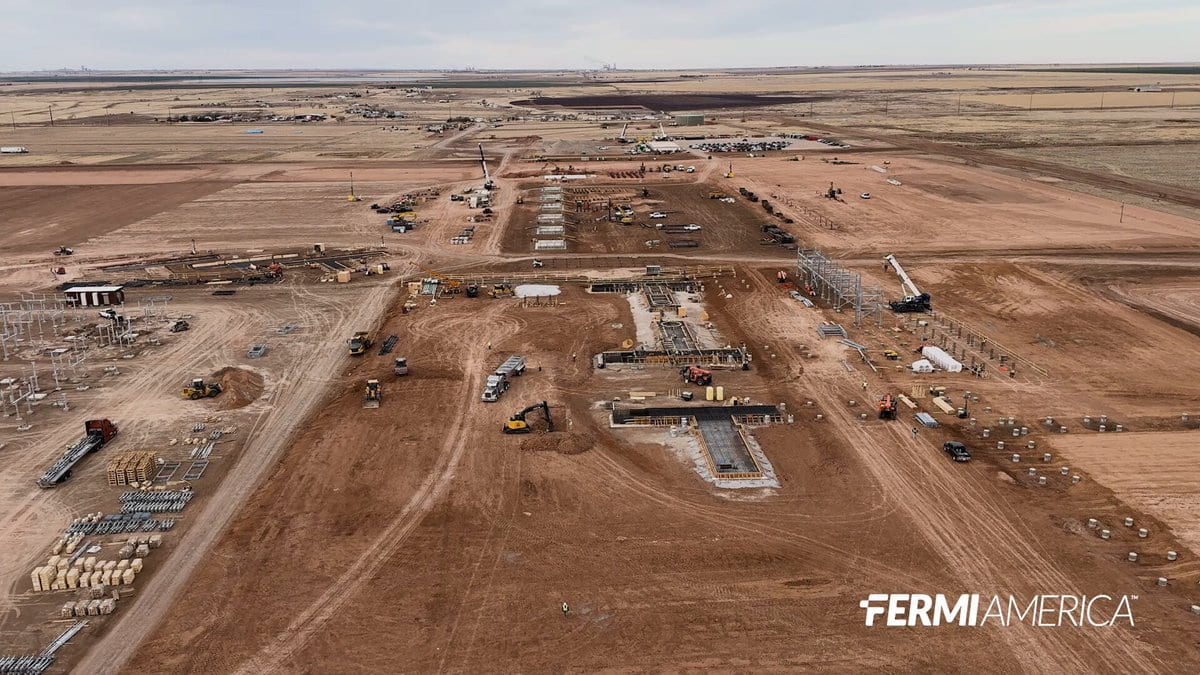
Fermi's quarter+15.47% — Fermi's quarter, up 15.47 percent today turned on two disclosures inside one filing: an unnamed investment-grade hyperscaler is putting money into Project Matador before signing anything, and the company's only signed tenant is gone. The Q3 report filed today shows a $200 million prepayment and a $15 million early-construction agreement for 600 megawatts that has no lease behind it yet, alongside the termination of the TensorWave data center lease signed in August and the AMD+4.95% — AMD, up 4.95 percent today credit support agreement tied to it 1. Fermi ends the quarter with zero signed leases.
The customer is paying before committing
The hyperscaler deal is structured as commitment without obligation: $200 million of upfront funding, $15 million for site preparation, and a $90 million steel-and-materials purchase still only contemplated, all while "the parties continue to work toward a definitive long-term lease" 1. The money matters anyway. Fermi's own framing, that early infrastructure investment attracts customer capital with "little or no dilution," is the strategy working as designed: when equity is expensive, pre-revenue developers fund concrete with customer checks 1. Chief Executive Lee McIntire says the 2.2-gigawatt pipeline, if converted, would fill current capacity 1.
$90 million of the hyperscaler's $305 million is still only contemplated
- Upfront prepayment$200M65.6%
- Early construction agreement$15M4.9%
- Steel and materials, contemplated$90M29.5%
Data
| Part | Hyperscaler commitment | Share |
|---|---|---|
| Upfront prepayment | $200M | 65.6% |
| Early construction agreement | $15M | 4.9% |
| Steel and materials, contemplated | $90M | 29.5% |
The balance sheet is the clock
What the prepayment buys is time. Nine-month capital spending reached $759.5 million against $315.5 million of cash and restricted cash, funded by a $463.0 million net increase in borrowings that took outstanding debt to $958.4 million 1. The quarterly loss of $141.6 million is almost entirely the $142.2 million administrative line, of which $65.8 million is stock compensation and $21.5 million advisory fees settled in shares, so cash burn is far smaller than the headline loss, but the dilution is real either way 1.
Debt rose from $86 million to $576 million as capex ran past cash in four of five quarters
- Capex
- Debt
- Cash
Data
| Capex | Debt | Cash | |
|---|---|---|---|
| Q2 '25 | $42.84M | $85.75M | $40.33M |
| Q3 '25 | $53.45M | $125.44M | $182.99M |
| Q4 '25 | $472.98M | $131.12M | $408.53M |
| Q1 '26 | $441.19M | $465.01M | $243.29M |
| Q2 '26 | $184.97M | $576.39M | $91.73M |
A prepayment is weaker than a signed lease
The TensorWave collapse is the warning inside the good news. That lease, signed in August, missed its October 31 closing deadline with project financing and board approvals still outstanding 3; the termination that followed removes a deal once valued at roughly $6.5 billion and ended AMD's credit support with it 12. A hyperscaler prepayment is a weaker instrument than a signed lease, and Fermi has now learned twice that commitments before closing conditions are not revenue. Until a definitive lease is signed, every quarter prices the next raise, and the down payment is what stands between buildout and dilution.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.