Honeywell's first solo quarter proves the cost cut, not yet the autonomy premium
Honeywell Technologies' first quarter since the break-up was a beat and a raise, built on cost removal rather than demand. Whether the leftover automation company earns a software multiple now turns on one guided number it has to hold.
 Richard Tang · 2 min read
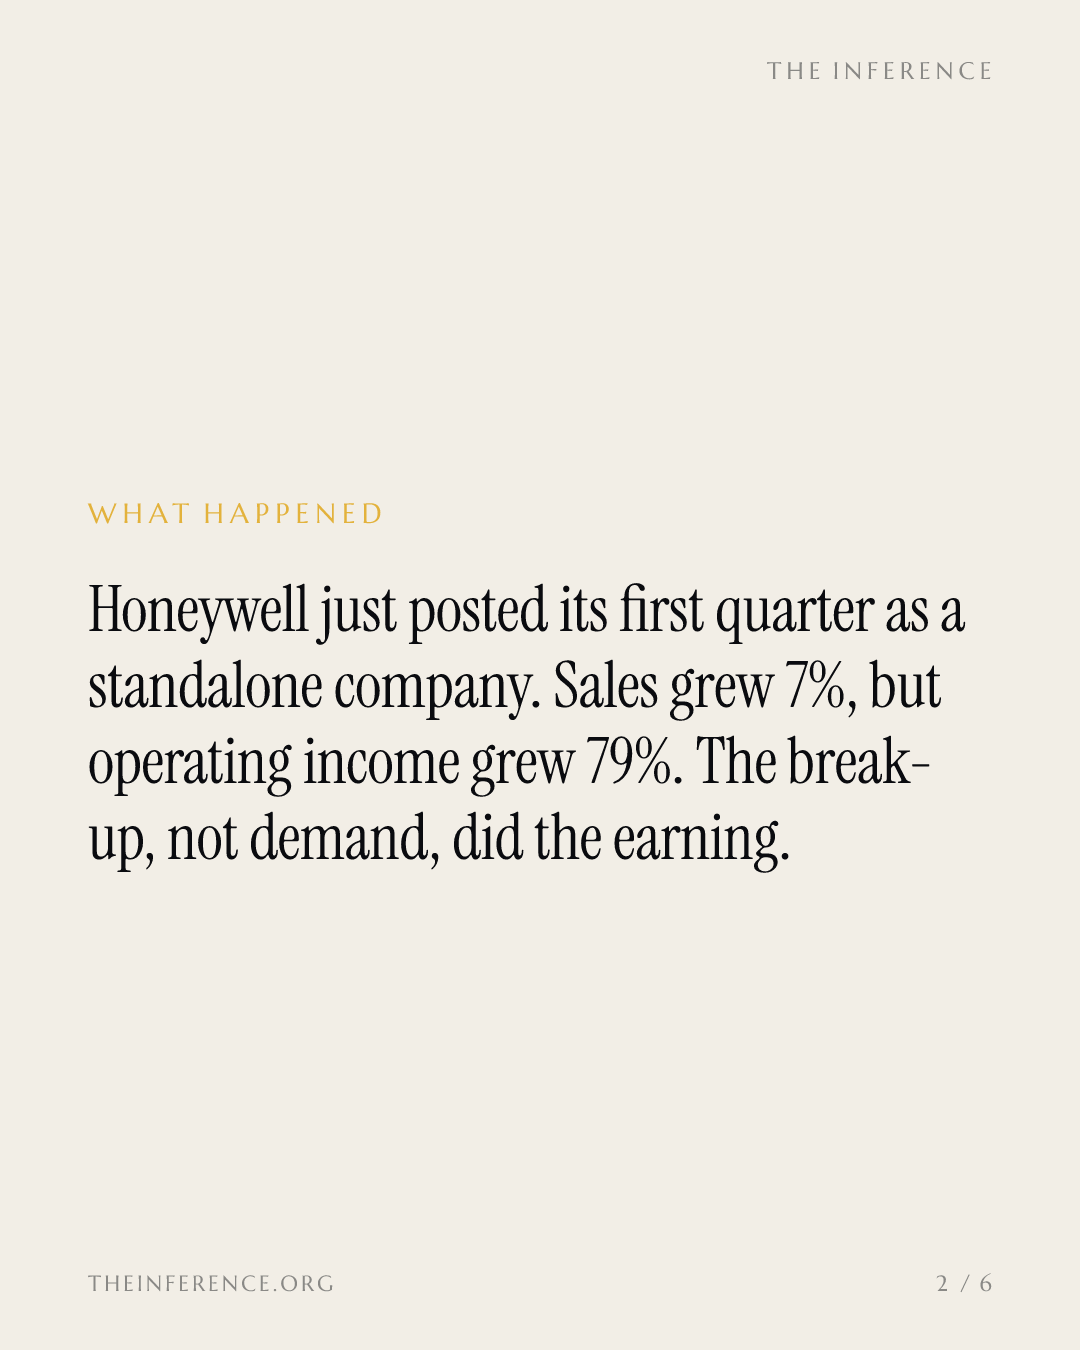
Honeywell Technologies+1.53% — Honeywell Technologies, up 1.53 percent today reported its first quarter as a standalone company this morning, and the gap between two numbers is the story. Organic sales grew 7% 1. Operating income grew 79% 1. Adjusted earnings of $2.27 came in ahead of expectations 2. A quarter does not get that profitable on demand, and the filing says so itself.
The break-up did the earning
The company reporting today is what an activist left behind. Elliott Investment Management pushed the three-way split of the old conglomerate 4; the advanced materials unit left in late 2025, Honeywell Aerospace−0.04% — Honeywell Aerospace, down 0.04 percent today (now Nasdaq: HONA) left in June, and the warehouse automation business went to a buyer in July 4. The multiyear carve-up is now complete 5.
What remained was carrying overhead built for a far larger company, and the 8-K credits the profit jump to eliminating those stranded costs, pricing that outran inflation, and volume leverage 1. The scary cash-flow headline is a one-time Resideo settlement in the prior-year quarter, not deterioration; free cash flow rose 15% 1.
After two years of slipping operating margins 6, the 21.3% segment margin is the first evidence the repair is real 1.
One guide decides the value case
The bull case is a multiple. Honeywell trades at 8.1 times earnings 6. The median S&P 500 company trades at 22.7 times 6. Analysts kept their ratings this month while trimming targets to between $231 and $270 3, which is a wait-and-see stance.
The case dies if the newly raised full-year segment margin guide of about 20.5% slips 17. Backlog near $19 billion and still growing is the demand evidence behind it 1, and the Johnson Matthey catalyst acquisition, closed in July, is a deliberate and visible drag on Process Automation margins while LNG and petrochemical project work keeps growing 16.
The margin reset is real for one quarter; the guide says hold it
- Segment margin
- Estimate
Data
| Segment margin | |
|---|---|
| Q3 2025 | 17.6% |
| Q2 2026 | 19% |
| Q3 2026 | 21.3% |
| FY 2026 guide (estimate) | 20.5% |
The autonomy premium is still unearned
Honeywell's own story is bigger than cost removal. Its control systems already run refineries, hospitals and data centers, and its newest product is Forge Cognition, an agentic AI and simulation platform built with NVIDIA and Dell for facility operations, designed to propose actions and act only with operator approval 8.
That chain runs from installed controls to operating data to software that runs plants; nothing in this quarter's revenue shows the last links yet. The break-up did the earning this quarter, and Kapur's team deserve credit for a margin that had been falling for two years 16.
The re-rating is a second, harder job: hold that margin, then turn decades of installed-base data into software customers run on. The first is nearly mechanical. The second is the whole bet, and it is where the reward belongs.
Get Robotics & Defense by email, free
Robots, self-driving vehicles, drones and AI in defense. In our daily email, every weekday.