Ichor earned 63 cents a share, burned $28.8 million of operating cash, and sold $195 million of stock
Ichor beat earnings and jumped after hours, but its gas-delivery business consumed $29 million of cash in a quarter that produced $21 million of profit. The December report has to show the money arriving.
 Richard Tang · 3 min read
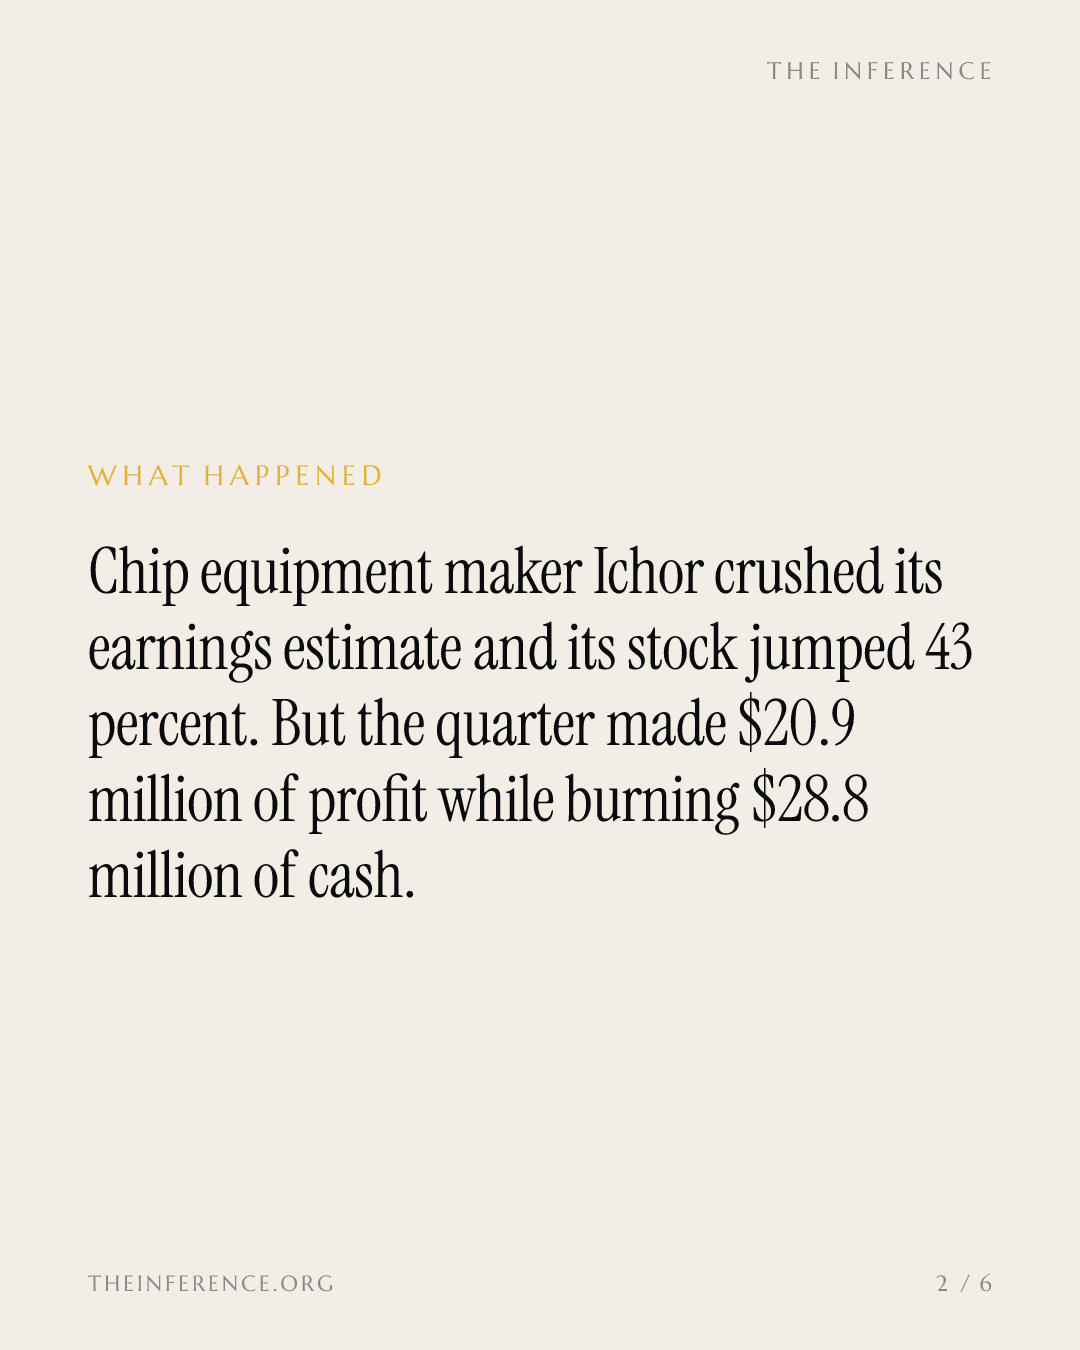
Ichor, which builds the gas and chemical delivery systems inside chipmaking tools, just printed the quarter the AI capex boom promises: earnings of 63 cents a share against roughly 45 expected, a third straight quarter of gross margin expansion, and a 43 percent after-hours surge on November 2 134.
What the surge priced too cheaply sits below the income statement. The quarter produced $20.9 million of net income and consumed $28.8 million of operating cash 1. The margin story is real; the cash conversion has not happened yet, and everything management promised for 2027 depends on it 1.
The boom's bottleneck runs through Ichor's gas panels
The chain from AI to Ichor is short and physical. AI datacenter demand has every segment of semiconductor manufacturing ramping at once, and the tightest constraints sit in high-end etch and deposition, the tools that carve features and lay down films on wafers for gate-all-around logic and advanced memory 2.
Those tools need precisely controlled gas delivery, which is Ichor's core product, and chief executive Phil Barros says his mix is weighted toward exactly this bottleneck 2. Revenue is up nearly 50 percent in three quarters, and building more of each system in-house lifted incremental gross margin to 33 percent, above the company's own long-term model 12. Notably, the constraint is supply, not demand: the cycle's limiting link right now is parts, which is the stronger signal for the boom itself.
The ramp is financed from Ichor's own balance sheet
Growth at this speed means building inventory and carrying receivables before customers pay. Inventory and receivables absorbed $75 million in the quarter, and nine-month operating cash flow is negative $47.6 million 12. The year's cash cushion came from shareholders: a $195.4 million share sale 1.
Management's defense is fair. Profit-level cash generation of about $30 million was a four-year record, inventory turns and collection days held flat, and customers increasingly backstop the inventory they cause, agreeing to own stock that stops moving 2. That makes the outflow a growth investment rather than deterioration. It still means shareholders, not customers, are fronting the AI buildout's plumbing.
Revenue climbs while operating cash flow goes the other way
Three quarters of rising revenue, three quarters of cash going out the door.
- Revenue
- Operating cash flow
Data
| Revenue | Operating cash flow | |
|---|---|---|
| Q4 2024 | $233.3M | -$2.5M |
| Q1 2025 | $244.5M | $19M |
| Q2 2025 | $240.3M | -$7.5M |
| Q3 2025 | $239.3M | $9.3M |
| Q4 2025 | $223.6M | $9.2M |
| Q1 2026 | $256.1M | -$2.9M |
| Q2 2026 | $294.8M | -$15.9M |
| Q3 2026 | $328.7M | -$28.8M |
December has to show the cash
The fourth-quarter guide already concedes friction: $10 million of revenue removed, split between component shortages and slipped commercial-space launches, with the GAAP earnings midpoint matching the quarter just printed while the adjusted midpoint rises 12. The next morning, both covering analysts kept Buy ratings and cut their targets anyway, and the after-hours surge thinned to under 2 percent by the pre-market 4.
For 2027, management projects earnings growing more than twice as fast as revenue 2. That arithmetic only compounds if working capital stops eating the profit line. Watch one number in the December print: operating cash flow. If it does not turn positive while revenue grows, the leverage is being rented from the balance sheet, and the funding question, more shares or more debt, comes straight back.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.