Jane Street's AXT stake grew to 6.5% while the stock fell a third, and AXT's China fab investors can redeem
AXT's China subsidiary is financing the AI optics squeeze with money investors can claw back in three years, while the stock's largest disclosed holder is a market maker certified to have no influence. The filing that puts the two together is a week old and almost nobody has read the pair side by side.
 Vincent Jiangtwo-minute read
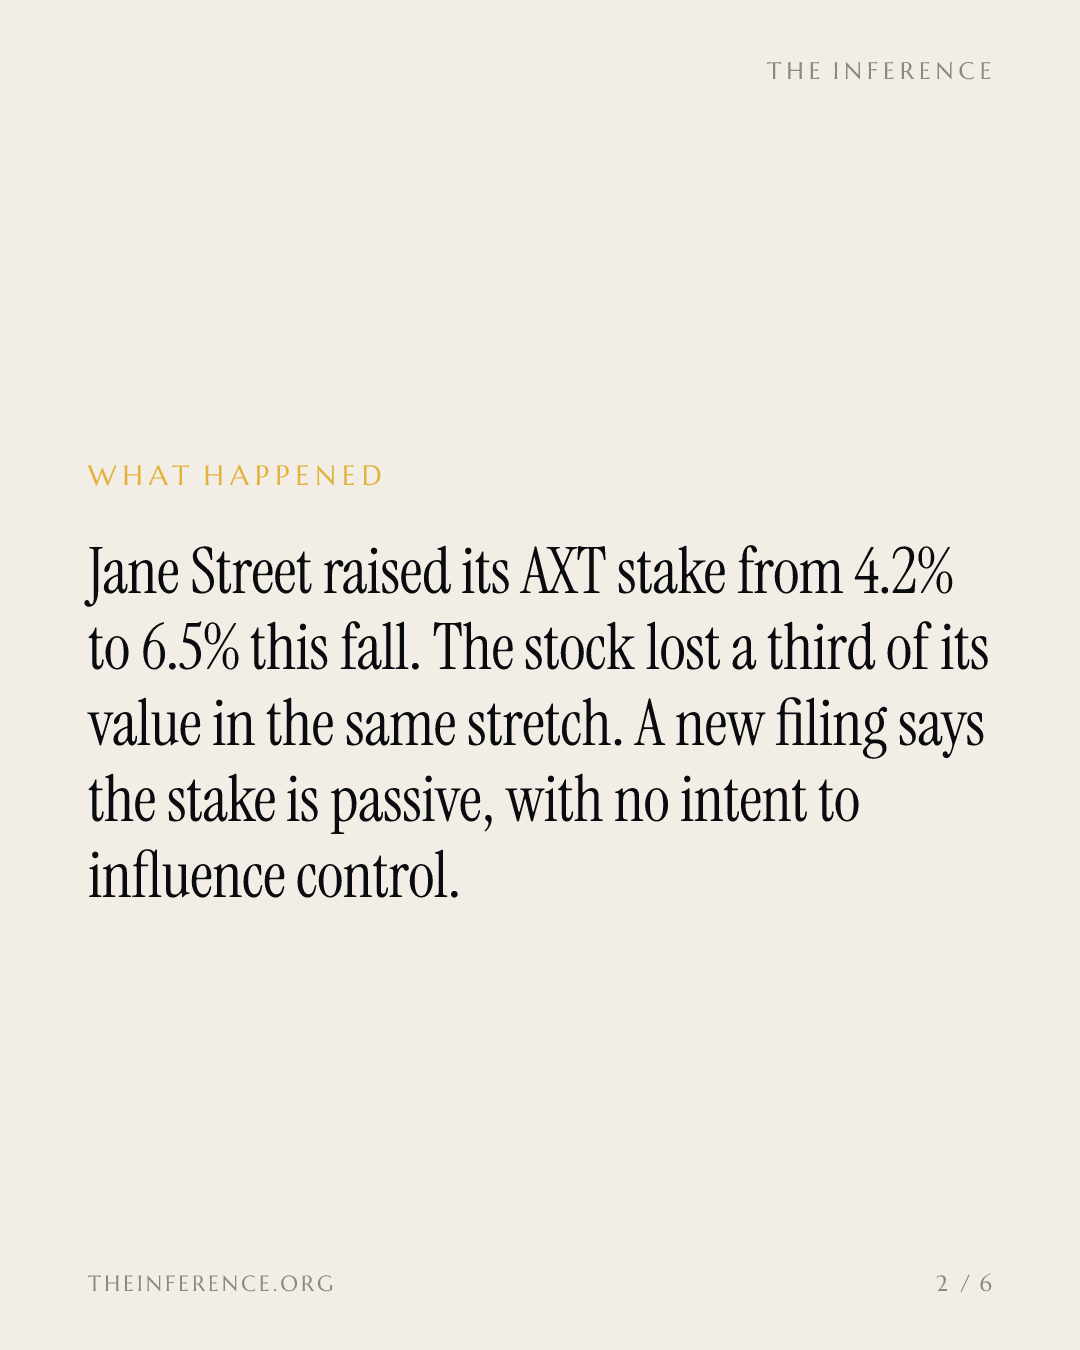
The most interesting document in the AXT story is a certification, signed by Jeremy Kahn for three Jane Street entities on November 9, 2026: the 4,246,421 AXT−7.25% — AXT, down 7.25 percent today shares they hold, 6.5 percent of the class, "were not acquired and are not held for the purpose of or with the effect of changing or influencing the control" of the company 1.
Five weeks earlier, on a September 30 event date, the same filer reported 2,760,847 shares, 4.2 percent 2. That is 1,485,574 shares added through the fall, by a market maker swearing it has no opinion 12.
The squeeze is real, and priced in China
The demand is not in dispute. AXT, the Fremont, California maker of indium phosphide wafers that carry the light inside AI data-center lasers, posted record third-quarter revenue of $73.4 million on October 29, up 162 percent year on year and 54 percent sequentially, beating the $66.0 million FactSet−0.23% — FactSet, down 0.23 percent as of its last quote estimate, at a 56.0 percent gross margin 53. Chief executive Morris Young says demand outpaces supply 5.
AXT's revenue more than doubled in a year on AI laser demand
- AXT revenue
- Estimate
Data
| AXT revenue | |
|---|---|
| Q3 2025 (estimate) | 28M |
| Q2 2026 (estimate) | 48M |
| Q3 2026 | 73.4M |
The complication is a redemption clause
The capacity to relieve that squeeze is being financed at Beijing Tongmei, AXT's majority-owned Chinese subsidiary, where investors from October 28 are committing $285 million to $545 million, AXT adding $400 million of its own and keeping about 73.40 percent at the maximum 65. The terms are AXT's own risk factor: if Tongmei does not complete a qualified IPO within three years, investors can redeem and AXT may have to support them; the agreement dies if closing slips past December 20, 2026 65. Every wafer still needs a Chinese export permit 5.
The market read the structure before the filing: AXTI closed October 28 at $64.38, fell 8 percent pre-market on the disclosure, and by November 9 had lost a third, to $42.91 634. Nomura initiated at Buy with a $90 target on November 4; the six-analyst average target is $91.50 3. Watch December 20, and the permits 3.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.