Manhattan Associates' cloud revenue passed services for the first time, and 2027 cloud growth slows to 20%
The October 27 print delivered the crossover, $134.4 million of cloud revenue against $134.4 million of services, plus a record $2.59 billion backlog. It also marked the engine down: about 20% cloud growth for 2027, on a stock asked to carry roughly 45 times forward earnings on an AI line the company will not publish.
 Vincent Jiang · 3 min read
The crossover quarter
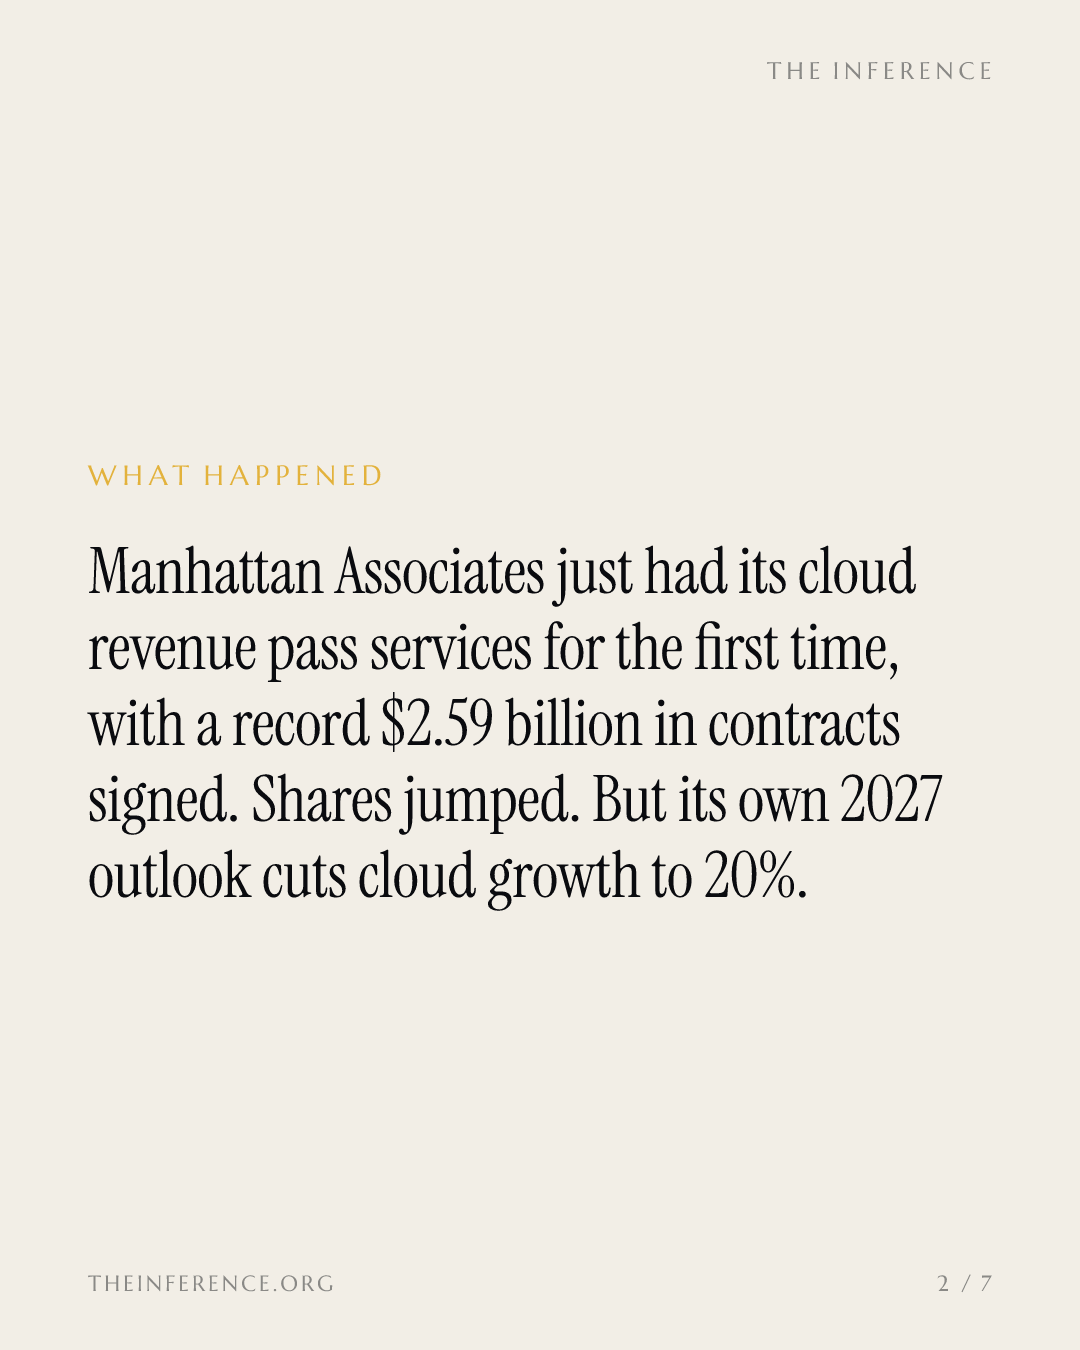
On October 27 Manhattan Associates+3.13% — Manhattan Associates, up 3.13 percent today, the Atlanta maker of supply chain software, crossed the milestone its pitch has been building toward: cloud subscription revenue of $134.4 million, up 28% year over year, passed services revenue, $134.4 million, up 1%, for the first time 12. Total revenue was $306.2 million, up 11%, and remaining performance obligations, the multi-year contracts signed and still waiting to be recognized as revenue, reached $2.59 billion, up 25% 12.
Shares jumped 10.9% after hours 3; Truist−1.40% — Truist, down 1.40 percent today, the investment bank, lifted its price target to $305 from $240 4, and the average of ten analysts' targets rose to $271.4, about 13% above the October 28 close 5. The Form 10-Q, filed on October 30, confirms the crossover, the total and the backlog 2.
The fine print inside the record backlog
The 25% backlog number carries a caveat in the 10-Q itself: about 40% of that $2.59 billion converts to revenue within 24 months, on cloud contracts running five to six years 2. Chief Executive Eric Clark's own arithmetic explains why that matters: five $1 million deals match one $5 million deal on RPO, but each one ramps much faster, so more deals pull more revenue into the current window 6. Faster ramps flatter the current-RPO reading, which means part of the 25% is timing, not fresh demand 6.
The other half of the company
Cloud is now about 44% of revenue 3, and the rest barely moves: services grew 1%, and maintenance shrinks as customers leave legacy contracts 3. That is why 28% cloud growth produces 11% total growth, a full-year guide of 9% all in 14, and management's first color on 2027, offered as "generally appropriate" consensus, puts cloud at about 20% and services in the low single digits 16. The fastest-growing line is decelerating on management's own telling.
Total revenue growth bottomed in mid-2025 and has climbed for four straight quarters
Data
| Total revenue growth, YoY | |
|---|---|
| Q2 '24 | 14.8% |
| Q3 '24 | 11.8% |
| Q4 '24 | 7.4% |
| Q1 '25 | 3.2% |
| Q2 '25 | 2.7% |
| Q3 '25 | 3.4% |
| Q4 '25 | 5.7% |
| Q1 '26 | 7.4% |
| Q2 '26 | 9.3% |
| Q3 '26 | 11% |
Cloud growth steps up through 2026, then management marks 2027 at 20%
- Cloud revenue growth, YoY
- Estimate
Data
| Cloud revenue growth, YoY | |
|---|---|
| Q1 '26 | 24% |
| Q2 '26 | 26% |
| Q3 '26 | 28% |
| 2027 color (estimate) | 20% |
The AI line nobody can audit
The quarter's AI story is strong and unverifiable. Agents convert 100% of pilots into subscriptions, and more customers now skip the pilot altogether 6.
Yet Chief Financial Officer Linda Pinne said the company does not intend to break out revenue by product quarterly and gave no AI revenue metric 16. The cost of that build shows up where the payoff does not: GAAP operating margin slipped to 26.5% from 27.5% a year ago 3, even as the company repurchased a record $325 million of stock in nine months, $50 million of it in Q3, with $175 million of authority left 2.
The peer that shows its meter
Both companies now sell the same thing: AI agents that enterprises deploy alongside paid human deployment engineers, a model monday.com+1.15% — monday.com, up 1.15 percent today named Frontier at Elevate on October 28 7. monday.com publishes its meter, $0.01 a credit, so ten busy agents run about $200 to $250 a month 8. It trades at 40.7 times earnings against Manhattan's roughly 45 times forward 39. The closest comparable shows its math; Manhattan asks investors to take the AI contribution on faith 1.
What settles it
The October 9 piece on the Editions tiers and the October 13 piece on Kesko's agent mandate asked whether the bookings answer would come; October 27 delivered it, along with the 2027 color and monday.com's Frontier meter 166. On this evidence, Manhattan is a candidate for an underweight: the AI line that would justify roughly 45 times forward earnings is one management has said it will not publish 16, and management's own 2027 color cuts cloud growth to 20% 6.
Two dates carry the next readings. The Q4 call brings formal 2027 guidance and promised AI color 6; monday.com reports November 9 8. Until the AI line has a number, the deceleration is management's own and 45 times earnings rests on nothing a filing can check 68.
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.