Micron's $100 Billion Insurance Policy Has a Deductible
Long-term contracts give the memory maker a stronger floor. The stock still depends on how much of today's pricing power survives.
 Vincent Jiangsix-minute read
A falling stock meets a different business model
Sanjay Mehrotra has spent the summer securing customers' promises to buy memory through the next cycle. In June, the Micron−4.50% — Micron, down 4.50 percent today CEO disclosed agreements representing roughly $100 billion of minimum revenue over their remaining terms.1
Those commitments acquired fresh importance on September 14. MU closed at $924.03, down 5.25%, as calls to slow frontier AI development unsettled chip investors.23 Falling share prices do not prove customers have cut orders. They expose the question behind Micron's rally: how much of this profit survives when buyers feel less desperate?
Micron has a more credible answer than it did in earlier booms. Customers are accepting binding purchase commitments and price floors in exchange for supply. That shifts some risk away from the manufacturer. It does not make today's earnings permanent.
Why AI makes ordinary memory scarce
Memory is where working data waits for a processor. High-bandwidth memory, or HBM, places stacked memory chips close to an AI accelerator so it can receive data quickly. Faster processors need enough memory bandwidth to avoid waiting for their next task.
But producing this premium memory consumes scarce manufacturing resources. Micron's published comparison puts HBM3E at roughly three times DDR5's wafer requirement for the same number of bits on the same manufacturing process.4 At August's Hot Chips conference, a Micron fellow explained that the gap grows with newer generations.5
The commercial consequence reaches beyond AI servers. Allocating more factory capacity to HBM can restrict the supply of conventional memory. A computer maker can therefore face higher prices even when its product does not use HBM.
That strengthens Micron's bargaining position across its portfolio. The customer is buying both a chip and confidence that the next production run can happen. For a manufacturer whose finished device cannot ship without memory, accepting a price floor can be cheaper than accepting uncertain supply.
The wafer tradeoff supports this mechanism. It does not establish a permanent shortage: new factories, better manufacturing yields and changes in demand can still alter the balance.
The profit surge came mainly from price
Micron reported $41.46 billion of fiscal-third-quarter revenue, versus $9.30 billion a year earlier, on June 24. Its GAAP gross margin reached 84.6%, up from 37.7%.6
The production data explains why the margin moved so far. Sequentially, DRAM average selling prices rose in the low-60% range, while bit shipments increased only in the low-single-digit range.7 Higher-priced product mix contributed, but this was principally a pricing surge, not a comparable increase in physical output.
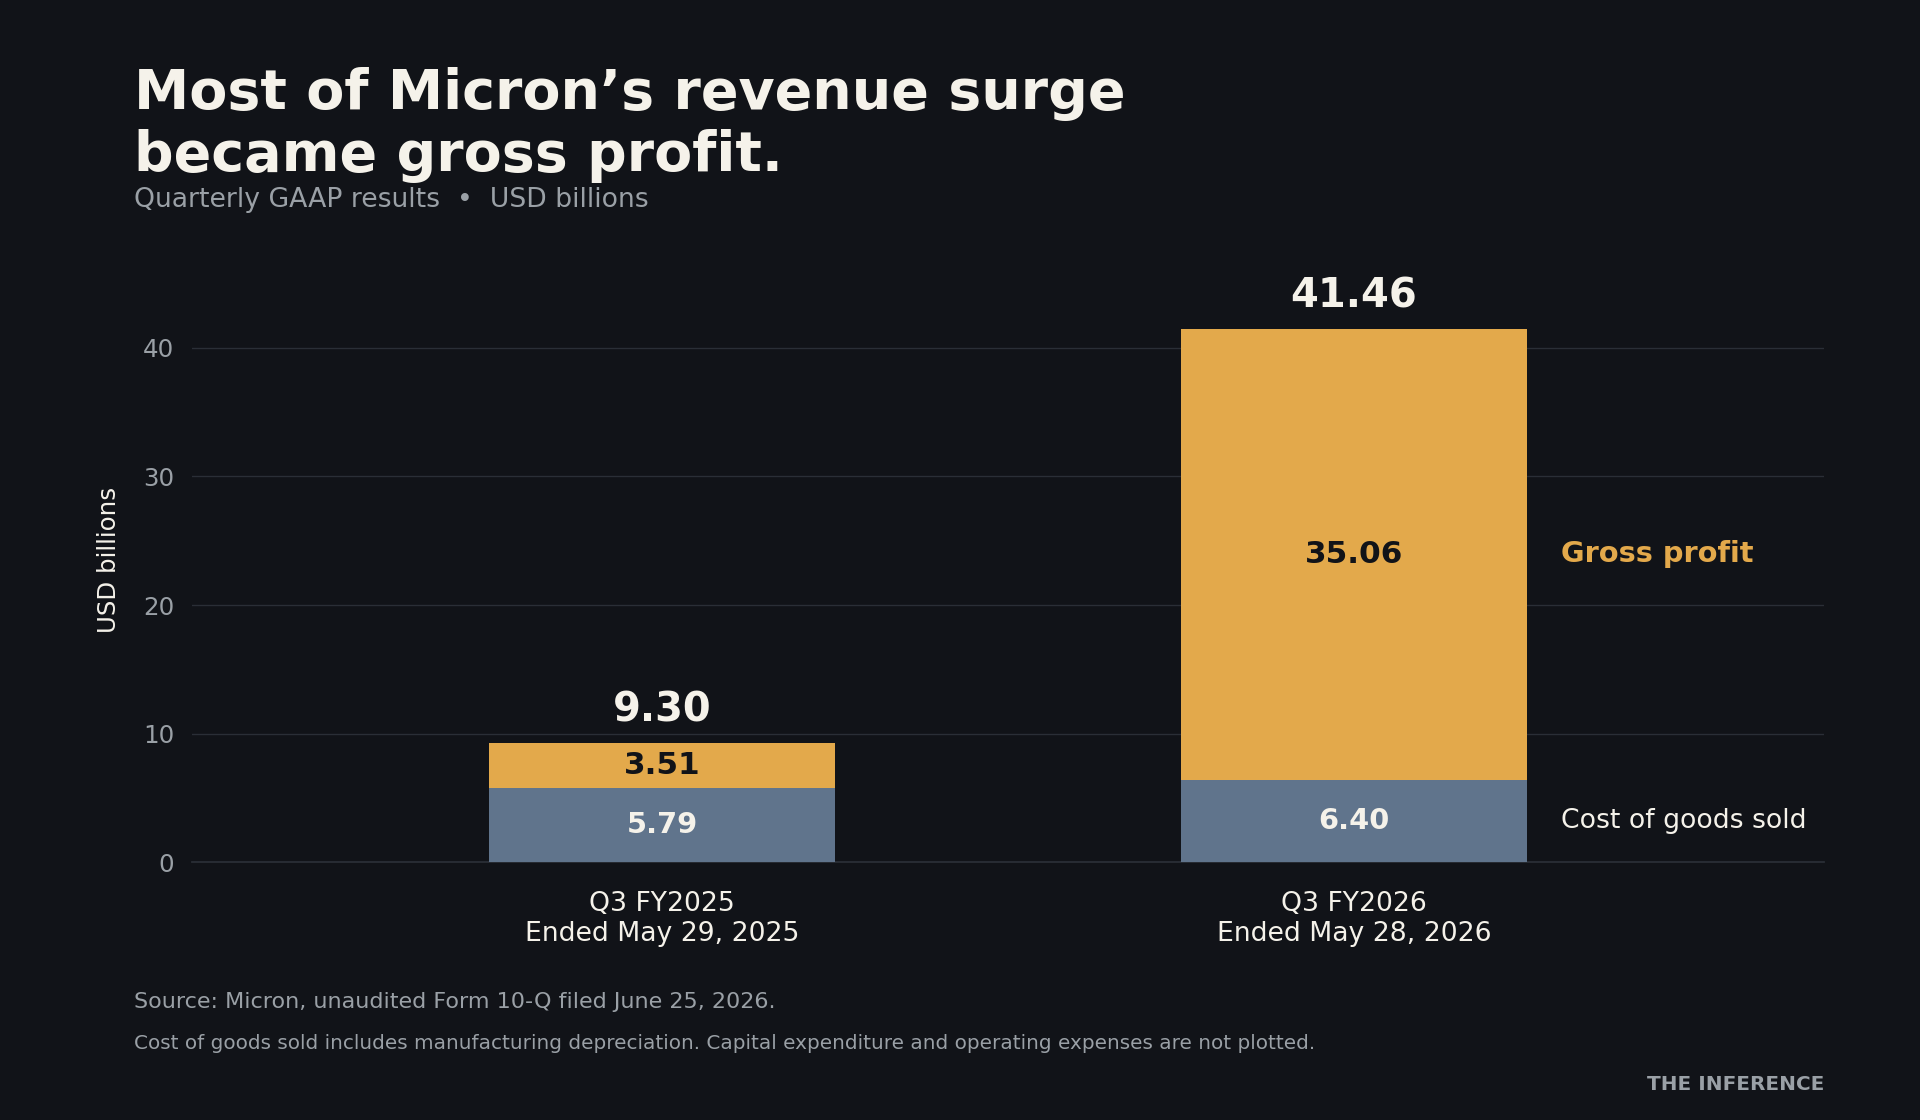
The distinction changes the investment case. Revenue growth driven by additional shipments builds on more units sold. Revenue growth driven by higher prices depends heavily on the bargaining conditions around those units. Both produce cash; they require different assumptions about what comes next.
For now, cash generation is substantial. Micron reported $18.3 billion of adjusted free cash flow after $7.1 billion of net capital expenditure in the quarter.6 That gives the company resources to expand without relying solely on future customer commitments.
The stronger argument for MU is that it can convert today's shortage into both cash and more durable contracts. Simply extrapolating the latest margin misses the work required to preserve it.
Customers get a ceiling. Micron gets a floor.
The June disclosure covered 16 strategic customer agreements, with most running through 2030. Fourteen accounted for the approximately $100 billion minimum-revenue figure. The announced agreements covered roughly 20% of DRAM volume and one-third of NAND volume across that period.18
That is meaningful protection, but clearly partial. Management's ambition to place half or more of company revenue under these arrangements depended on completing additional agreements.8 In August, Micron said it had signed more, without supplying an updated count.9
Under the largest original agreements, prices generally move within a band: the ceiling approximates market prices in calendar Q2 2026, while a floor applies through the term. Some agreements use fixed prices or market pricing instead.7
This is a trade. Buyers surrender some benefit from a future price collapse; Micron surrenders some upside if prices rise beyond the ceiling. Committed supply and a limited price range help buyers plan. Binding demand helps Micron justify factory investment.
The financing matters too. June's $22 billion of expected deposits and related commitments included about $18 billion in cash deposits. Management said these deposits enter financing cash flow, do not increase free cash flow, and are returned toward the latter half of the contracts.8
Data
| Value | |
|---|---|
| Minimum contracted revenue | $100B |
| Deposits & commitments | $22B |
These are not immediate sales or free money. They can reduce Micron's financing burden while leaving future repayment and supply obligations. Investors should separate that benefit from the profitability of the chips eventually delivered.
A price floor cannot guarantee a profit margin
The best bullish argument is that the old memory-cycle playbook has become less reliable. Micron suffered a $5.83 billion net loss in fiscal 2023.10 Long-term commitments could reduce the severity of another downturn, even if they cannot eliminate one. Dismissing these contracts because memory has always been cyclical would ignore an actual change in how risk is shared.
Management expects the price floors to support margins above earlier cycles' quarterly peaks.7 That is a consequential forecast. It is also different from promising that today's company-wide margin continues.
A price floor protects what Micron charges, not what it costs to make the chip.
Micron expects advanced products and new factories to raise blended DRAM costs. Premiums for newer product generations will require future negotiation.8 A contract can provide a revenue floor while its profit contribution changes as production becomes more expensive.
Supply is also responding. September 4 industry reporting described plans to bring Micron's HBM wafer-input capacity toward 100,000 wafers a month by year-end, from roughly 40,000 to 50,000 in 2025.11 That is an industry-source estimate, not a confirmed finished-chip output target. Packaging, yields and customer qualification still determine usable supply.
Finally, contracts operate inside commercial relationships. June reporting raised the risk of customers seeking renegotiation in a weaker market.12 Micron's filing acknowledges enforcement, damages and supply-allocation risks.7 Those are reasons to examine performance, not evidence that the new agreements have already failed.
The cheap multiple depends on the earnings underneath
Micron's June guidance called for $30.73 of GAAP earnings per share at the fiscal-Q4 midpoint.6 Multiply that quarter by four and the annual earnings pace becomes $122.92. At September 14's closing price, the resulting price-to-earnings ratio is approximately 7.5 times.2
That arithmetic explains the stock's appeal. It does not establish a normal year of earnings. The following sensitivity holds the share price constant and changes only the earnings assumption:
| Annual earnings per share | Basis | P/E at $924.03 |
|---|---|---|
| $122.92 | Four times Q4 GAAP guidance midpoint | 7.5 times |
| $80.00 | Illustrative lower earnings | 11.6 times |
| $40.00 | Illustrative deeper decline | 23.1 times |
At an illustrative 15-times multiple, today's price corresponds to $61.60 of annual earnings per share, roughly half the annualized Q4 guidance. A buyer therefore need not assume the current quarter repeats forever. The harder judgment is whether earnings can settle above that level after conditions normalize, and whether the business then deserves that multiple.
No assumption that AI disappears is necessary for the multiple to rise. Profits can fall while demand keeps growing if supply catches up, prices soften or production costs increase. Conversely, durable contract margins and continued demand could make today's valuation attractive without another extraordinary price jump.
The September 30 earnings report offers the next test.13 Beyond the headline results, watch the volume and prices covered by new contracts, deposits actually received, production costs and the outlook for uncontracted sales. Slower model releases may coexist with more spending on running AI systems; the latest selloff does not settle that question.3
Micron has improved its protection against a downturn. The investment turns on the earnings that remain after that protection is needed. On September 30, watch whether management can make that earnings floor more concrete.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.
Reader comments
0 comments