Modine's data-center sales rose 95% and the margin bill came due
Data Centers sales rose 95% to $439.7 million on a fourth straight record order book, yet gross margin fell 470 basis points, net income fell 32%, and first-half free cash flow was negative $145.6 million. Analysts cut targets to $160–215 against a $98.56 stock before the November 18 investor day.
 Vincent Jiangtwo-minute read
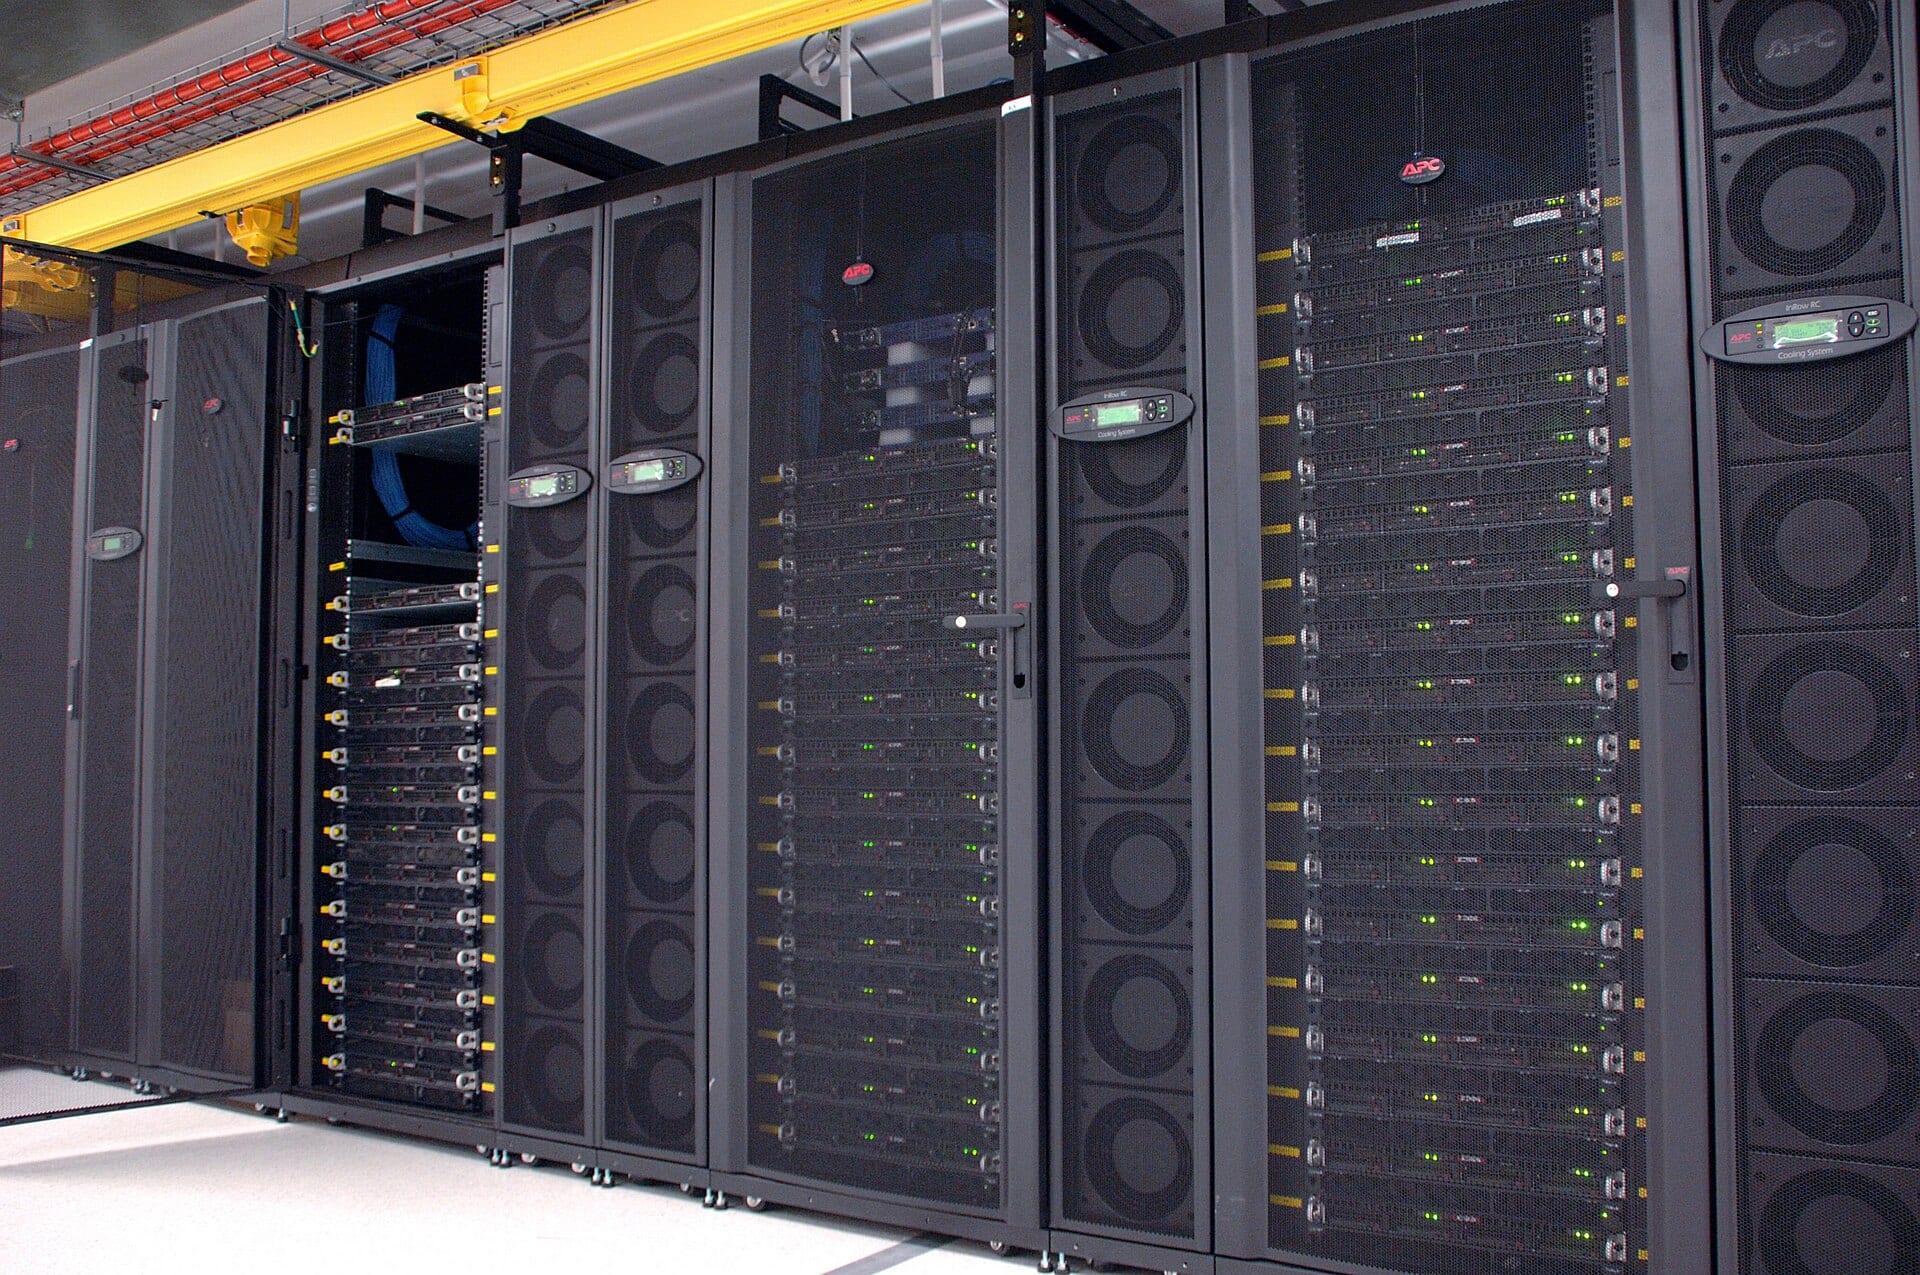
Modine+5.49% — Modine, up 5.49 percent today Manufacturing, the Wisconsin thermal-management group whose coils and air handlers cool AI data-center halls, reported fiscal second-quarter results on November 3, 2026: data-center sales rose 95% to $439.7 million, on more than $1 billion of orders 12. That was the segment's fourth straight quarterly order record, including a $400 million hyperscale air-handler contract running through the end of 2027 12.
The cost of doubling sat in the same release. Segment gross margin contracted 470 basis points to 19.7% on higher material, component and tariff costs, and company net income fell 32% to $30.3 million 12.
The margin is where the boom gets tested
Segment EBITDA margin slipped to 15.4% from 18.1% a year earlier 2. Commercial HVAC told a milder version of the same story: sales up 23% to $285.5 million, gross margin down 140 basis points 1. The quarter still includes Performance Technologies, the auto-parts business spun off on October 1, which moves to discontinued operations next quarter 1.
Data Centers out-earned the business Modine just spun off
Data centers carried more of Modine's quarterly sales than the business it just spun off
Data
| Value | |
|---|---|
| Data Centers | $439.7M |
| Performance Technologies | $287.7M |
| Commercial HVAC | $285.5M |
Hyperscalers place the orders, shareholders fund the inventory
First-half free cash flow was a use of $145.6 million, against $30.3 million a year earlier, as capex rose to $88.5 million and inventories climbed to $697.5 million from $506.1 million in March; net debt reached $573.7 million 1. Management re-based its fiscal 2027 outlook to the continuing business, guiding to $3.1–3.2 billion of revenue and $470–500 million of adjusted EBITDA, growth of 50–55% 12. July's $650–680 million EBITDA range included Performance Technologies, so the absolute ranges do not compare 1.
Gross margin has fallen for five of the last six quarters
Data
| Gross margin | |
|---|---|
| Q2 '24 | 24.6% |
| Q3 '24 | 25.2% |
| Q4 '24 | 24.3% |
| Q1 '25 | 25.6% |
| Q2 '25 | 24.2% |
| Q3 '25 | 22.3% |
| Q4 '25 | 23.1% |
| Q1 '26 | 22.5% |
| Q2 '26 | 20.8% |
| Q3 '26 | 20.7% |
Bulls hold the guide, skeptics hold the targets
Since our October 25 preview, when the tape stood at $133 against Wall Street at $305 (The Inference), the stock has reset further: it traded at $98.56 on November 5 3. Analysts paid for the margin, not the orders 2.
Oppenheimer cut its price target to $215 from $260 on Thursday and UBS cut to $160 from $355 today, November 7, both keeping buy ratings 2. New segment president Michael Mahan has set the falsifiable test: a 20% data-center EBITDA margin by the fourth quarter 2. Longer-term targets land at the investor day on November 18; that is the date the margin promise gets priced or doubted 2. Texas's planned pause on new data-center permits remains the demand-side wildcard behind it 2.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.