NetApp counts 350 AI deals instead of reporting AI revenue, and insiders sold 33 times without buying
NetApp closed its Peak:AIO purchase with no price disclosed, in the same week the books closed on a period of insider selling: 33 sales in six months, not one purchase. The stock's premium rests on an AI business the company has never reported as a revenue line.
 Richard Tang · 3 min read
NetApp−0.11% — NetApp, down 0.11 percent as of its last quote (NASDAQ: NTAP), the enterprise data-storage company, completed its acquisition of Peak:AIO on November 2 and said nothing about what it paid 126. Peak:AIO is the third data-infrastructure company NetApp has absorbed since July 2, and the pattern holds in its reporting: the AI business carrying the stock is disclosed as a count of deals, never as a revenue figure 3.
The stall Peak:AIO fixes is real
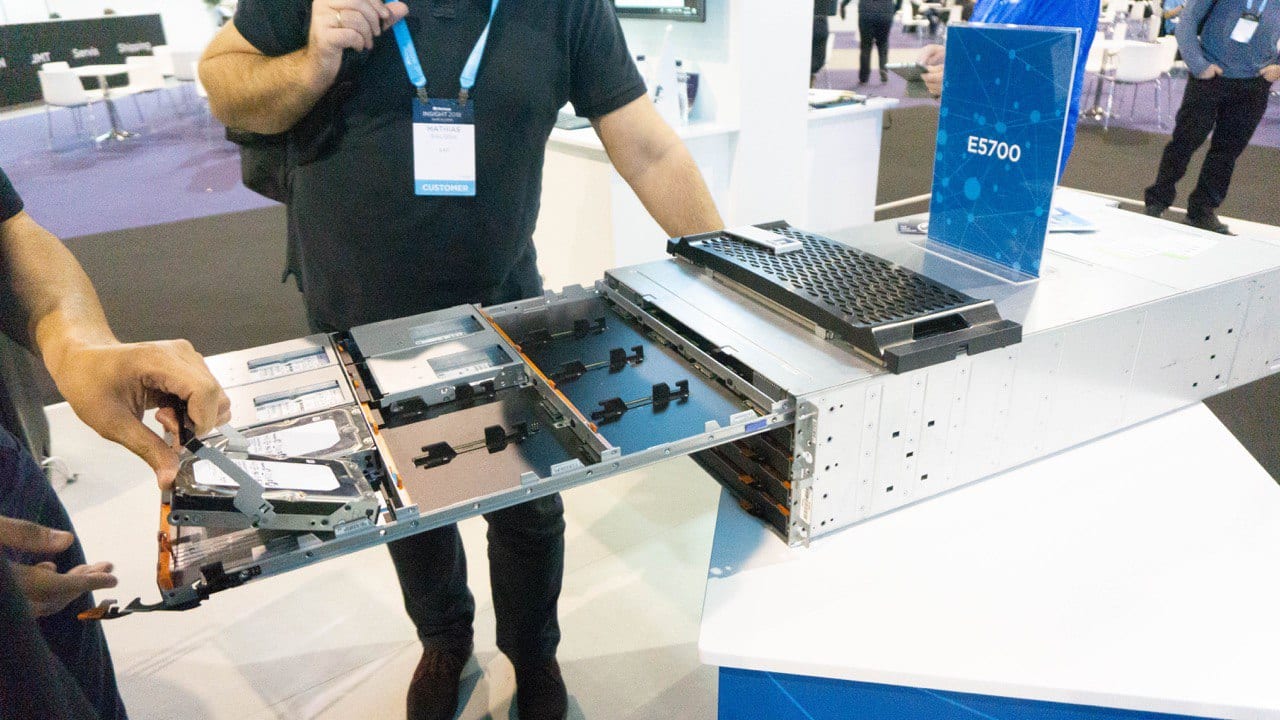
The engineering case is the strongest part of this story. AI clusters idle when thousands of GPUs queue behind a single metadata index, the lookup service that says which file lives where. Peak:AIO, a Manchester company founded in 2021 and proven at Los Alamos National Laboratory, splits metadata from the data path so lookups scale with the number of readers; its Lattice server is an open-source parallel-NFS metadata server 18.
NetApp is folding that into ONTAP, its storage operating system, and Novus, a new architecture aimed at AI clouds and GPU-as-a-service providers 1. Keeping expensive GPUs fed is the right layer to own, and NetApp bought the team that does that work instead of building it.
The AI business is reported as a count, not a revenue line
The reported quarter carries the same shape. Revenue and earnings set records, and management raised the year's revenue guidance by $650 million 34. The AI demand itself appears as roughly 350 AI and data-lake modernization deals, Samsung among them, and nowhere as a revenue line 3. Where AI touches the reported economics, it shows up as a cost: product gross margin slipped to 54.6 percent on component prices, and the quarter that closed in late October was guided to a lower gross margin again 3.
Gross margin has slipped about two points since its late-2025 peak
Data
| Gross margin | |
|---|---|
| Q3 '23 | 71.1% |
| Q4 '23 | 71.7% |
| Q1 '24 | 70.5% |
| Q2 '24 | 71.3% |
| Q3 '24 | 71% |
| Q4 '24 | 69.8% |
| Q1 '25 | 68.9% |
| Q2 '25 | 70.4% |
| Q3 '25 | 72% |
| Q4 '25 | 70.6% |
| Q1 '26 | 70.1% |
| Q2 '26 | 70.1% |
The register is the tell
Insiders have been converting the story into cash. NetApp officers and directors sold 33 times in the past six months and did not buy once 4. Last quarter's insider sales came to about $35 million, most of it from chief executive George Kurian 45. Sales can be planned; a register with no purchases in six months is still a position.
The market pays nearly 18 times forward earnings for NetApp 3. The storage industry averages about 7 3. Barclays−1.53% — Barclays, down 1.53 percent as of its last quote cut the stock to Equal Weight on valuation in October, and the shares fell a tenth in a day at month's end 4.
The print that settles it
The storage layer of AI is a real business, and NetApp is assembling the right pieces of it. This premium, though, is a claim on a number the company has never printed. When the October-quarter results land, one line would settle the case: AI revenue in dollars. Another count of deals leaves the multiple resting on the part of the story that costs margin.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.