Sea's earnings miss was credit and marketing spending, not AI costs
The wires blamed AI costs for Sea's earnings miss, but the company's own expense table shows the money went to lending marketing and credit losses. That distinction decides whether the 9% drop is a capex story or a growth-spending story.
 Richard Tangtwo-minute read
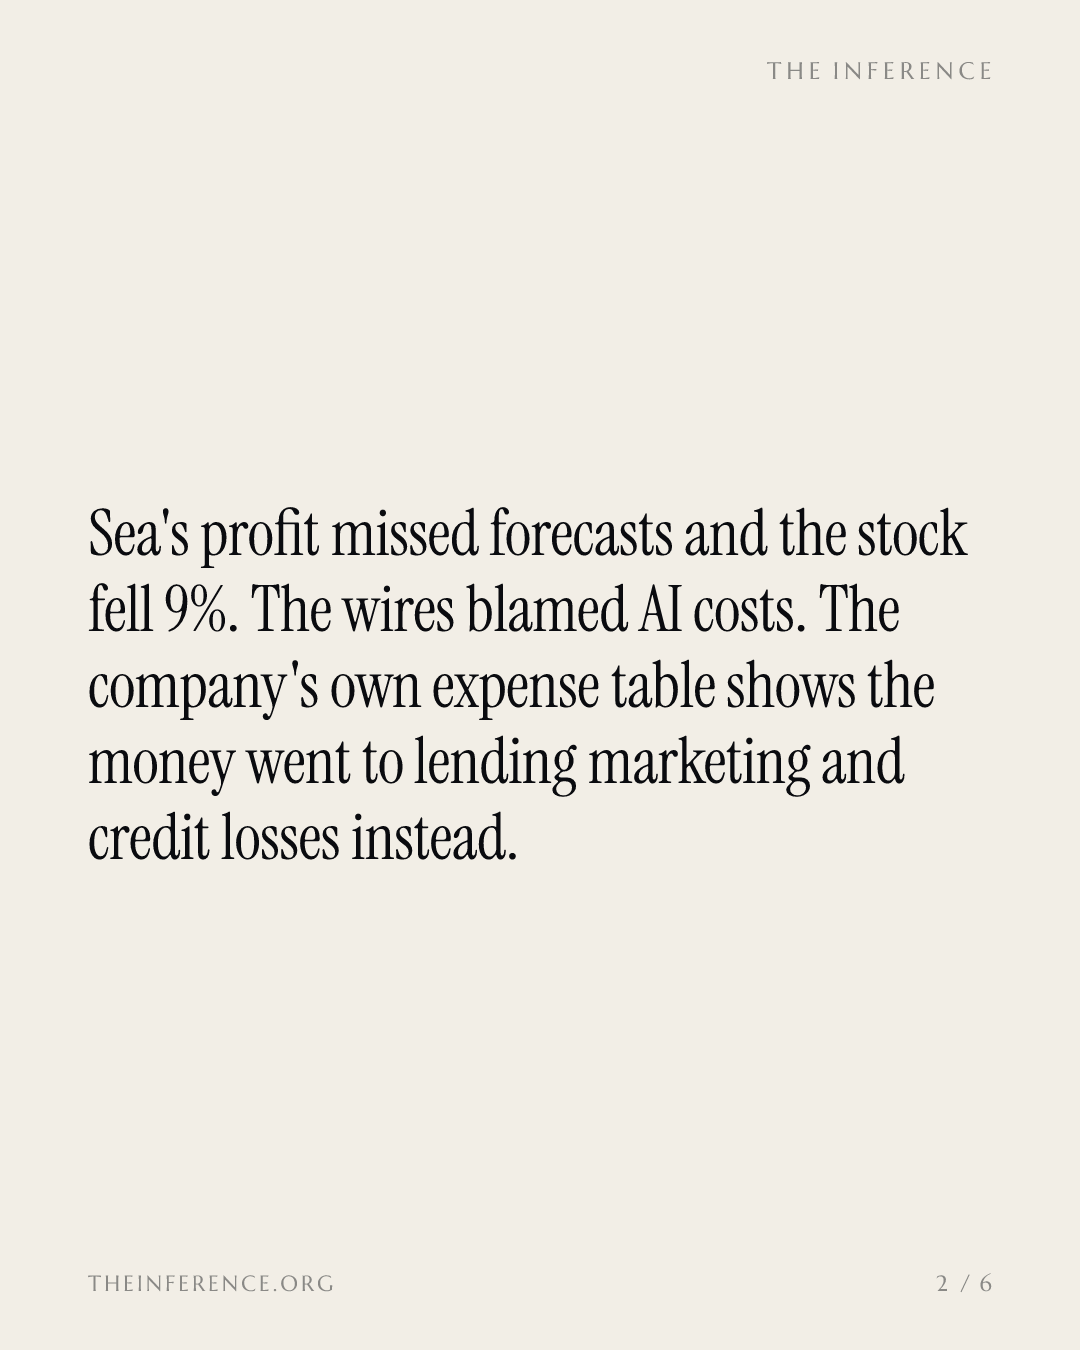
Sea Limited's profit miss this morning was not, on the company's own numbers, an AI story. Revenue beat forecasts by about $500 million and rose 43.4% to $8.6 billion, yet adjusted EBITDA came in at $931 million against a $990 million estimate, and the stock fell 9% to 10% on the day 124. Bloomberg framed the miss as spending on AI features and cloud costs 2. Read the filing's expense table and the money went somewhere else.
The fast-growing cost lines are credit and marketing, not compute
The three cost lines that actually grew fastest are all about lending and promotion, not compute. Sales and marketing rose 64% year-on-year to $1.9 billion, with Monee's marketing bill more than doubling to $334.6 million 1. Provision for credit losses jumped 82.3% to $681.5 million 1. Cost of revenue, the line where server and hosting spending sits, grew 37.2%, slower than revenue 1.
The fast-growing cost lines are credit and marketing, not compute
Marketing and credit provisions grew far faster than revenue; cost of revenue grew slower
Data
| Value | |
|---|---|
| Credit loss provision | 82.3% |
| Sales and marketing | 64% |
| Revenue | 43.4% |
| Cost of revenue | 37.2% |
The margin question is pace of growth spending, not physics
That gap matters for the trade. If margin pressure were AI capex, the bear case would be structural: a 43% grower absorbing an open-ended infrastructure bill that compounds into 2027 13. What the filing shows is a credit engine being funded: Monee's loan book grew 60% to $12.6 billion, its 90-day non-performing ratio ticked up to 1.3% from 1.1%, and its adjusted EBITDA grew just 15.5% on revenue up 63.9% 13. Marketing and provisioning are decisions Sea can throttle; the growth camp and the margin camp are arguing over pace, not physics.
The board's move on November 9 points the same way: after using $997.2 million of its $1 billion buyback, it authorized another $1 billion without expiration 1. Management is spending on distribution and absorbing early credit losses while telling the market it still has capital to return. The AI headline made this look like Sea joined the capex arms race. The filing says it is buying growth in credit, and that is a materially different bet about whose money is at risk.
Get Applications by email, free
How AI is changing the software people and companies use. In our daily email, every weekday.