ServiceNow将AI功能打包,却未将账单打包
Now Assist被内置至全部三个新层级,并依据一个额度池进行计量。超额使用费率并未公开,且仅在签约前可协商。
 Vincent Jiang · 3 min read
以具体岗位命名的层级
一线服务台坐席如今已成为价目表上的一个独立项。ServiceNow于4月9日开始销售的三个层级中,最顶端的“Prime”层级,依据能够承担完整职责的“智能体”数量销售,而服务台正是其明确指定的职责。1
计量的价值已显现
在六月季度,AI业务的年合同总值突破10亿美元,在达38.77亿美元、同比增长24.5%的订阅收入中占据一席。2 至9月9日,该业务全年目标上调至15亿美元。3
“包含”不等于“免费”
原有的五个套餐缩减为三个,而Now Assist被内置到所有套餐中,而非作为附加项存在。1 每个层级都包含一个“辅助”额度池。超出额度池的部分将按使用量计费,且一次智能体调用所消耗的额度远高于一次摘要生成。4
顾问估计,每个“履行者”的额度池大小在1500至6000次辅助之间。超额使用费率可在续费时协商,但一旦错过窗口期便无法更改:若未将相关条款写入协议,则供应商会在额度耗尽时单方面设定费率。4,5 这两项费率均无公开报价。4
“打包”不等于“免费”。打包意味着计量收费。
成本由合同双方共同承担
提供一次辅助服务的成本,体现在该平台自身的毛利率上。六月季度,非GAAP订阅业务毛利率从去年同期的83.0%下降至80.5%,全年指引为81.0%。2 公司将此下滑归因于超大规模云服务使用量增加以及AI业务的采用。6,10
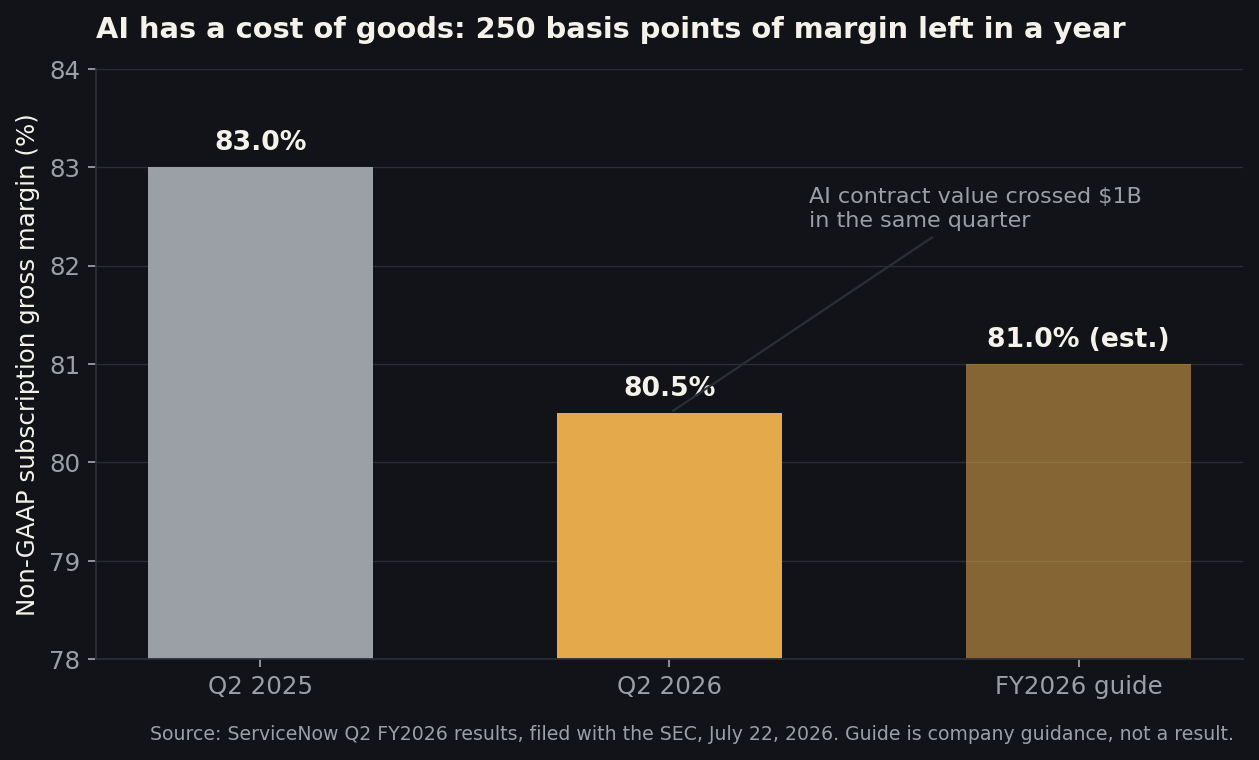
采购方的预算压力也在增加:在续费时,单价上涨8%至12%,并附带每年3%的复合增长条款,而这还未计入任何一次辅助服务的费用。5,7,11 执行这些任务的智能体是通过收购而非自研获得的:ServiceNow以28.5亿美元收购了Moveworks,该交易于去年12月完成,目前该产品已整合到同一个服务包中。8
计量收费的逻辑
计量模式自有其道理。若客户从未用尽额度池,就不会产生额外费用;一位分析师将此结构解读为“先试后买”的路径,而非“过路费”。1 而投资者今年一直在为相反的风险定价,认为智能体会侵蚀按座位收费的软件模式,导致其股价较52周高点下跌约51%。9,12 公司CEO比尔·麦克德莫特(Bill McDermott)表示,这并未拖累销售周期。10
两种看法可能同时成立。但两者都无法告诉采购方超额使用的确切成本,而这种风险敞口从签约次日就已开始。
关注什么
应关注三个新层级下的首批续费客户表现,以及当额度池开始耗尽时,81%的毛利率指引能否在后续季度得以维持。决定这一切的关键数字,并非AI本身的价值。
而是计量表上的读数。
How this brief was made
01Gathered & sourced373 channels · 1,899 articles▾
Agents swept 373 channels and ingested 1,899 articles, then de-duplicated and ranked them for signal.
02Verified & cross-validated12 claims · 31 data feeds▾
Every one of 12 load-bearing claims was checked against primary sources, with 31 live data feeds reconciling the figures and charts.
- 1TechTarget, Apr 2026 (the three AI-native tiers, what is bundled, Prime sold on role replacement; independent trade coverage quoting named analysts at Moor Insights & Strategy and IDC).
- 2ServiceNow Q2 FY2026 results, filed with the SEC, Jul 22 2026 (primary record: $3,877M subscription revenue, 24.5% growth, 80.5% non-GAAP subscription gross margin against 83.0%, AI ACV past $1B, 81% full-year margin guide; guidance is not a result).
- 3Ad-hoc News market report, Sep 2026 (AI contract-value target raised to $1.5B at an investor conference on Sep 9; company-claimed target, not a booking).
- 4Redress Compliance, Now Assist licensing white paper, 2026 (assist pools of 1,500 to 6,000 per fulfiller, top-up negotiable only at renewal, no published unit rate; named licensing advisory with a commercial interest in negotiation work, figures are estimates).
- 5Redress Compliance, ServiceNow cost creep report, 2026 (8 to 12% unit-price rises and 3% compounding uplift clauses at renewal; advisory estimate, unaudited).
- 6Investing.com, Jul 22 2026 (Q2 slide coverage attributing the margin decline to hyperscaler partnerships and AI consumption; editor-reviewed market report).
- 7UpperEdge, 2026 (negotiation timing advisory on consumption terms; commercially interested, not an audit).
- 8CX Today, Dec 2025 (Moveworks acquisition completed for $2.85B in cash and stock; independent trade coverage).
- 9The Motley Fool, Jul 20 2026 (shares roughly 51% below the 52-week high on AI-disruption fears; market commentary, not a valuation opinion this desk endorses).
- 10ServiceNow Q2 FY2026 earnings call transcript, Jul 22 2026 (management on model mix and cost optimisation; company-claimed, speaker text).
- 11NPI, 2026 (buyer-side negotiation benchmarks for the same renewals; commercially interested advisory).
- 12TIKR, 2026 (the counter-case that the 2026 selloff misreads the category; market commentary, single outlet).
03Reviewed & edited2 human editors▾
2 editors read the draft against the evidence, tuned the framing, and signed off before it shipped.
Become a contributor
Reporting on the business of AI and want it read? We take pitches from outside contributors who bring primary sources and a number worth arguing about.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.