SoFi is paying 4.4% for the money stablecoins like Circle's USDC hold for free
SoFi launched SOFIE on October 22, the first tokenized deposit sold to consumers by a US national bank, a day after the OCC finalized the rule that bars stablecoin issuers from paying yield. The contest for the digital dollar now runs through the rate sheet.
 Richard Tang · 3 min read
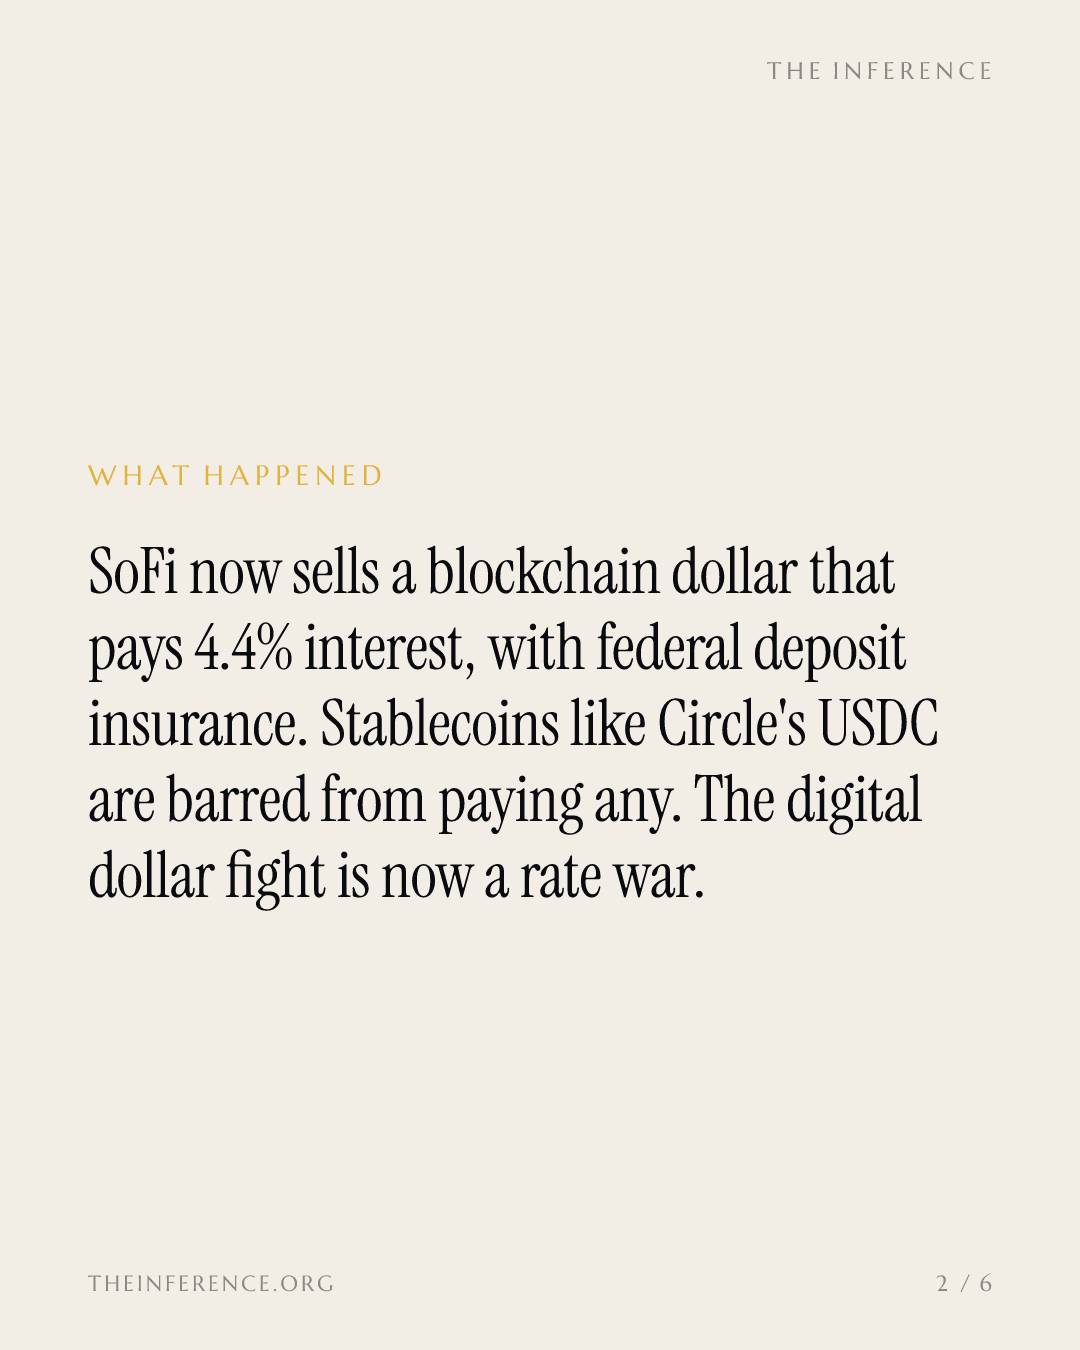
SoFi−0.87% — SoFi, down 0.87 percent today began selling a blockchain dollar on October 22 that pays 4.4%, carries federal deposit insurance, and converts one-for-one into a stablecoin whenever its owner wants to move money 12. It is the first tokenized deposit a US national bank has offered to individuals 2.
A day earlier, the Office of the Comptroller of the Currency (OCC) became the first federal agency to finish writing its rules under the GENIUS Act, the 2025 law governing payment stablecoins, effective January 18, 2027 34. The contest between banks and stablecoin issuers now runs through the rate sheet, and only one side is allowed to use it.
The yield is legal only inside a bank charter
Each SOFIE is a $1 deposit at SoFi Bank, recorded on a blockchain, that earns interest until the customer converts it into SoFiUSD, the bank's stablecoin, for round-the-clock transfers or crypto purchases 25. The GENIUS Act bars issuers such as Circle−4.49% — Circle, down 4.49 percent today and Tether from paying interest to holders, the same provision that sank the Clarity Act in Congress 15.
The OCC's final rule keeps that wall, and exchange reward programs, Coinbase's−4.79% — Coinbase, down 4.79 percent today among them, get no automatic pass: each will be assessed case by case 37. SoFi's design splits the digital dollar in two, a deposit that earns and a token that moves.
SoFi is bidding for the idle money first
CEO Anthony Noto's target is cash parked in yield-less stablecoins. SoFi cites Federal Reserve research putting about $64 billion in rarely used stablecoin wallets 5. "Too much money in the digital asset ecosystem is sitting idle," Noto said 2.
Reach is the limit, because a tokenized deposit moves only between the issuing bank's customers. That is why Noto is courting crypto companies and service providers that already bank with SoFi; since September, SoFi has settled card transactions in SoFiUSD over Mastercard's+1.67% — Mastercard, up 1.67 percent as of its last quote network 12. The rate is funding, not largesse: it matches SoFi's promotional savings rate and feeds a loan book that earns far more 6.
Circle's income is the float itself
Almost all of Circle's revenue is interest on the reserves backing USDC, and that machine has stalled, with year-over-year growth slowing to single digits in the first half of 2026 89. Circle has been building fee businesses, custody and a payments network, to diversify away from rate-dependent income 8.
Circle's revenue flattened in 2026, just as a bank started bidding for the same dollars
Data
| Revenue | |
|---|---|
| Q3 '24 | $445.76M |
| Q4 '24 | $435.37M |
| Q1 '25 | $578.57M |
| Q2 '25 | $658.08M |
| Q3 '25 | $739.76M |
| Q4 '25 | $770.23M |
| Q1 '26 | $694.13M |
| Q2 '26 | $701.32M |
What tells the story from here
Two things settle whether this matters: SoFi's deposit growth, and what the OCC's case-by-case review leaves standing of exchange rewards 37. If SOFIE pulls idle balances out of stablecoins, the squeeze lands on issuer income, not on holders. The reward is accruing to whoever does the middle work of putting a charter, deposit insurance and a card network behind a token. Today that work is being done by a bank.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.