Marvell's $115 billion Lumentum swap already trades $31 billion under the headline, and China now decides it
The fixed swap for the AI laser supplier already trades well below the $115 billion headline, and TrendForce says China's review will turn on one question: whether Chinese module makers keep access to Lumentum's lasers.
 Vincent Jiang · 3 min read
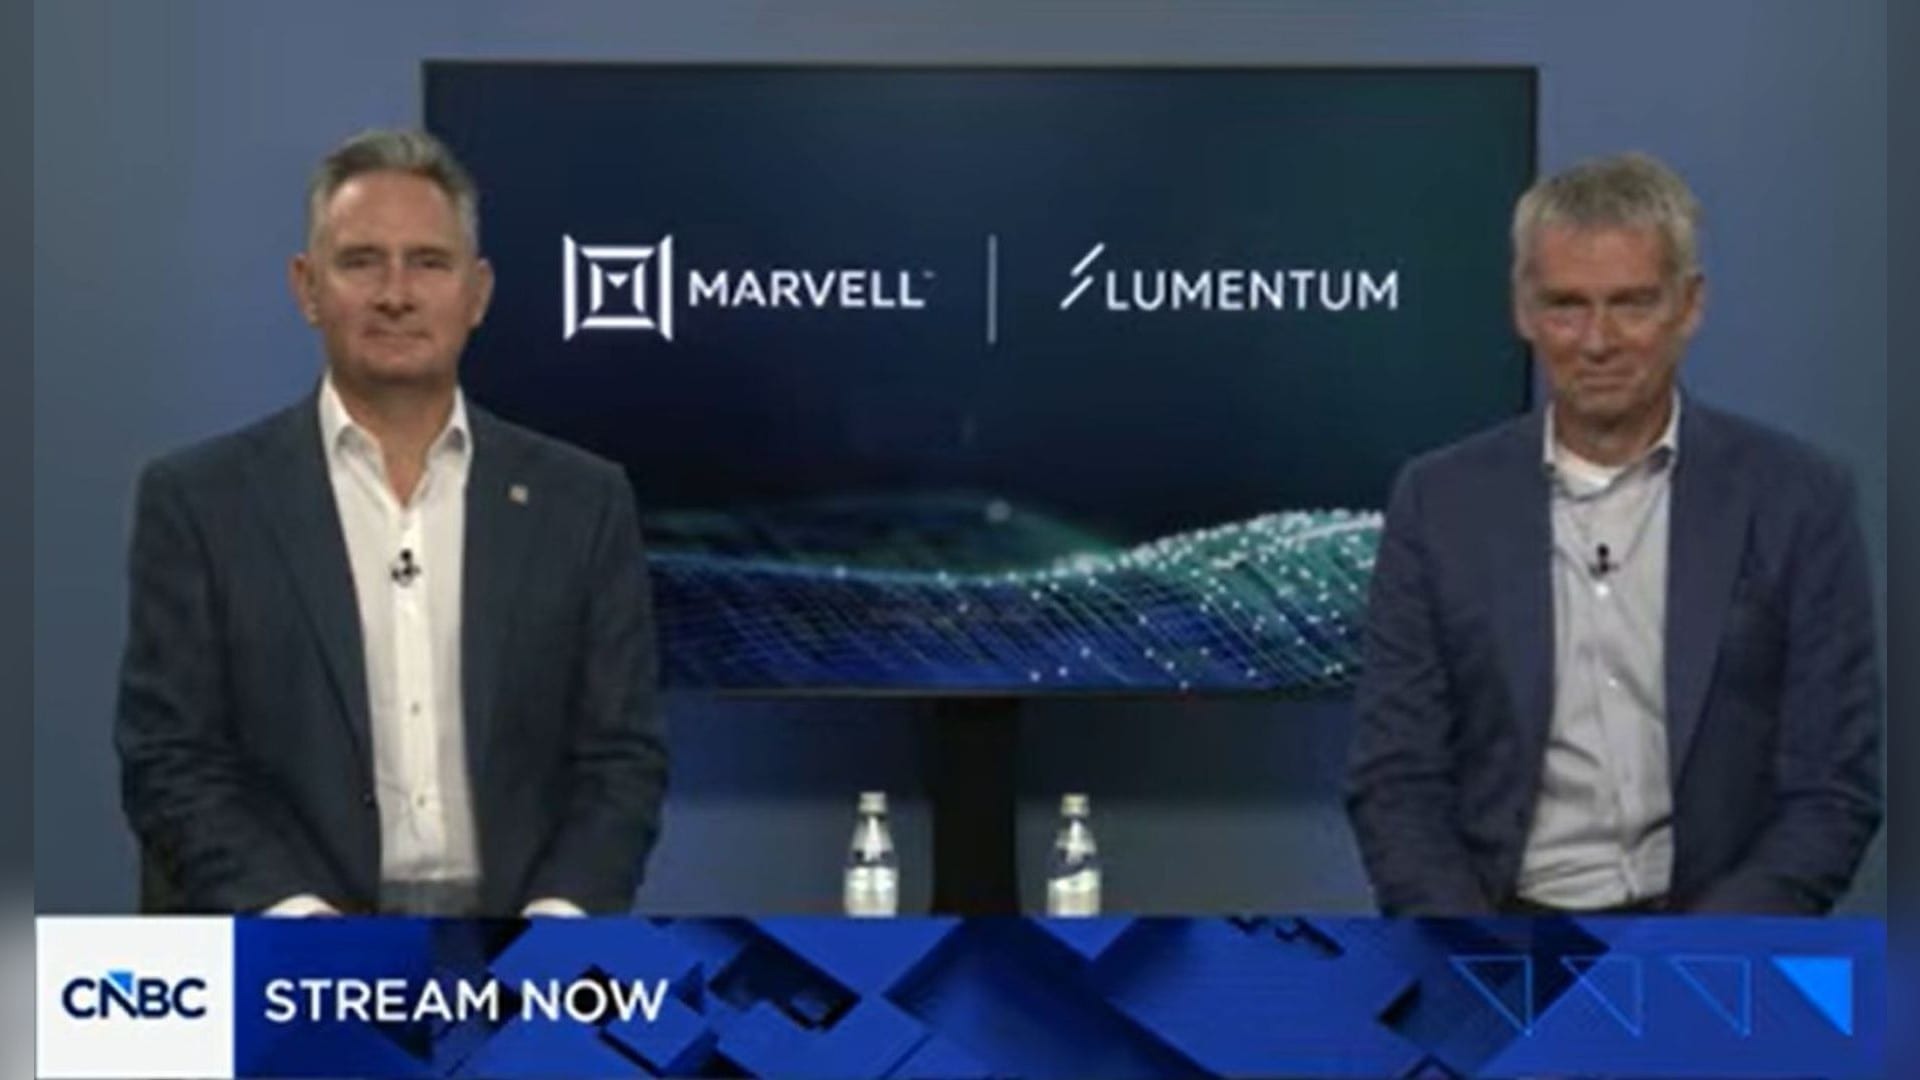
Marvell's $115 billion purchase of laser maker Lumentum, struck on November 2, is already worth less on the table, and the approval that matters most now sits in Beijing. The fixed share swap trades roughly $31 billion below the headline, and TrendForce says China's review will turn on whether Chinese module makers keep their laser supply.
A third of the company, in shrinking paper
Marvell−7.38% — Marvell, down 7.38 percent today is paying all in stock: 4.5 Marvell shares per Lumentum−7.61% — Lumentum, down 7.61 percent today share, a fixed ratio that valued the target at $1,132 a share, a 23.9 percent premium to the October 28 close before Bloomberg reported the talks 13. Lumentum holders receive about a third of the combined company when it closes, expected in the first half of 2028 13.
Because the ratio is fixed, the dollar value floats with the buyer's stock: Marvell fell about 22 percent between the leak and the October 30 close 3. Stifel+6.26% — Stifel, up 6.26 percent today, the broker, reckoned the offer was worth roughly $824 a Lumentum share, about $84 billion, at midday prices on November 2 2.
The fixed swap already trades $31 billion below the headline
The fixed swap already trades $31 billion under the headline
- Estimate
Data
| Value | |
|---|---|
| Announced value, 2 Nov | 115 |
| Stifel mark, midday 2 Nov (estimate) | 84 |
| Inphi deal, 2021 | 10 |
That puts the paper Marvell is handing over about $31 billion below the headline it announced two days earlier 12.
The deal buys scarce laser capacity, but starts by diluting margin
What Marvell gets is scarce. Lumentum's fiscal first-quarter revenue reached $1.26 billion, up 136.5 percent, and its second near-packaged or co-packaged optics win, designs that place optics beside the chip, carries purchase commitments above $5 billion 12. But the combined non-GAAP gross margin of 57 percent sits below Marvell's own 58 percent, so the deal starts by diluting margin, and the more than $1 billion of yearly cost savings only arrive after closing 3.
Beijing holds the decision
The unpriced condition is China. TrendForce expects regulators there to focus on one question: whether Chinese module makers, which buy Lumentum's lasers and Marvell's digital signal processors, the signal chips that shape optical traffic, can keep buying from a company that would also own Cloud Light, a competing module house 14.
The merged group would hold nearly 7 percent of the semiconductor wired communications market, behind only Nvidia−3.00% — Nvidia, down 3.00 percent today and Broadcom−1.99% — Broadcom, down 1.99 percent today, which is the concentration China's review would weigh 4. Conditions requiring open supply would keep the lasers flowing; a block would push customers toward Coherent, the large laser maker left outside any chip designer's control 15.
The deal starts by lifting margin, not diluting it
Data
| Non-GAAP gross margin | |
|---|---|
| Marvell alone | 58 |
| Lumentum | 57 |
| Combined group | 58.7 |
Watch next: the S-4 and the second sources
Nvidia put $2 billion into each of Marvell and Lumentum this year and now owns slices of both sides of the swap 2. Marvell CEO Matt Murphy told Fox Business the split is "very, very compelling for Lumentum shareholders" whatever Marvell trades at 3. The Form S-4, the SEC filing that carries the merger's terms, will carry any break fee and regulatory conditions; China's approval will decide whether Chinese module makers keep access to Lumentum's lasers 3.
Get Deals by email, free
The acquisitions, rounds and contracts that move AI money. In our daily email, every weekday.