Accenture re-rated from 9.8 to 18.6 times earnings as its Asia-Pacific co-CEO sold $1.4 million
Accenture's stock re-rated from 9.8 times earnings to 18.6 in four months, while management disclosed falling prices and its Asia-Pacific co-CEO sold $1.4 million outside any trading plan. On December 17, consulting revenue growth says who is right.
 Vincent Jiang · 3 min read
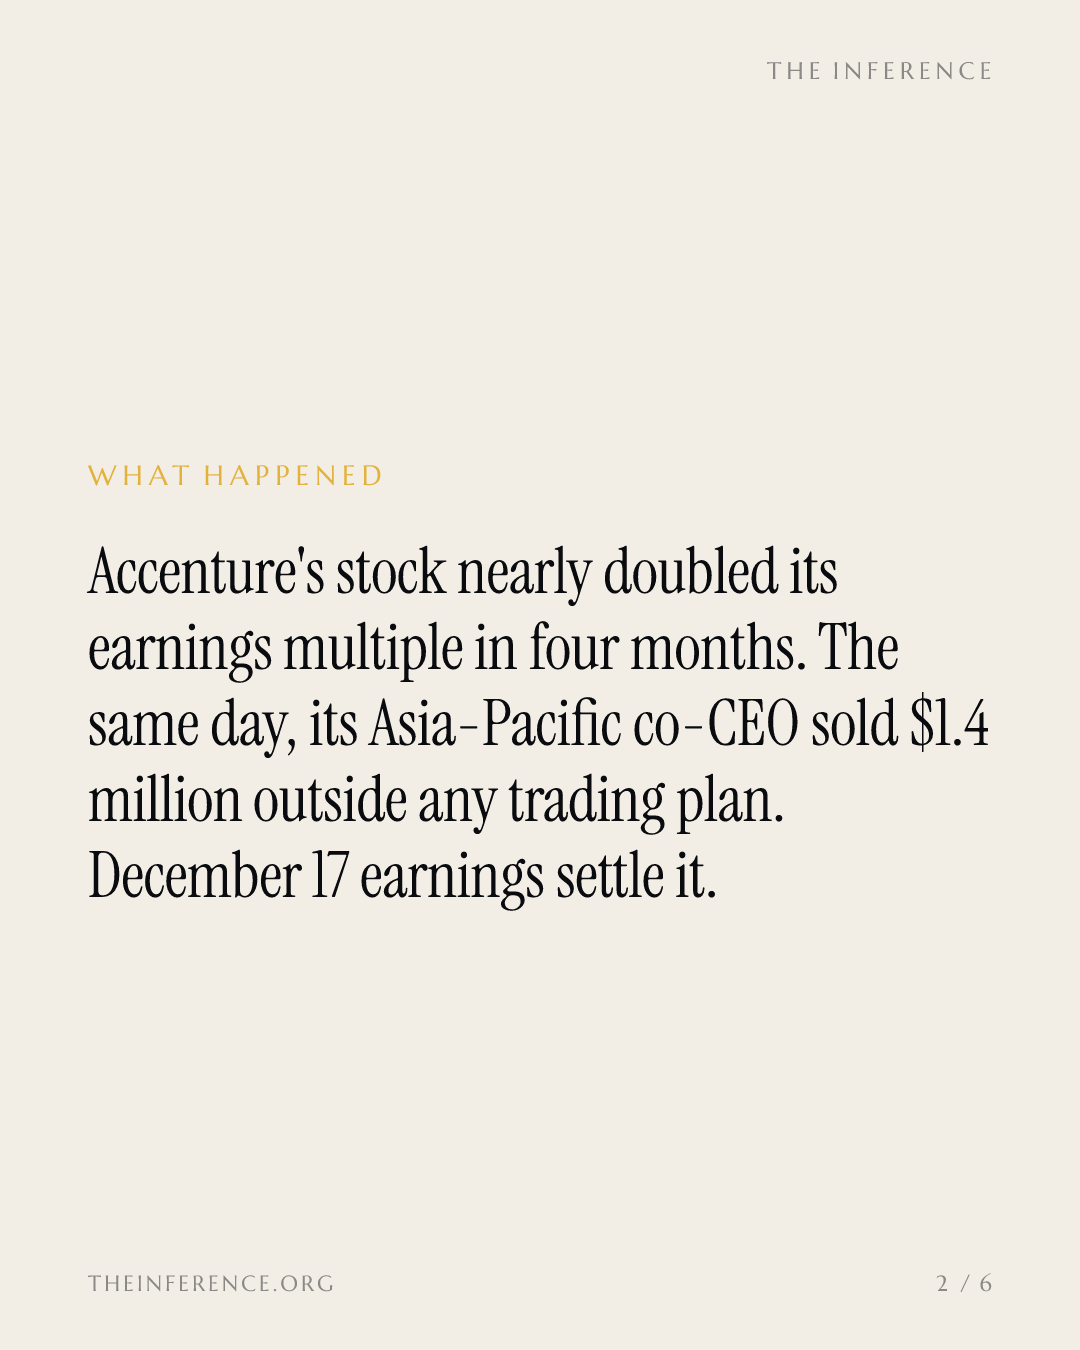
The record: on the same October day the stock stood 12.24% above the average of 27 analyst targets, the executive who runs Accenture's−4.64% — Accenture, down 4.64 percent today Asia-Pacific business sold $1.4 million of it 3. Ryoji Sekido, co-chief executive for Asia Pacific, sold 5,844 shares on October 22 at about $244.84, not under a pre-arranged 10b5-1 trading plan, leaving himself 1,194 shares, per his SEC Form 4 3. The next data point that can vindicate or embarrass that price is dated: Accenture reports its first quarter of fiscal 2027 on December 17 2.
The multiple doubled while prices fell
Accenture, the $153 billion consulting giant with 814,000 employees, closed at $258.74 on October 22, up 41.10% in October and 77.4% over three months against 3.7% for the S&P 500 21. On June 30 it traded at 9.8 times earnings, the cheapest of the last 40 quarter-ends; it now trades at 18.6 times, against 23.0 for the S&P 500 1.
Baird analysts called the rally "warranted" but downgraded the stock to Neutral on October 21 anyway, arguing the valuation already reflects slower growth: they expect 3% to 4% organic revenue growth through fiscal 2029 against an 8% average from fiscal 2014 to 2023 4.
Accenture's earnings multiple has more than doubled since June
- P/E ratio (times)
- Estimate
Data
| P/E ratio (times) | |
|---|---|
| ACN, 30 Jun 2026 | 9.8 |
| ACN, 22 Oct 2026 | 18.6 |
| S&P 500, now (estimate) | 23 |
The company's own words point the other way
On the October 1 earnings call, management said Accenture saw lower pricing in many areas of its business in fiscal Q4, and described the market as highly competitive; pricing was stable for the full year, so the pressure is one quarter old 1. Revenue for the twelve months to August 31 was $74.2 billion, up 6.5%, but consulting, the slower half, grew just 3% in local currency against 6% for managed services 1.
Consulting, the slower half, grew half as fast as managed services
Data
| Growth (%) | |
|---|---|
| Consulting | 3 |
| Managed services | 6 |
| Total revenue | 6.5 |
Guidance for fiscal 2027 is 3% to 6% in local currency, with acquisitions carrying 2 to 2.5 points of it 1. Baird also flagged that contracted revenue, the backlog of signed work, slipped to $37 billion from $38 billion in the quarter 4.
Insider sales are actions, not arguments
Two other officers sold small stakes earlier in October, chief operating officer Catherine Hogan among them 2. Sekido's sale is the sharpest because of what it was not: a scheduled plan sale, filed the day the stock jumped 7.69% 23. A Form 4 shows a decision, not a reason, and no filing carries one 3. It is a signal only in direction, weight comes from what he kept: 1,194 shares, the last of his direct stake 3.
What decides it
Bulls say AI efficiencies are being made up by new kinds of work, as management claims, and the re-rating from 9.8 times proves the market believes it 1. The test is one number: consulting growth in local currency, reported December 17 12. Below 3% and the multiple looks like the first leg of a return toward June's 9.8 times; at or above it, the insider sale was a man diversifying 12.
What happens next
ACNDoes consulting revenue growth in local currency come in at or above 3%, vindicating the re-rating, or below it?
The case for
Baird analysts called the rally warranted, arguing AI efficiencies are being made up by new kinds of work
The case against
Consulting grew only 3% in local currency against 6% for managed services in fiscal 2025, and management itself flagged lower pricing in fiscal Q4
- December 17, 2026Accenture reports first-quarter fiscal 2027 results.
Get our follow-up when these land
Free. We'll email you when we publish on Accenture, and send our free weekday newsletter. Unfollow in one click.