Apollo sells its credit book below book value, and Ares' fee engine grows two days before earnings
Ares Capital agreed today to buy Apollo's MidCap Financial Investment Corporation for about $2.6 billion, a 30.1% premium to the market but below MFIC's reported net asset value. Two days before Ares Management's Q3 report, Apollo is exiting a sub-scale vehicle and Ares is consolidating fee-bearing assets.
 Richard Tang · 2 min read
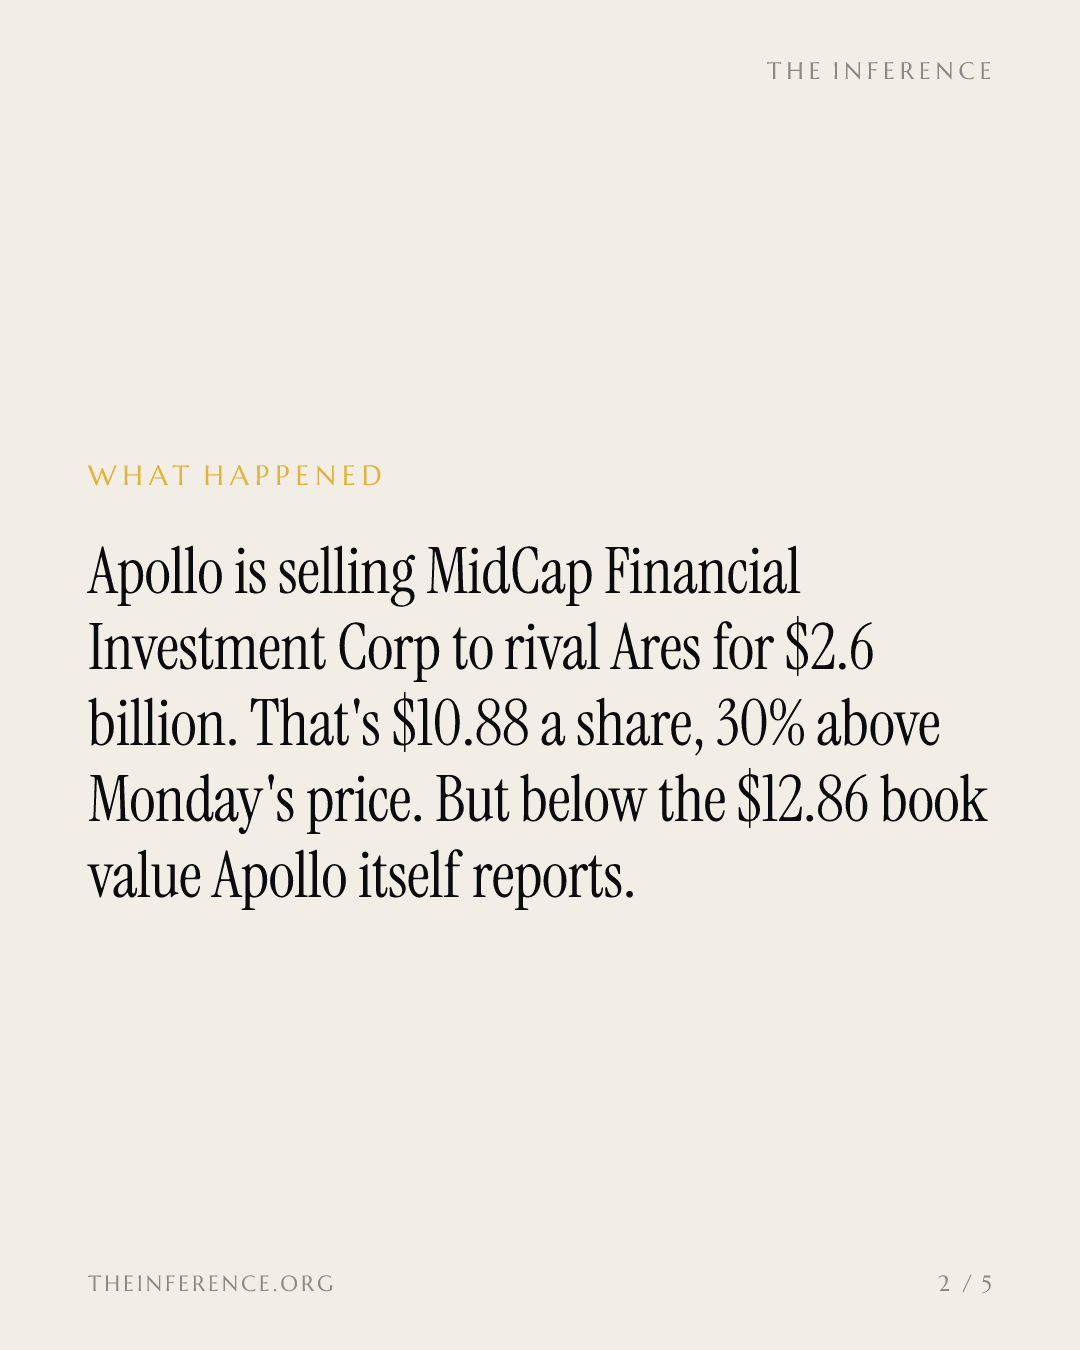
Apollo is selling its own listed credit vehicle to a rival at a price below the value Apollo itself reports for that vehicle's assets. That is the tell in today's deal: Ares Capital (ARCC), the largest publicly traded business-development company and the engine of Ares Management's+0.19% — Ares Management, up 0.19 percent today credit fee stream, agreed to acquire MidCap Financial Investment Corporation (MFIC) for about $2.6 billion in enterprise value 1.
For MFIC holders that is $10.88 a share, a 30.1% premium to Monday's close but under the $12.86 net asset value MFIC estimated for September 30 1. A premium to the market and a discount to NAV at the same time means both boards agree the shares will never trade to book value on their own.
MFIC holders get a premium to market but still leave NAV on the table
Data
| MFIC per share | |
|---|---|
| Monday's close | $8.36 |
| Deal price | $10.88 |
| Sept 30 NAV estimate | $12.86 |
MFIC holders arbitrage a NAV they will never see in full
They get roughly $1.21 in cash, funded by an Ares Management subsidiary, and the rest in ARCC stock, plus a special dividend of MFIC's undistributed income before closing 1. They also share in half of any ARCC price premium over NAV, capped near book value 1.
It is a rational arbitrage on a NAV that only a consolidator could unlock, and the independent directors called it value-maximizing 1. Apollo's affiliates hold just 5.2% and signed voting agreements; John Zito, Apollo's co-president, framed the sale as part of a year of "supporting stockholder value across our public vehicles" 1. Selling below your own stated NAV is a strange way to spell support, but exiting a sub-scale vehicle into the sector's largest one is defensible portfolio logic.
Thursday's print decides whether the fee pipeline converts
The strategic weight falls on Ares Management (ARES), which reports Q3 on October 29 2. The stock is down about 22% this year and estimates have slid for three months, and the bull case rests on $114 billion of assets not yet paying fees that management says could eventually add roughly $828 million of annual management fees 2.
The MFIC portfolio is immediately fee-bearing the day it closes, expected in the first half of 2027 with Wells Fargo−0.07% — Wells Fargo, down 0.07 percent today providing $750 million of financing 1. Thursday's print decides whether the rest of that pipeline converts too. Watch fee-paying AUM, not the headline beat.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.