Applied Digital's interest bill passed its rent for the first time: $77.4 million vs $65.8 million
Applied Digital's quarterly interest expense passed its base rent for the first time, and its CEO says 800 megawatts of the buildout still needs financing. The AI buildout's bottleneck has moved from demand to the price of borrowed money, and shareholders are absorbing the difference.
 Richard Tang · 3 min read
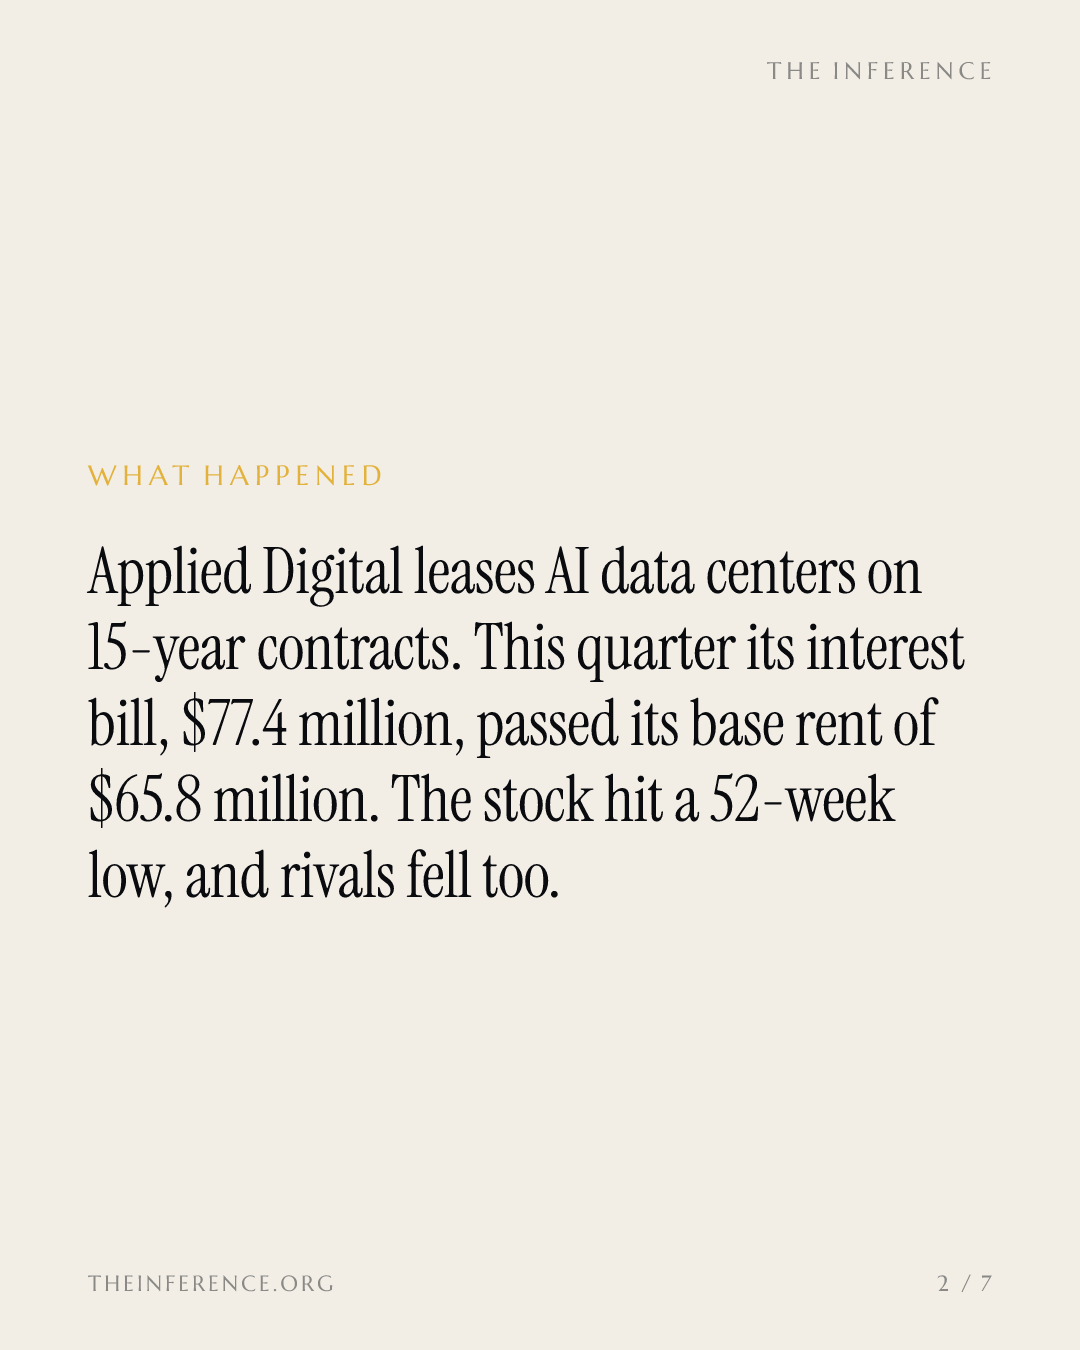
For the first time, Applied Digital's+0.99% — Applied Digital, up 0.99 percent today quarterly interest bill has passed its rent. In the quarter ended August 31, the AI data-center landlord booked $77.4 million of interest expense 1. Its base rent came to $65.8 million, less than the interest for the first time since the leasing business began 12. That arithmetic, not any wobble in demand, took the stock to a 52-week low of $17.16 on November 2 and pulled Nebius+3.97% — Nebius, up 3.97 percent today, CoreWeave+2.00% — CoreWeave, up 2.00 percent today and IREN+2.36% — IREN, up 2.36 percent today down about 6% with it 23.
Lenders now collect more than the tenants pay
The mechanism matters more than the headline. Applied Digital builds powered campuses and leases them on take-or-pay contracts of 15 years or more to investment-grade hyperscalers 5. It holds roughly $36 billion of contracted revenue across five campuses 1.
It has leased 1.41 gigawatts of capacity and switched on 250 megawatts, so most of the rent is still to come while the debt is drawing now 1. Fit-out fees and interest on its $3.7 billion cash pile narrow this quarter's gap 18, but fit-out is pass-through construction work; the recurring rent is what has to carry the debt.
Capex has outrun revenue for nine straight quarters, on borrowed money
- Revenue
- Capex
- Total debt, quarter-end
Data
| Revenue | Capex | Total debt, quarter-end | |
|---|---|---|---|
| Q2 '24 | $0.04B | $0.04B | $0.14B |
| Q3 '24 | $0.04B | $0.06B | $0.43B |
| Q4 '24 | $0.04B | $0.17B | $0.8B |
| Q1 '25 | $0.05B | $0.26B | $0.99B |
| Q2 '25 | $0.05B | $0.17B | $0.91B |
| Q3 '25 | $0.08B | $0.25B | $0.7B |
| Q4 '25 | $0.13B | $0.55B | $2.61B |
| Q1 '26 | $0.13B | $0.78B | $2.83B |
| Q2 '26 | $0.26B | $1.29B | $5.1B |
| Q3 '26 | $0.34B | $2.08B | $6.48B |
The bottleneck moved from demand to the price of money
On November 2, chief executive Wes Cummins told CNBC that about 800 megawatts still need financing over the next 12 months, and he rejected the compute-seller label: "We're effectively a highly technical real estate business 45. Long-term leases, high-quality tenants." 45 The unfinanced capacity is leased to tenants rated AA or better, he said, and the bond market stays open at a price 5.
The price is the story. Macquarie's preferred equity in the campuses earns 12.75%, a rate we mapped in October when the lender side drew its line; the newest secured notes were sold at 7% 124.
Elon Musk, having borrowed $40 billion for SpaceX's+0.74% — SpaceX, up 0.74 percent today own chips, says debt markets have "almost entirely shut off" for anyone without revenue independent of data centers, promising "guppy-level death" for the 200-plus neoclouds 67. Nvidia's+2.91% — Nvidia, up 2.91 percent today Jensen Huang names the same constraint from the other end: demand is "off the charts", capital is what is scarce 6.
Shareholders hold the gap; the tenant's credit is the collateral
Who pays is the equity, down 51% in a year 2, with fiscal-2028 consensus swinging in three months from a small profit to a projected loss of 78 cents a share 24. Who benefits is the tenants. CoreWeave, about 30% of contracted revenue, rents campuses financed on someone else's balance sheet, and its own customer at the site is Meta+0.45% — Meta, up 0.45 percent today, which Cummins says improves the credit 245.
Revenue is running four times last year's level; the net loss widened anyway
- Revenue
- Net income (loss)
Data
| Revenue | Net income (loss) | |
|---|---|---|
| Q4 '24 | $0.04B | -$0.14B |
| Q1 '25 | $0.05B | -$0.04B |
| Q2 '25 | $0.05B | -$0.05B |
| Q3 '25 | $0.08B | -$0.02B |
| Q4 '25 | $0.13B | -$0.02B |
| Q1 '26 | $0.13B | -$0.1B |
| Q2 '26 | $0.26B | -$0.11B |
| Q3 '26 | $0.34B | -$0.24B |
CoreWeave itself owes $51.6 billion against $5.5 billion of cash, and its interest bill already runs at about a quarter of its revenue 7. The demand for AI compute is signed; the debt that houses it is not. January's fiscal Q2 report prices the next tranche, and whoever can fund the gap cheapest captures this stretch of the buildout 7. None of this argues against AI adoption; it argues for reading the financing hop as closely as the model releases.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.