Arbs earn about 3% a year to wait out Proofpoint's $6.3 billion Varonis buyout
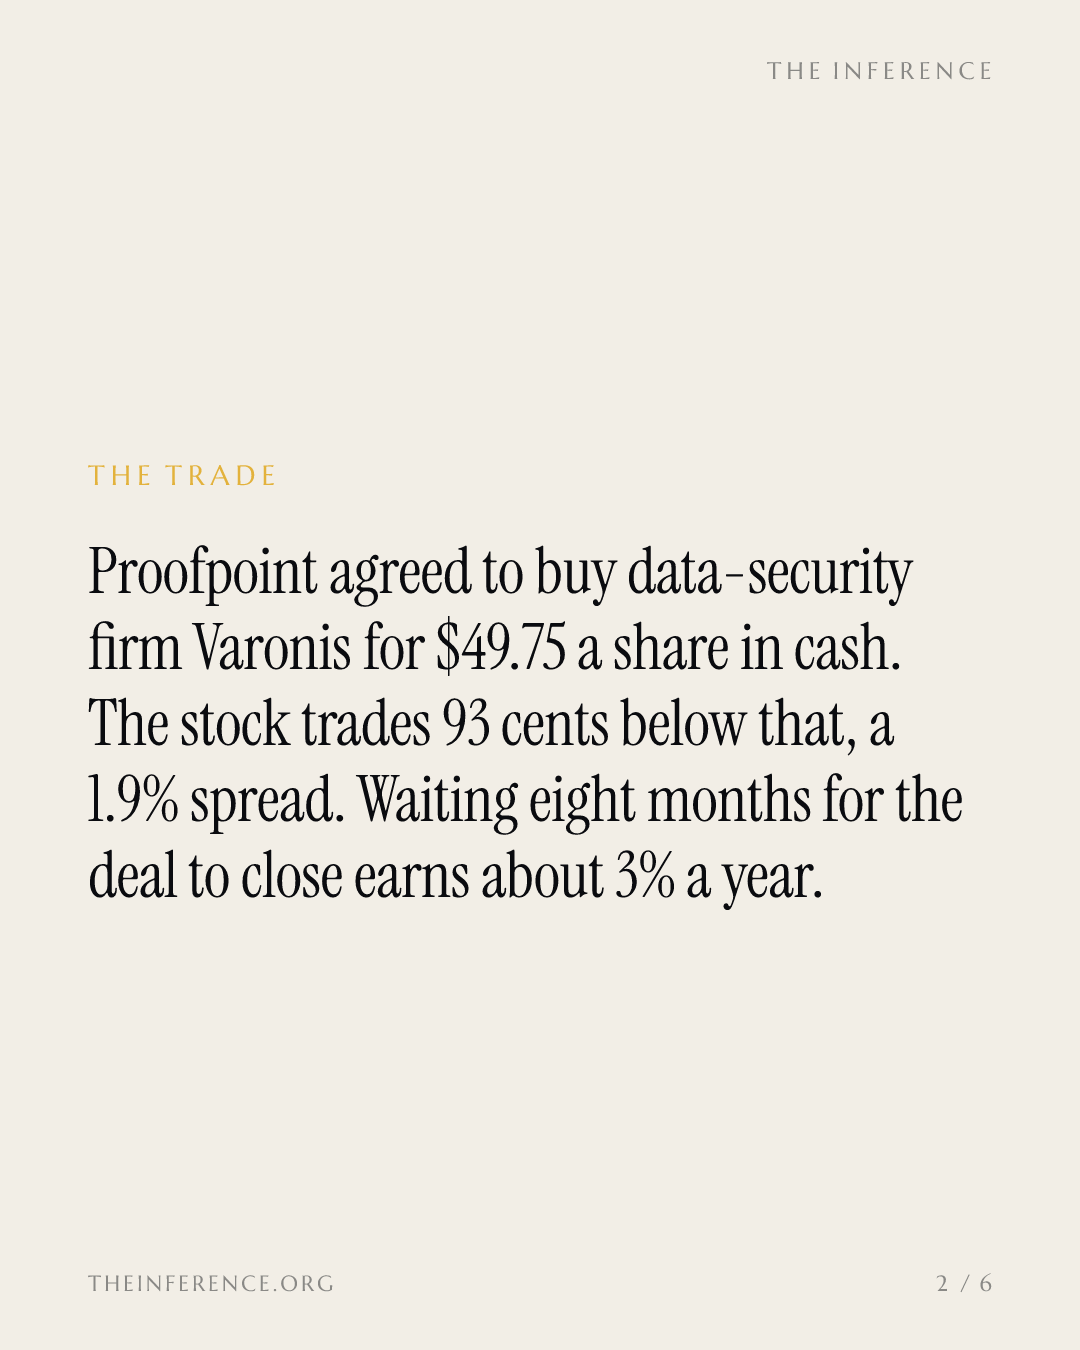
Proofpoint agreed to pay $49.75 a share for Varonis, the stock sits 93 cents under the deal price, plaintiff firms are circling a $63.80 peak, and the private rival in the same category is asking for $20 billion.
 Vincent Jiang · 4 min read
Proofpoint, the Thoma Bravo-owned security vendor, agreed on October 15, 2026, to buy Varonis, the data-security software maker, for $49.75 a share in cash, a transaction worth about $6.3 billion, with the Varonis−0.08% — Varonis, down 0.08 percent today board approving unanimously 1. Close is expected in the first half of 2027, subject to shareholder and regulatory approvals 1.
Thoma Bravo committed the equity and secured debt financing, and Ontario Teachers' Pension Plan agreed to invest into Proofpoint alongside 1. Proofpoint is paying 8.4 times trailing revenue and 53 times trailing free cash flow for a company whose second-quarter revenue grew 18.3% to $180.02 million, with adjusted earnings of $0.04 a share beating the $0.01 consensus 12.
Growth re-accelerated to 18.3% in the quarter Proofpoint priced
Data
| Revenue | |
|---|---|
| Q1 '24 | $114.02M |
| Q2 '24 | $130.35M |
| Q3 '24 | $148.07M |
| Q4 '24 | $158.51M |
| Q1 '25 | $136.42M |
| Q2 '25 | $152.16M |
| Q3 '25 | $161.58M |
| Q4 '25 | $173.37M |
| Q1 '26 | $173.13M |
| Q2 '26 | $180.02M |
The premium math exposes the leak. $49.75 is 52% above the $32.71 close on June 22, the last day before the first sale rumors, but only 17% above the $42.35 close on September 1, the day before "additional media reports speculating about a potential sale" 1. The stock added just 2.5% in after-hours trading when the agreement surfaced on October 15 4. The deal was priced before most of the public could act on it.
The spread
Varonis closed at $48.89 on October 22, the day it told noteholders about the merger 3, and traded at $48.82 by October 29, 93 cents under the cash price 4. That is a 1.9% gross spread; with closing roughly eight months out at the back edge of the guided window, the annualized return works out to about 2.9% 4. Short interest sits at 5.51% 4. Waiting through a shareholder vote and regulatory clearances for under 3% a year is pocket change, not payment 4.
The deal price sits $14.05 below this year's high, 93 cents above the tape
Data
| Value | |
|---|---|
| 52-week high | $63.80 |
| Deal price | $49.75 |
| Market, Oct 29 | $48.82 |
Noteholders get paid only on closing
A October 22 notice to holders of the 1.00% convertible senior notes due 2029 says the merger will constitute a Fundamental Change, a Make-Whole Fundamental Change and a Corporate Event "as of the Effective Time," and that if the merger "is not consummated for any reason, then none" of the three events will have occurred 5. In plain terms, the make-whole protection pays only on closing. The note spread and the equity spread carry the same condition: no close, no pay.
The two camps on price
Halper Sadeh LLC, an investor rights law firm, is investigating whether the board obtained the best possible price, ran a fair process and disclosed everything shareholders need 6. Wohl & Fruchter is questioning the price against the stock's 52-week high of $63.80 3.
The board's answer is on the record: an independent committee ran "extensive outreach to a range of potential strategic and financial buyers," and CEO Yaki Faitelson called the price "immediate, significant, and certain value well in excess of the risk-adjusted value" of the standalone plan 1.
The category reprices while the deal waits
Cyera~$3B — Cyera, private, latest valuation ~$3B, the private company selling data security for the AI age in the same category as Varonis, added a $400 million Goldman Sachs extension to its Series G on September 22, on top of a $600 million round led by Evolution Equity Partners in June 78. Six outlets reported this week that Cyera is in talks at a $20 billion valuation, a figure no company filing confirms 8.
Proofpoint is locking the category's public benchmark at 8.4 times revenue while its closest private rival asks for 67% more than the $12 billion mark Goldman−4.59% — Goldman, down 4.59 percent today underwrote a month earlier 178. Every dollar of credibility the Cyera ask gains is a dollar of ammunition for the firms arguing $49.75 is light 178. The Inference followed the money into Cyera when Goldman wired its check in September; this week's reported repricing is what is new.
Cyera raised $1.4 billion in three 2026 checks before this week's $20 billion ask
Data
| Amount raised | |
|---|---|
| Series F, Jan 2026 | $400M |
| Series G, Jun 2026 | $600M |
| Goldman extension, Sep 2026 | $400M |
What decides it from here
Varonis reports third-quarter results after the close on November 3, with no earnings call because of the pending deal 1. The proxy for the special meeting has not been filed yet 5. Three readings set the spread from here: the Q3 print, the litigation disclosures in the proxy, and whether Cyera's talks close anywhere near $20 billion 8. If the category re-rates, the $49.75 print ages badly and the litigants gain leverage 8. If the Cyera talks die, the deal closes as signed and arbs keep their 3% 8.
Get Deals by email, free
The acquisitions, rounds and contracts that move AI money. In our daily email, every weekday.