Baker Hughes' 56.7% HMH stake is worth $266 million, more than the float; Akastor holds an identical stake
The November 16 13G is the first since HMH's IPO lock-up expired, and it shows an exchangeable stake worth roughly $266 million against a float worth about $203 million, with Akastor holding an identical right. Whether either parent converts or takes cash decides whose money moves.
 Vincent Jiangthree-minute read
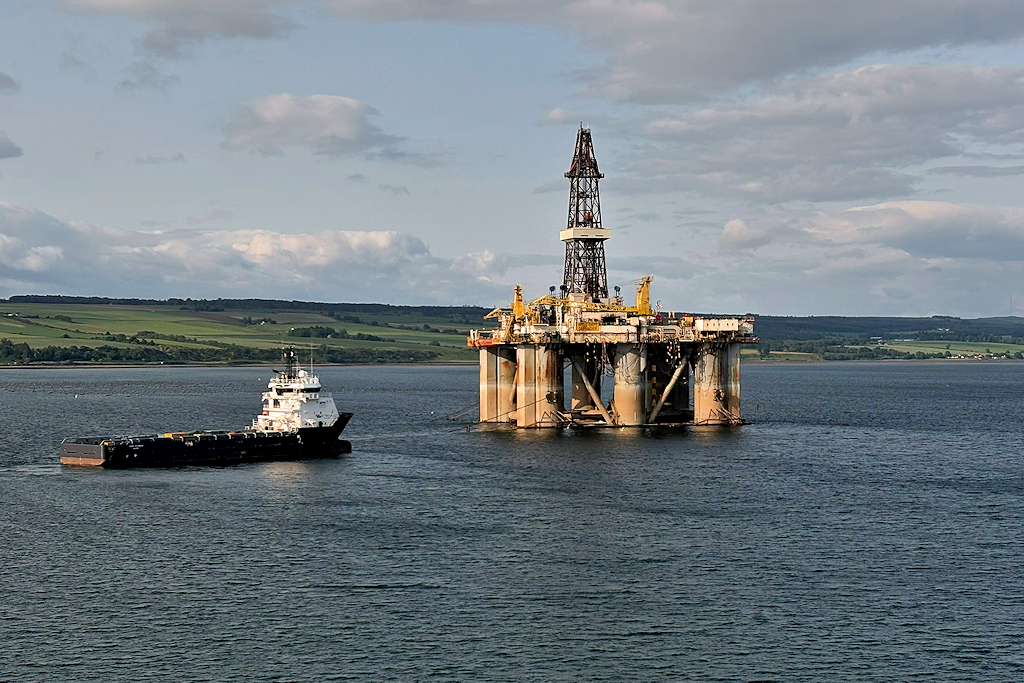
Baker Hughes−0.49% — Baker Hughes, down 0.49 percent today filed a Schedule 13G on November 16, 2026, telling the market something nobody had printed before: Baker Hughes Holdings LLC can turn 15,945,826 shares of HMH Holding Inc 1. Class A common stock into a tradeable stake, 56.7% of the class, whenever it wants 1. HMH is a Houston-based global provider of offshore and onshore drilling equipment and services (NASDAQ: HMH), and it completed its IPO on April 2, 2026 3. Its whole public float is 12,201,501 shares as of October 31, 2026, per its own Form 10-Q filed November 4, 2026 1.
The stake is worth real money against a small market. HMH last traded near $16.66 in early November, with six analysts averaging a $28.33 target 5. At $16.66, Baker Hughes' exchangeable position pencils out to roughly $266 million, larger than the entire float's market value of about $203 million 5. Converted, those bundles would more than double the public supply against a float that size.
Baker Hughes' exchangeable HMH stake exceeds the entire public float
Each parent can exchange more shares than HMH's whole public float
Data
| Value | |
|---|---|
| Class A float (Oct 31) | 12,201,501 |
| Baker Hughes exchangeable | 15,945,826 |
| Akastor exchangeable | 15,945,826 |
The cash clause is the whole negotiation
The mechanics come straight from the filings. The Exchange Agreement, dated April 2, 2026, lets Baker Hughes swap each bundle of HMH Class B shares and non-voting B.V. shares for Class A stock, and those rights became exercisable when HMH's IPO lock-up ended September 27, 2026, with no expiry 1. The clause that matters most is one sentence: upon mutual agreement of HMH and Baker Hughes, the bundles may be exchanged for cash in lieu of stock 1.
Cash has precedent. HMH's 10-Q describes "a $12.9 million purchase of HMH Inc. and HMH B.V. shares as part of the greenshoe exercise" in its financing cash flows, and its cash flow statement books the same $12.9 million as a "Redemption under exchange agreement with Principal Stockholders" 3. The 10-Q also names the other parent: Akastor ASA, the Norwegian industrial holding, whose subsidiaries hold an identical 15,945,826 exchangeable shares, so potential supply against the 12.2 million-share float is roughly 31.9 million shares from two directions 3.
The business under the paper is under strain
Q3 2026 revenue was $171.1 million, down 21% year over year, with product revenue down 69% on Middle East conflict delays; net income attributable to HMH was $5.0 million and free cash flow was negative $11.6 million 4. Orders rose 12% year over year to $191 million, a book-to-bill of 1.12x, so demand is holding even as revenue lags 4.
HMH's third-quarter orders outran revenue while free cash flow went negative
Data
| Q3 2026 ($M) | |
|---|---|
| Revenue | $171.1M |
| Orders | $191M |
| Net income | $5M |
| Free cash flow | -$11.6M |
Baker Hughes itself is a $49 stock moving on its own calendar 2. Its chief accounting officer, Rebecca L Charlton, sold 555 BKR shares at $49.06 on November 13, 2026, under a 10b5-1 plan adopted February 24, 2026, holding 16,367 shares after 2. Routine, but it prices the parent while its HMH position sits unmarked.
Watch two things from here: whether Baker Hughes, or Akastor, files a 13D or a sale notice on HMH, and whether HMH's next cash statement shows another redemption line 1. A parent that takes stock floods a $200 million float; a parent that takes cash needs HMH's board to agree on a price, and that negotiation has no deadline, because the right never expires 1. Minority holders face the supply risk of a conversion and hold no vote on any cash-out price.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.
Reader comments
0 comments