Freeport-McMoRan's Indonesian unit taps bond investors; the debt lands on the parent as copper slides
The notes, rated Baa3/BBB, land on Freeport-McMoRan's consolidated balance sheet, so bond buyers fund the Grasberg rebuild while the equity keeps its payout room and carries the leverage risk. Copper's five-week slide makes the pricing a live test of the AI-copper thesis.
 Richard Tangtwo-minute read
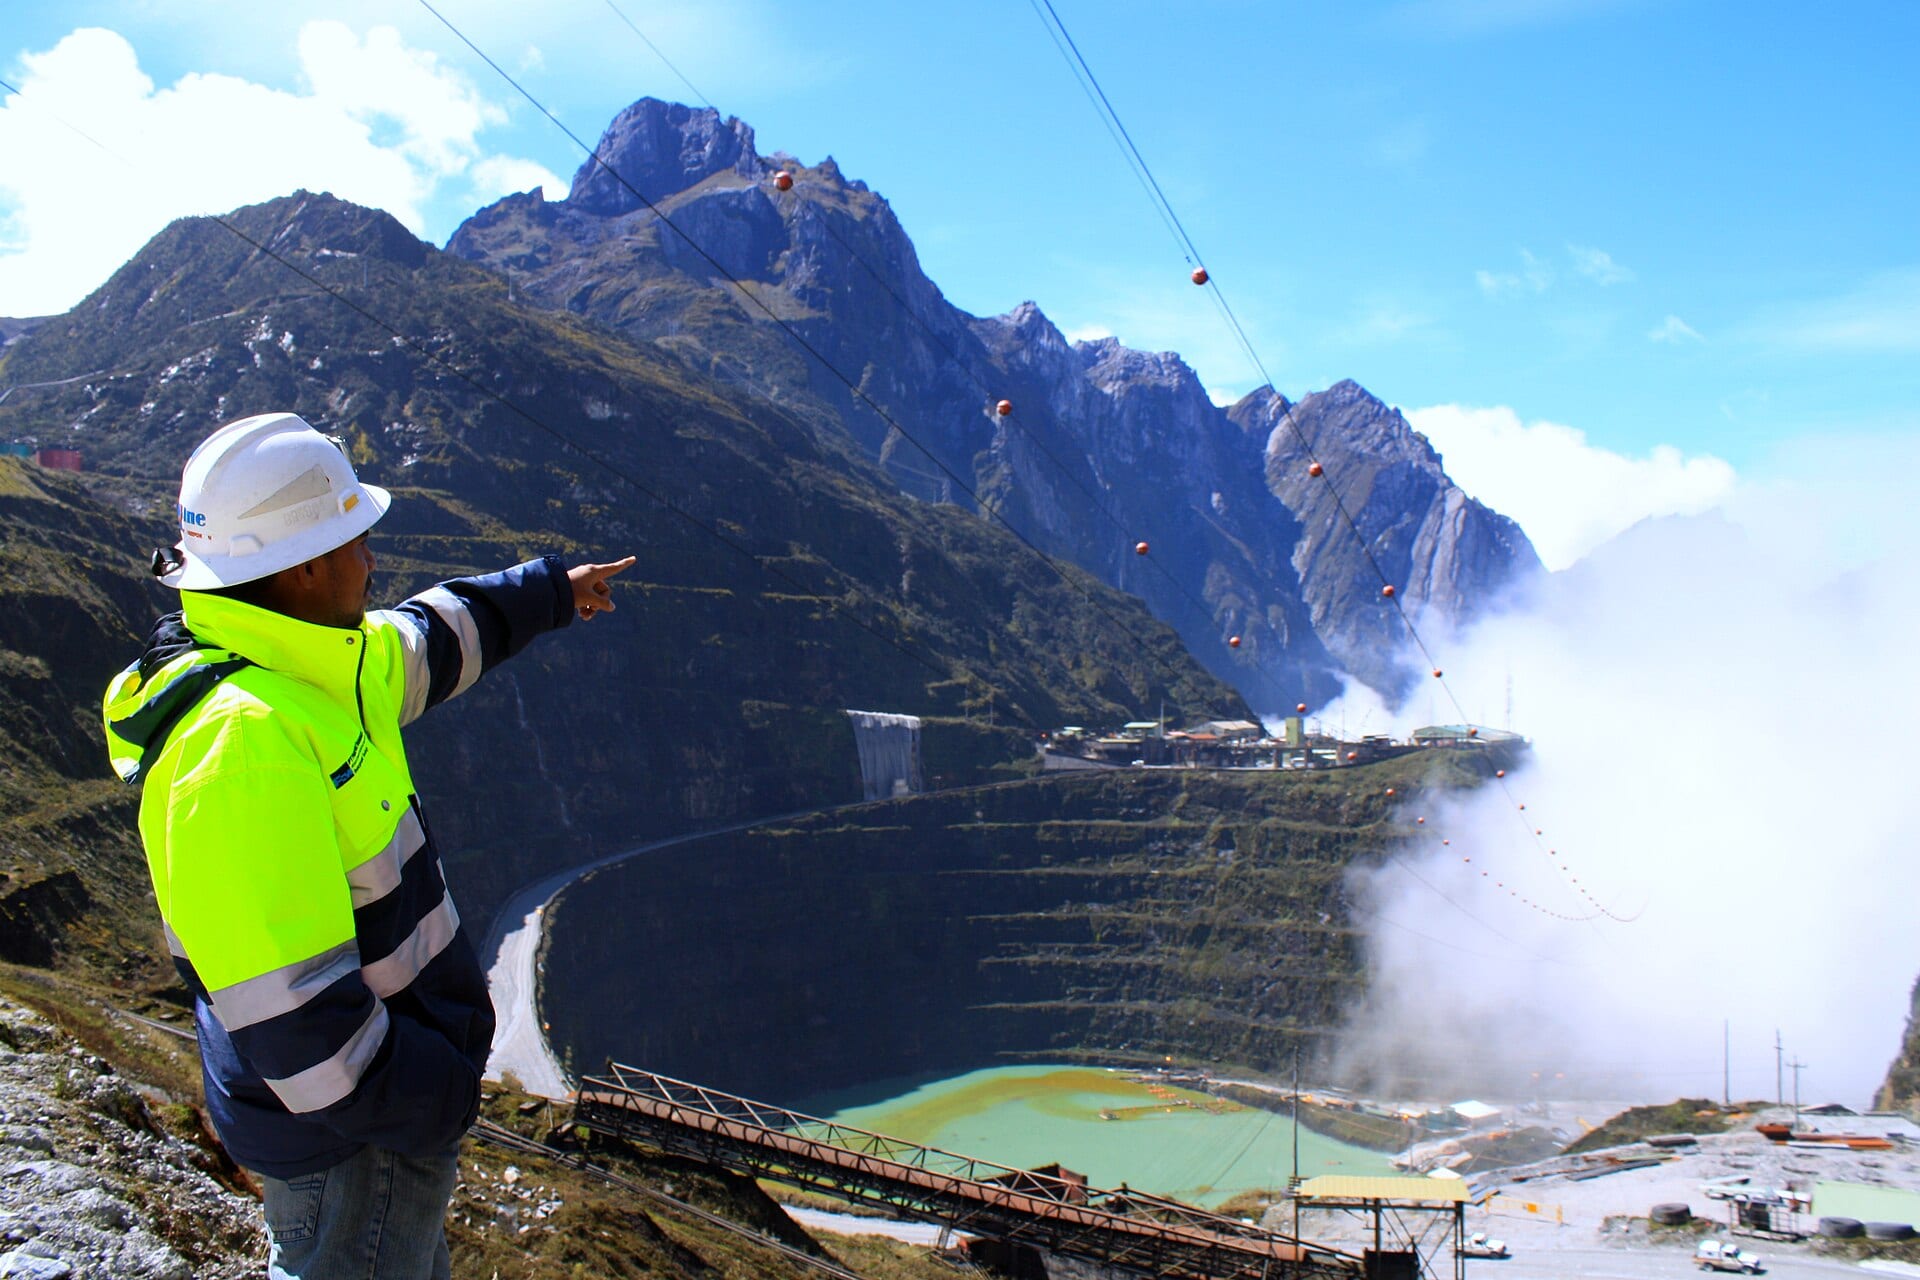
PT Freeport Indonesia, the 48.76 percent Freeport-McMoRan−6.48% — Freeport-McMoRan, down 6.48 percent today subsidiary that runs the Grasberg copper and gold district, is tapping bond investors for dollar senior notes to refinance debt and fund general corporate purposes 12. Freeport's own 8-K adds the fact the wires left out: the notes, though issued by the Indonesian subsidiary, land on FCX's consolidated balance sheet 1. That matters because PTFI has been carrying the cost of the 2025 Grasberg mud rush on its own books, and the equity is about to feel the follow-on 1.
The rebuild is real but unfinished
Grasberg mills ran at 67 percent of capacity in the third quarter, and management targets 80 percent by mid-2027 and near-full rates by year-end 3. Copper sales are meant to rise from about 3.0 billion pounds this year past 4.0 billion in 2028 3.
Copper sales guidance climbs as Grasberg returns to full rates
Freeport's recovery thesis rests on sales growing more than a third from 2026 to 2028
- Copper sales guidance
- Estimate
Data
| Copper sales guidance | |
|---|---|
| 2026 | 3B lbs |
| 2027 (estimate) | 3.7B lbs |
| 2028 (estimate) | 4B lbs |
Nine months of idle-facility and recovery costs, $934 million so far, get absorbed into unit costs rather than vanish 3. Add the $4.5 billion Bagdad expansion approved on November 4, which pushes 2027 capex to $5.2 billion, and you have a company spending into a volume recovery the copper market has stopped believing in 34.
Capex runs near $1 billion a quarter; the 2027 plan needs about $1.3 billion
- Operating cash flow
- Capital spending
Data
| Operating cash flow | Capital spending | |
|---|---|---|
| Q4 '24 | $1.44B | $1.13B |
| Q1 '25 | $1.06B | $1.06B |
| Q2 '25 | $2.2B | $1.13B |
| Q3 '25 | $1.66B | $0.91B |
| Q4 '25 | $0.69B | $0.88B |
| Q1 '26 | $1.5B | $0.84B |
| Q2 '26 | $2.05B | $0.96B |
| Q3 '26 | $1.98B | $1.01B |
The credit market gets the vote this week
LME copper just logged its fifth straight weekly loss, the worst stretch in nearly two years, with Goldman−2.57% — Goldman, down 2.57 percent today trimming its 2027 forecast on softer AI-related positioning 5. The chain here runs straight through your portfolio: data centers pull copper, copper pulls Freeport's recovery thesis, and the bond pricing is the credit market's vote on whether that recovery happens on schedule 125.
Watch the coupon when the notes price. A tight print says lenders believe the Grasberg ramp; a wide one says the AI-copper trade is cracking faster than management admits 125.
For shareholders, the structure is the point: bond buyers fund the rebuild while parent cash stays free, and the leverage risk sits with the equity 13. Start from the pricing, not the press release.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.
Reader comments
0 comments