Honeywell's 21.3% segment margin vs Emerson's 29.1%: 8 points apart on paper, 0.1 point on one line
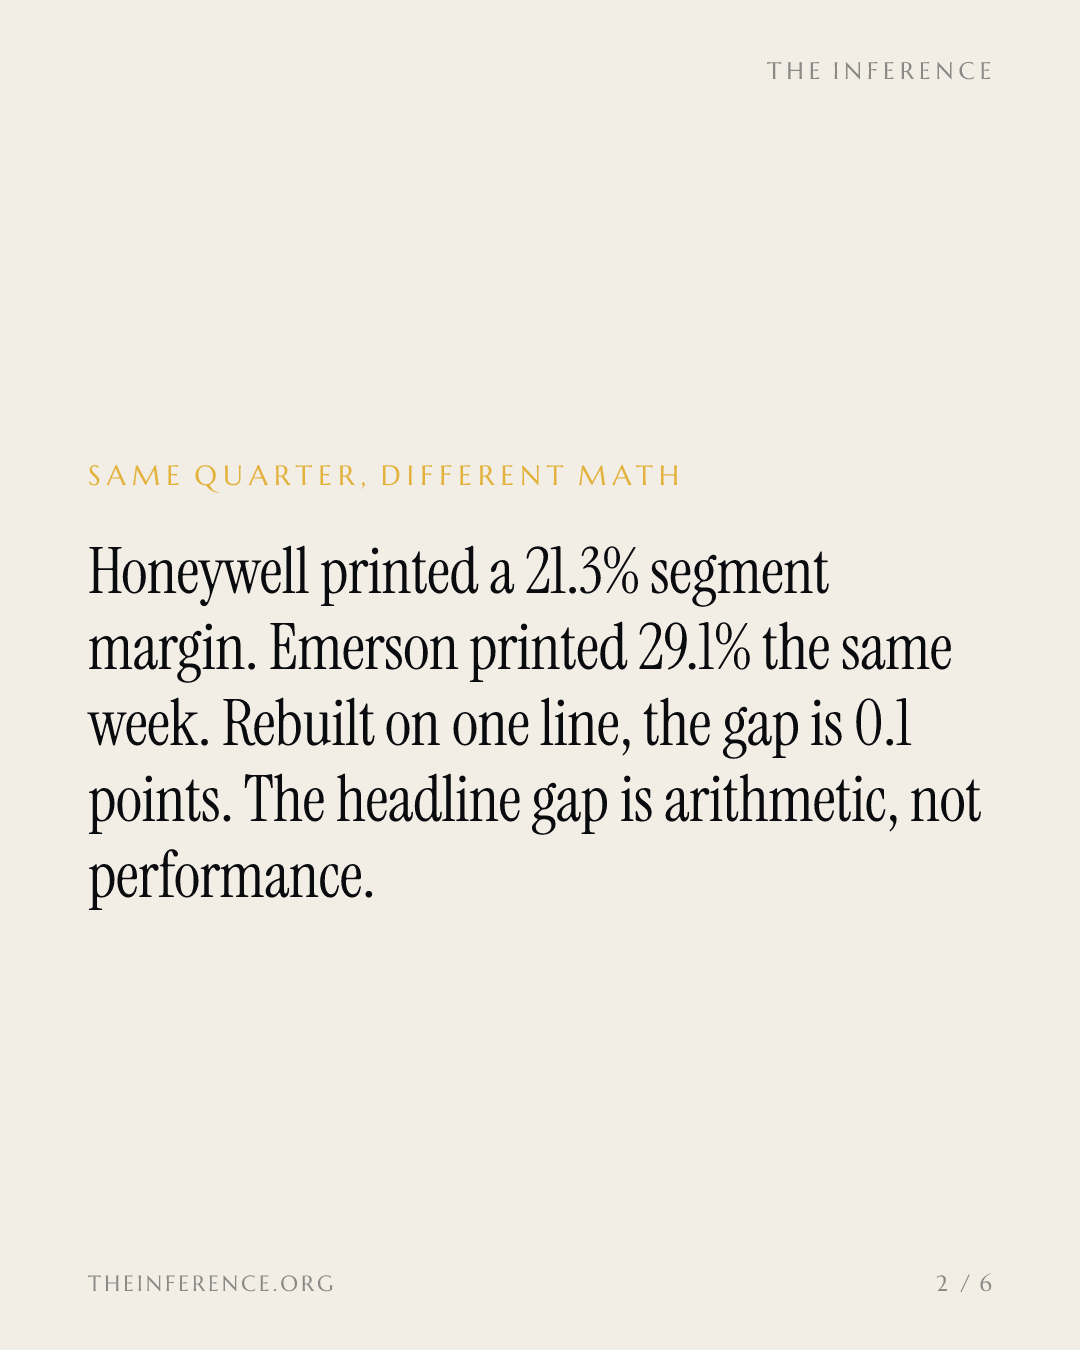
Honeywell's 21.3% segment margin and Emerson's 29.1% look eight points apart, but put both on the same line and the gap is 0.1 points. The real question for investors is Honeywell's $235 million of add-backs and a forward margin guide that ships without a reconciliation.
 Vincent Jiangtwo-minute read
On November 17 Vimal Kapur, chairman and chief executive of Honeywell Technologies−2.09% — Honeywell Technologies, down 2.09 percent as of its last quote, takes the stage at an RBC investor conference 12. The number waiting for him is the full-year 2026 segment-margin guide of about 20.5%, raised with third-quarter results on October 22 alongside an adjusted EPS target of $8.40 to $8.45 12. It is stated on a definition the earnings release never reconciles to the 14.8% operating margin it printed in the same document 1.
The eight-point gap is arithmetic, not performance
The quarter ended September 30, 2026, shows Honeywell with segment profit of $1,062 million on segment sales of $4,994 million, a 21.3% margin 1. Emerson−3.44% — Emerson, down 3.44 percent as of its last quote, which reported the same calendar day on November 4, printed an adjusted segment EBITA margin of 29.1% on $1,511 million of $5,201 million in sales 1. Eight points looks like a verdict.
It is not. Honeywell's line carries $101 million of corporate cost inside it 1. Emerson's sits above corporate expense and adds back amortization and restructuring. Rebuild both on one line and the gap dissolves: Honeywell's three segment profits sum to $1,163 million, 23.3% of sales; Emerson's three GAAP segment earnings sum to $1,207 million, 23.2% 1. Honeywell's definition is the more conservative of the two.
The 21.3% vs 29.1% gap is mostly definition, not performance
On matching definitions the eight-point gap collapses to 0.1 points
Data
| Value | |
|---|---|
| HON headline | 21.3% |
| EMR headline | 29.1% |
| HON pre-corporate | 23.3% |
| EMR GAAP | 23.2% |
The $235 million of add-backs is the number to read
Getting from Honeywell's $740 million of operating income to $1,062 million of segment profit means adding back $322 million, of which $235 million is stock compensation and acquisition amortization, 4.7 of the 6.5 margin points between the two lines 1. Operating cash flow from continuing operations fell 74% to $607 million while adjusted free cash flow rose 15% to $688 million 2. Nine-month pretax income of $7,474 million is dominated by a $6,629 million gain on deconsolidation 1.
Building Automation carries the growth, Process Automation the drag
The growth story is real but priced elsewhere: Building Automation margin of 27.0% 1, AI building platforms launched at Accelerate 2026 3, and a low-carbon fuels partnership with Keppel announced November 16 45. Process Automation margin fell 210 basis points to 22.2% on project mix and dilution from the Johnson Matthey Catalyst Technologies deal, which lands again in the fourth quarter 1. At $222.46 on November 13 1, the call is to read Note 18, not to chase the headline gap.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.
Reader comments
0 comments