Bending Spoons raised Evernote's top plan 92% to $250 in the week it took $1.5 billion of notes to market
Bending Spoons lifted Evernote's top annual tier from $130 to $250, a 92 percent rise, in the same week it took $1.5 billion of senior secured notes to market through subsidiaries it will not guarantee. Repayment rides on subscribers who stay, and only the company reports how many do.
 Richard Tang · 3 min read
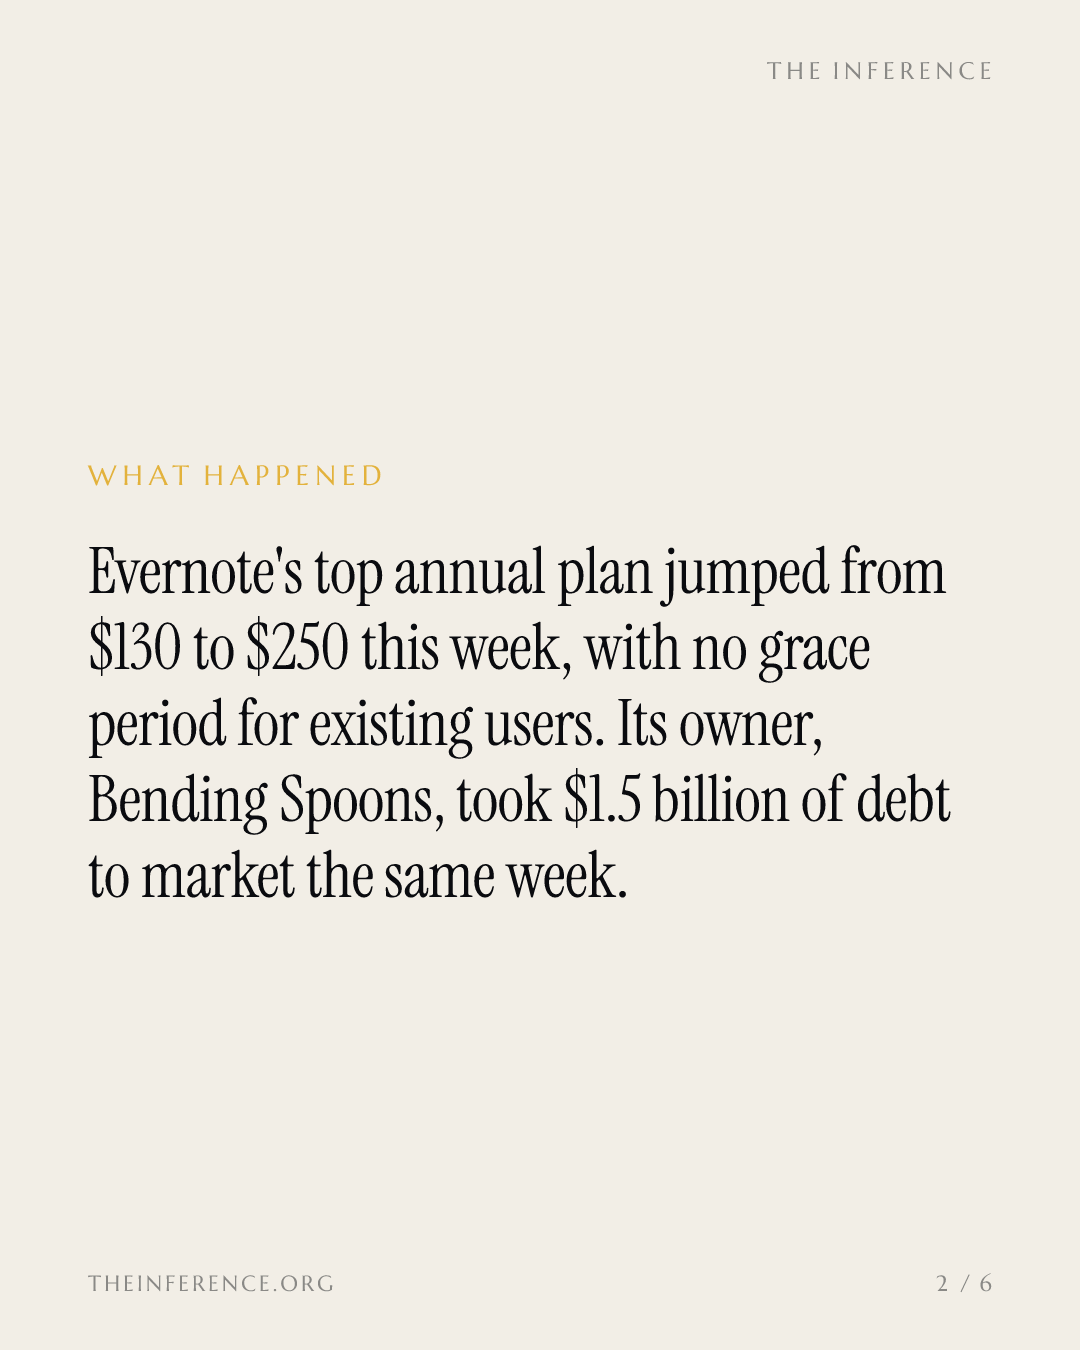
Evernote$200M — Evernote, private, latest valuation $200M, the note-taking app, raised its top annual plan from $130 to $250, with no grace period announced for existing subscribers 17. The 92 percent rise became public in the same week the app's owner, the Milan serial acquirer Bending Spoons+0.37% — Bending Spoons, up 0.37 percent today, took $1.5 billion of senior secured notes to market 12.
Senior secured notes are debt backed by the issuers' assets and first in line for repayment; here the issuers are two subsidiaries, and the parent says it will not guarantee their debt 2. The pricing and the borrowing are one plan: the notes will be serviced by subscription revenue from acquired apps, and Evernote is the cleanest public record of how that revenue is made.
Tenure is the asset, and the filing says so
Bending Spoons bought Evernote in 2023 for what a June securities filing calls its 200 million accounts and "robust subscriber retention": customers with an average tenure of 7.2 years, thousands of stored notes and personalized workflows 1. Those figures describe switching cost. A customer with years of notes and a workflow built around them is expensive to move, and Bending Spoons paid for that stickiness.
Evernote's top annual tier has gone from $70 to $250 under Bending Spoons
Data
| Top annual tier | |
|---|---|
| 2023, at acquisition | $70 |
| After 2023 hike | $130 |
| October 2026 | $250 |
Half the conversions now start with hitting a limit
Since the takeover, Bending Spoons has run more than 200 pricing and feature experiments 1. Revenue per monthly active user is now two and a half times its 2022 level, and an app that had been unprofitable for years was reportedly at record profitability by late 2024 1. The most effective change was friction: half of all Evernote conversions in 2025 came from users hitting a usage limit, after previously paywalled features were opened up with caps attached 1.
Registrations, which shrank for three straight years before the deal, then grew in 2024 and 2025 1. Every number in that defense is published by the company itself, and no independent churn figure exists for the $250 tier 17.
Evernote registrations returned to growth once the price ladder started
Data
| New registrations, year-over-year change | |
|---|---|
| 2021 | -23 |
| 2022 | -23 |
| 2023 | -20 |
| 2024 | 29 |
| 2025 | 20 |
Noteholders and Berkshire are betting users stay
Bending Spoons listed on Nasdaq in July. Berkshire Hathaway+0.34% — Berkshire Hathaway, up 0.34 percent today put $600 million into the listing and another $330 million two weeks ago, lifting it to a 4 percent stake 3.
The portfolio runs from AOL$1.4B — AOL, private, latest valuation $1.4B, Vimeo$1.38B — Vimeo, private, latest valuation $1.38B and WeTransfer to the AI photo app Remini 4. The purchase of Miro$1.79B — Miro, private, latest valuation $1.79B, the online whiteboard company, closed the day before the notes were announced, and the proceeds are earmarked for more deals, which chief executive Luca Ferrari calls the source of the overwhelming majority of the company's growth 245. Noteholders, Berkshire and the equity all sit on the same bet. The market's first read was skeptical: BSP shares fell before the bell when the offering was announced 6.
The moat being priced is the one AI erodes
Bending Spoons describes itself as improving acquired products by "leveraging Artificial Intelligence and data technologies" 4. The moat it is monetizing is accumulated personal context, and that is the asset AI makes portable: if an assistant can search an archive, summarize it and rebuild the workflow in a rival app, tenure stops protecting the price.
That erosion is a projection, not a measured result, and it is the reason the extraction window may be shorter than the notes' 2032 maturity suggests 2. Two disclosures will test the plan. The notes' final coupon and terms are still to be set at pricing 2, and Bending Spoons' next filing will carry the first registration and retention figures covering the $250 tier 1. Both come from the company whose plan depends on them, and until they arrive, whoever renews at $250 is paying the coupon 21.
Get Applications by email, free
How AI is changing the software people and companies use. In our daily email, every weekday.