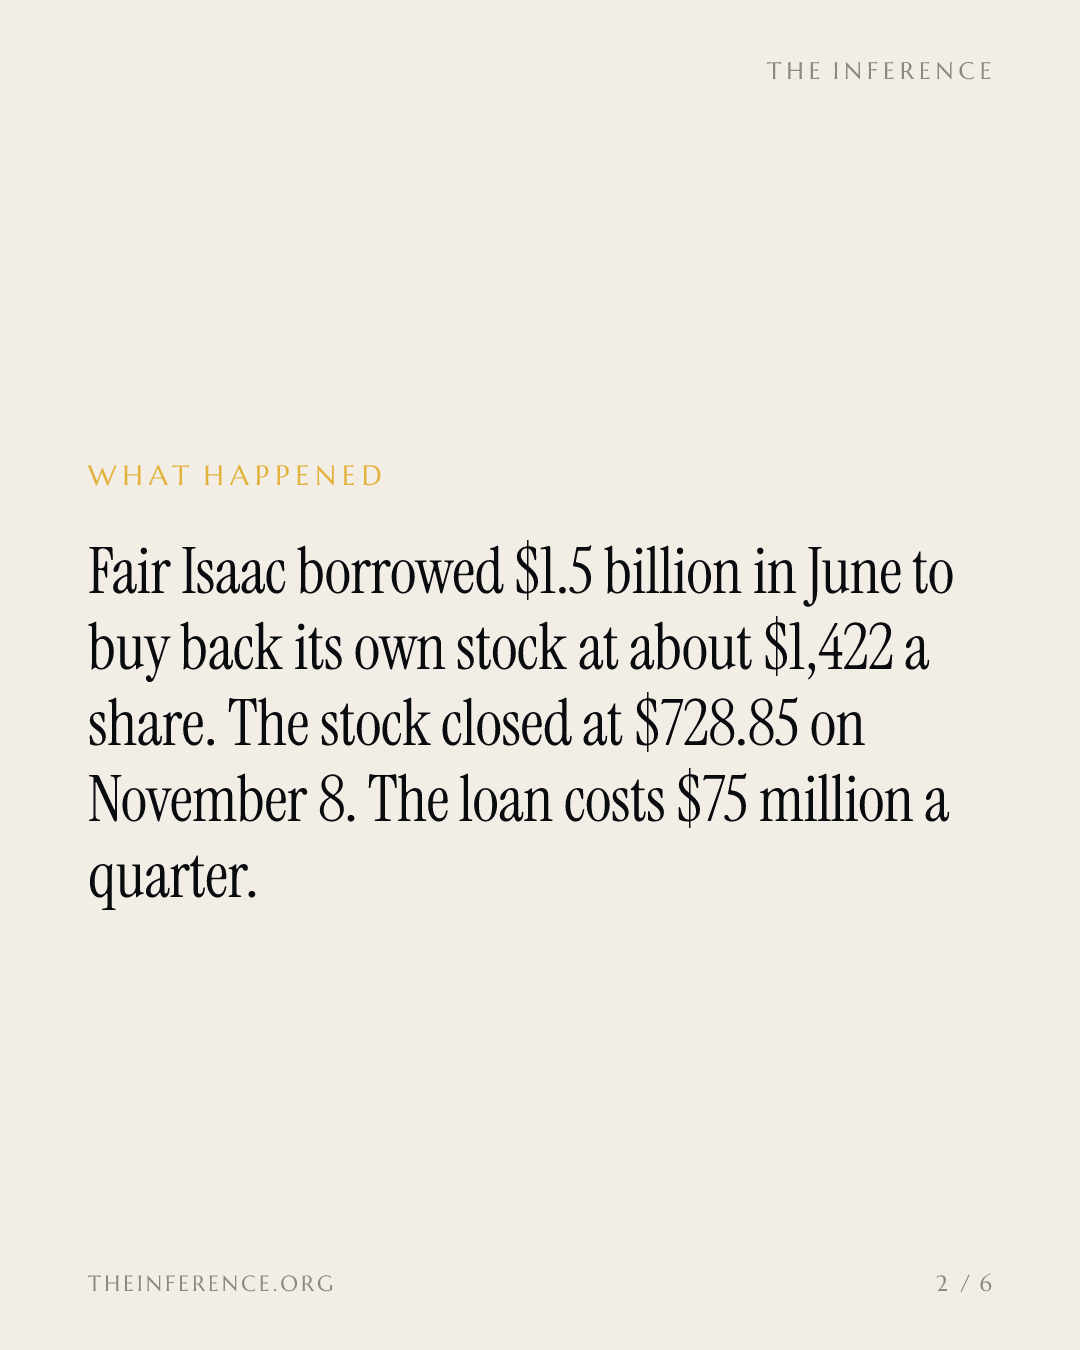
FICO borrowed $1.5 billion for a buyback at about $1,422 a share; the stock closed at $728.85
A June 8 filing shows how the buyback was funded: a $1.5 billion floating-rate term loan that now amortizes $75 million a quarter, against a stock that closed at $728.85 on November 8.
 Vincent Jiangthree-minute read
The loan that did the buying
Fair Isaac−1.21% — Fair Isaac, down 1.21 percent today borrowed the full $1.5 billion of a new unsecured term loan on June 5, maturing May 15, 2028, and priced at SOFR plus 1.50% to 2.25% 1. Three days later it paid the entire amount to Wells Fargo+0.08% — Wells Fargo, up 0.08 percent today Securities under an accelerated share repurchase, taking initial delivery of about 1,055,100 shares, roughly $1,422 each; the final count settles on the stock's average price over the deal's term 1. About $500 million stayed unspent under the new $2.0 billion authorization 1. FICO closed at $728.85 on November 8, 49% below that first tranche 2.
Borrowed at the old monopoly prices
On September 29, Federal Housing Finance Agency Director Bill Pulte put VantageScore, the score owned jointly by Equifax−0.32% — Equifax, down 0.32 percent today, Experian and TransUnion−0.92% — TransUnion, down 0.92 percent today, on the same mortgage pricing grid as Classic FICO 34. The stock fell 26.5%, its worst day since 1989 3. Rocket Mortgage began defaulting eligible loans to VantageScore 4.0, which TransUnion sells at 99 cents through December 2028 against FICO's $10 pull 34.
Frozen at $10 with $3.05 billion already spent
Fair Isaac froze the $10 wholesale price for 2027 on October 23 and lost another 16% 5. The balance sheet was built at the old prices: total debt of $5.26 billion at September 30 versus $3.06 billion a year earlier, book equity of minus $3.87 billion, and $3.05 billion of stock retired in fiscal 2026, about a tenth of the company, against $1.03 billion of free cash flow 6.
March had already added $1.0 billion of 6.25% notes due 2034 to retire $400 million of 5.25% paper due 2026: longer maturity, higher coupon 7. The term loan now amortizes the cost of a monopoly Fair Isaac no longer has.
Debt climbed to $5.28 billion while cash sat at $218 million
- Total debt
- Cash
Data
| Total debt | Cash | |
|---|---|---|
| Dec 2023 | $1.97B | $0.16B |
| Mar 2024 | $2.06B | $0.14B |
| Jun 2024 | $2.14B | $0.16B |
| Sep 2024 | $2.23B | $0.15B |
| Dec 2024 | $2.44B | $0.18B |
| Mar 2025 | $2.55B | $0.15B |
| Jun 2025 | $2.8B | $0.19B |
| Sep 2025 | $3.08B | $0.13B |
| Dec 2025 | $3.22B | $0.16B |
| Mar 2026 | $3.66B | $0.22B |
| Jun 2026 | $5.6B | $0.25B |
| Sep 2026 | $5.28B | $0.22B |
The margin print leaves out two charges
The quarter looked strong: revenue up 27% to $657 million, Scores up 33% on a higher price per mortgage score 6. But the 61% non-GAAP operating margin excludes a $65 million antitrust settlement accrual and a $27 million charge for cutting about 15% of the workforce; on GAAP terms the operating margin was 40.6% 684.
The September quarter's 40.6% margin gave back the year's gains
Data
| GAAP operating margin | |
|---|---|
| Q4 '23 | 39.6% |
| Q1 '24 | 44.9% |
| Q2 '24 | 42.5% |
| Q3 '24 | 43.4% |
| Q4 '24 | 40.8% |
| Q1 '25 | 49.3% |
| Q2 '25 | 48.9% |
| Q3 '25 | 46% |
| Q4 '25 | 45.7% |
| Q1 '26 | 58.2% |
| Q2 '26 | 53.8% |
| Q3 '26 | 40.6% |
Chief Financial Officer Steven Weber put net leverage at 3.29 times EBITDA and called the buyback pause temporary 8. The offsets are real: platform recurring revenue rose 72% to $453 million, direct licenses cover about 73% of mortgage reseller volume, and the FHA accepts Score 10T starting January 2027 8.
December reprices both sides of the ledger
All 101 economists in a November 10 poll expect a quarter-point Fed hike in December 9. The loan floats: after the September 30 payment it stands at $1.425 billion, and a quarter point is about $3.6 million of interest a year 6. The same move squeezes the originations FICO scores, a risk the company itself cited in withholding fiscal 2027 guidance 6.
Management will not say whether average 2027 pricing lands above or below 2026 8. RBC Capital Markets' November 11 downgrade to Sector Perform, target $770, says less than the calendar 10: whether the last $500 million is spent before the bespoke 2027 contracts take effect, with the amortization stepping up to $112.5 million a quarter after June 30 1.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.