Flex's Axiom spinoff targets $37 billion revenue by 2030, marked at $37.5 billion by General Catalyst and Koch
The November 10 filing puts the first standalone numbers under the $37.5 billion enterprise value General Catalyst and Koch agreed to in October: about $9.7 billion of revenue this year, negative free cash flow, and a plan to double in 2027. Flex shareholders are being handed 88% to 94% of the company carrying that mark.
 Vincent Jiangthree-minute read
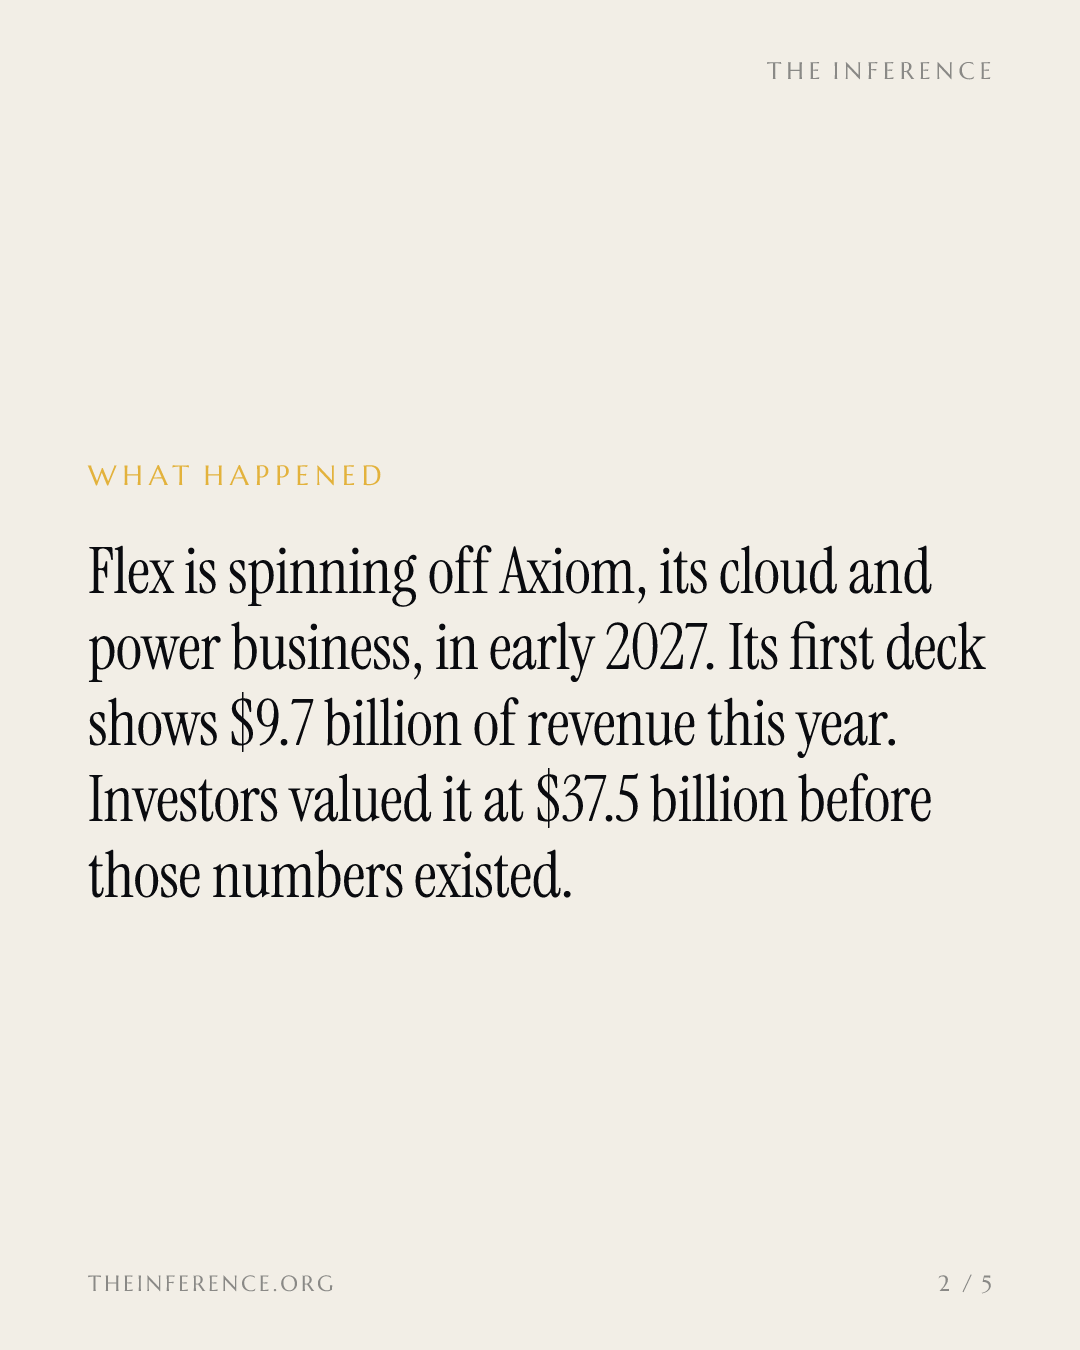
At an Innovation Day in Austin this morning, Axiom Solutions International, the cloud and power business Flex−2.46% — Flex, down 2.46 percent today is separating in the first quarter of 2027, gave its first standalone investor presentation, filed by Flex in an 8-K 1. The deck estimates about $9.7 billion of revenue for calendar 2026, an adjusted EBITDA margin around 11%, negative free cash flow and capital spending near 10% of sales 2.
The price was set before the numbers were
The outside mark came five weeks earlier, on October 2: General Catalyst and Koch Equity Development agreed to buy $2.0 billion of Series A convertible preferred, 200,000 shares at $10,000 each, an initial enterprise value of $37.5 billion 35. A day after the announcement, Flex's entire market capitalization was $43.1 billion 4.
Holders hand over 88% to 94% of Axiom
On November 2 shareholders voted 310,323,729 to 213,425 to distribute 88.0% to 94.0% of Axiom common stock, leaving Flex a 6% to 12% stake it plans to exchange for its own debt within 24 months 156.
The preferred ranks ahead of that common: 10% a year in cash until separation, roughly $200 million against the $1.1 billion or so of EBITDA implied by an 11% margin on $9.7 billion, then 6% cash or 7% paid in kind, plus a General Catalyst board seat 23. Conversion is capped at a $37.5 billion enterprise value, with a $30 billion floor 2.
The $37.5B mark equals a full year of Axiom's 2030 revenue target
The preferred's price sits at Axiom's 2030 revenue framework, not its $9.7B today
- Estimate
Data
| Value | Range | |
|---|---|---|
| CY26E revenue (estimate) | $9.7B | — |
| CY27 outlook (estimate) | $20.5B | $20–21B |
| CY30E framework (estimate) | $37B+ | — |
| Preferred deal EV | $37.5B | — |
The deck asks for a doubling, then another
Axiom's outlook is $20 to $21 billion of revenue in 2027, which it calls 95% secured through backlog and customer commitments including co-investment, and $37 billion-plus by 2030, with margins in the high teens and power margins in the high 20s against a 24% peer median for 2027 2. The mark is about four times this year's revenue, and roughly one full year of the 2030 target 2.
Two clocks run against the spin
The $4.4 billion EPC Power purchase closed October 14 on a $3.3 billion term loan and a $1.1 billion bridge, both maturing October 2027; the preferred, still unclosed, is earmarked to repay them 7. The agreement lets Flex call the money with five business days' notice, and nothing forces the call before the debt is due 5.
If the spin slips past December 31, 2027, holders can require redemption at 115% of stated value in cash or 125% in Flex shares, under a Flex guarantee 5. The market has already flinched once: shares fell 6.9% on October 13 as investors weighed the valuation against the unit's margins and capital spending 8. The Inference laid out the debt clock on October 14 and the stub math on November 2 8.
Watch the funding notice for the preferred, Axiom's first standalone quarter against the $20 to $21 billion year, and the spin date itself. The preferred is an option on 2030 that pays 10% to wait; the common being distributed is the same option without the coupon.
Get Deals by email, free
The acquisitions, rounds and contracts that move AI money. In our daily email, every weekday.