Honeywell Aerospace shareholders are funding the factory meant to replace its weakest suppliers
The spun-off engines and avionics maker beat estimates, raised guidance and declared its first dividend on October 28, and its stock still sold off the next morning. The market has begun pricing the two years and $500 million that stand between Honeywell Aerospace's orders and its ability to ship them.
 Richard Tang · 3 min read
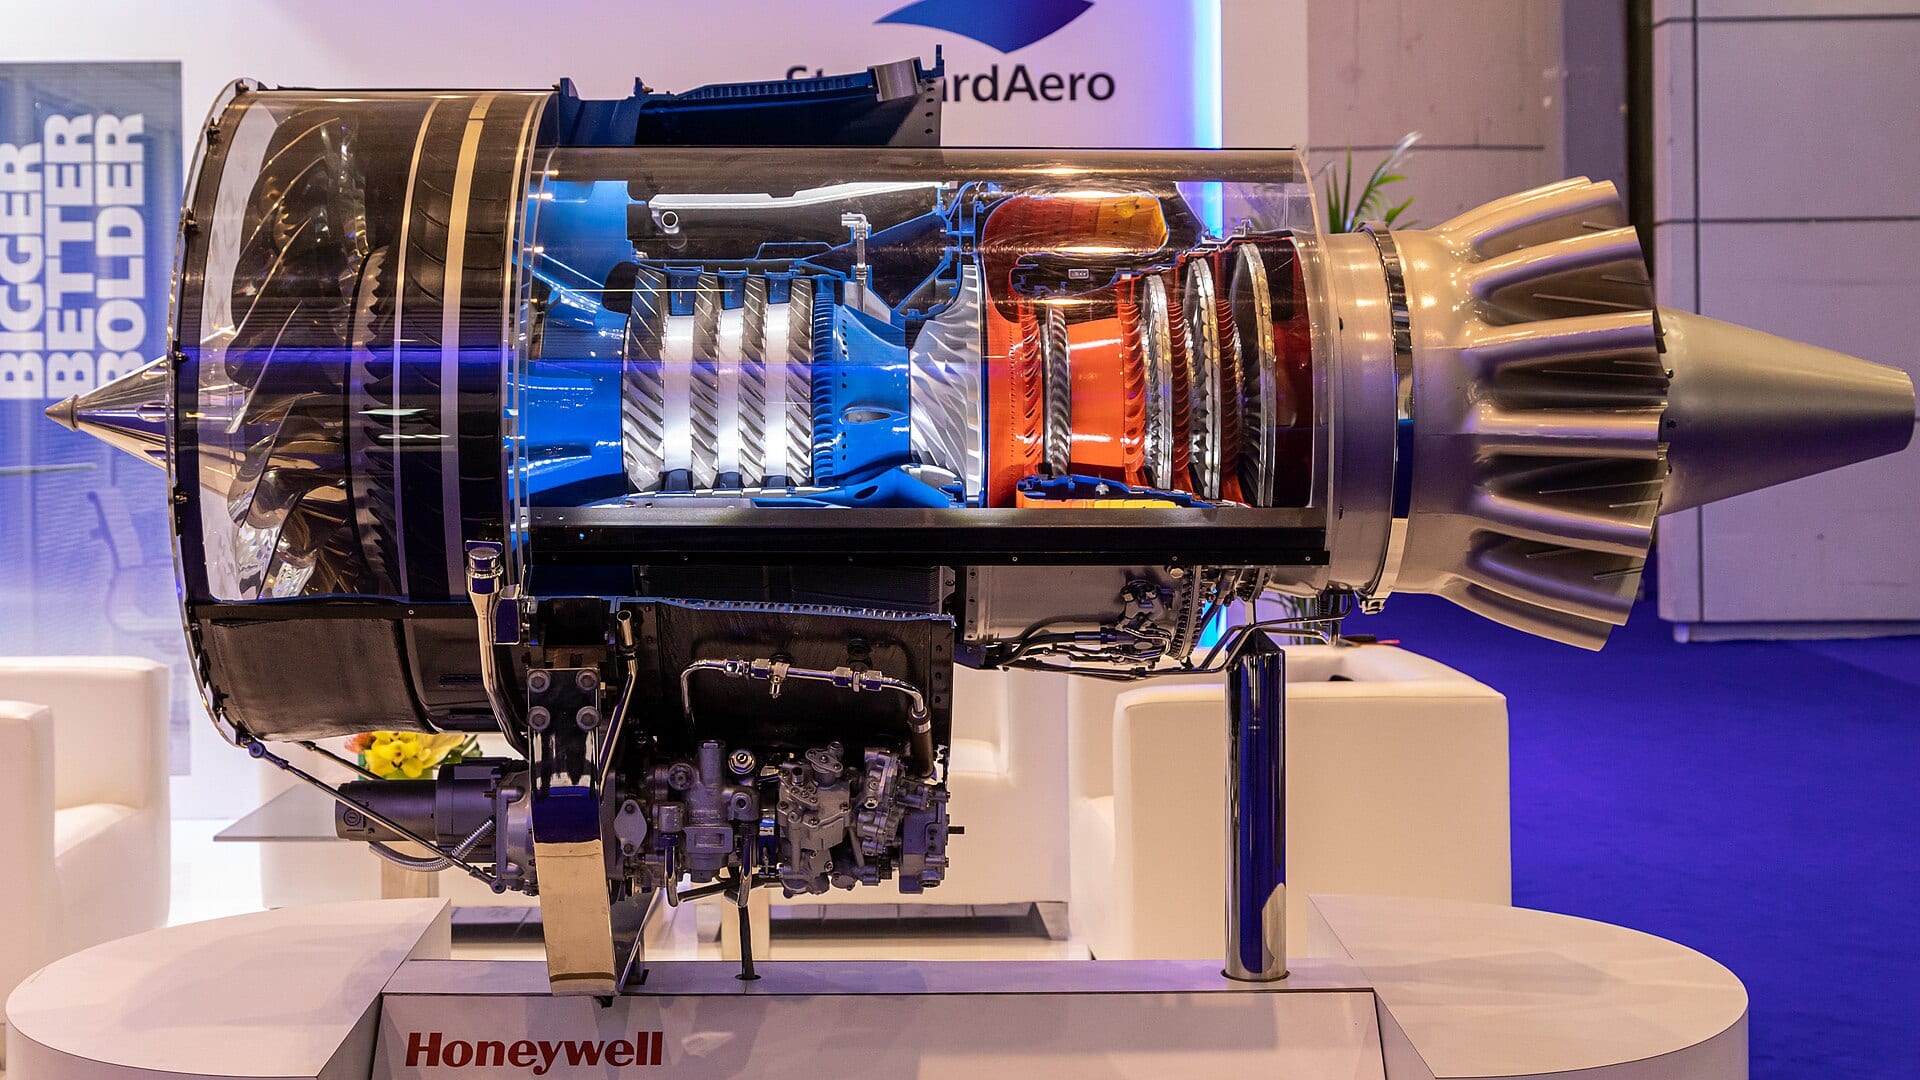
Honeywell Aerospace−3.47% — Honeywell Aerospace, down 3.47 percent today (Nasdaq: HONA), the engines and avionics maker spun off from Honeywell on June 29, beat third-quarter earnings estimates by 34 cents a share on October 28, raised its outlook and declared its first dividend 14. The shares had risen more than 5% into that close, with the results released after the bell 8, and then traded down 9.5% the next morning 4.
It was the second stumble: the stock fell 23% in a single day on August 6 after its first standalone report 5. Both drops price the same gap. Demand for aircraft parts is running ahead of the company's ability to manufacture them, and shareholders are being asked to fund the fix years before it ships anything.
Ten suppliers set the pace for the whole company
Backlog rose 12% from a year earlier to $19.3 billion, and orders grew in every end market 16. On the earnings call, chief executive Jim Currier said about ten suppliers, concentrated in complex machining, castings, forgings and bearings, cap output for the entire company 67. Commercial aftermarket, the most profitable part of an aerospace supplier's business, grew 2% because parts were unavailable, not because airlines stopped buying 1. The constraint is physical capacity, and it sits inside other companies.
The beat was thinner than the headline
Adjusted EBIT, the operating profit measure, rose 1% year over year 1. Inside that sat about $50 million of tariff refunds that management does not expect to repeat this quarter 17. The full-year profit range narrowed around an unchanged midpoint, and the raise to earnings guidance came from lower-than-expected costs below the operating line as a new public company 16. The engines and power systems segment earned less profit on higher sales, the signature of an aftermarket rationed by parts.
The quarter's profit decline sits in one segment
Data
| Value | |
|---|---|
| Electronic Solutions | 11% |
| Control Systems | 2% |
| Engines & Power Systems | -16% |
The factory is the admission
The new Tempe, Arizona plant opens in late 2028 and pulls complex machining, the most constrained step, inside the company, run with modular robotics, automated inspection and a digital thread 3. Alongside it, the board has approved insourcing projects covering more than $100 million of annual material spend 6.
Currier points to real supplier progress, including one machining shop that grew its workforce by more than a fifth and reached record weekly shipments in October 6. The capital plan still says the durable answer is owning the machines rather than asking suppliers to hire.
The $500 million factory is Honeywell Aerospace admitting the fix will not come from its suppliers.
Shareholders pay first, the payoff lands in 2028
Capital spending rises next year while the dividend pays out about a fifth of adjusted earnings, so today's shareholders of a $56 billion company underwrite the two-year gap between orders and capacity 268. That is the right use of the money: when a handful of outside shops throttle the backlog, buy the constraint and automate it.
The 2027 output ramp and the 2028 opening are projections, and the engine segment's margin will not recover until the parts flow. The reward for closing this gap belongs to whoever does the work, and for now the stock's buyers are the ones paying for it.
Get Robotics & Defense by email, free
Robots, self-driving vehicles, drones and AI in defense. In our daily email, every weekday.