Lam Research's China revenue was 35% of sales and is guided lower; ACM Research reports Nov. 5
Lam's China revenue hit 35% of sales, then its CFO guided that share significantly lower for December. ACM Research, the China-heavy toolmaker on NASDAQ, reports on November 5 and settles which face of Chinese demand is real.
 Vincent Jiang · 2 min read
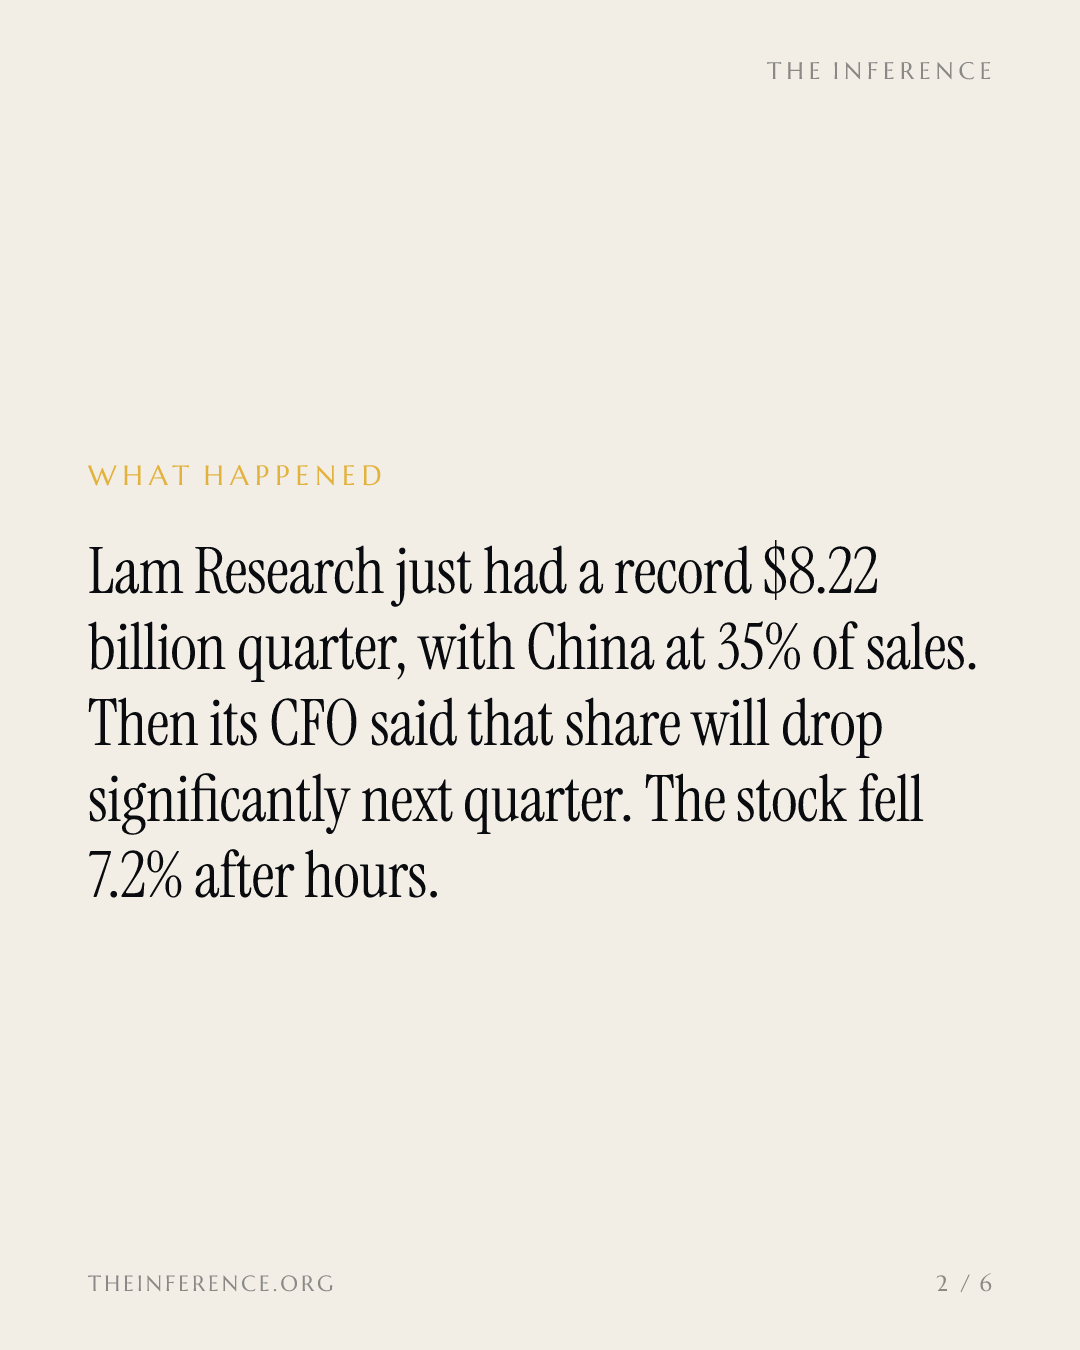
Lam Research−9.04% — Lam Research, down 9.04 percent today just showed both faces of China's chip-equipment market in one report. Its September quarter was a record on every line: $8.22 billion in revenue, up 54% year over year, with the AI memory buildout doing the lifting 15. China alone supplied 35% of that revenue, up from 26% the quarter before 15. Then chief financial officer Doug Bettinger told investors that share would drop significantly in the December quarter, driven mainly by Chinese chipmakers 1. The stock fell 7.2% after hours to $242 1.
The only listed way to test which face is real before year-end is ACM Research−6.93% — ACM Research, down 6.93 percent today (NASDAQ: ACMR), the Fremont-based cleaning and plating toolmaker whose revenue comes mostly from Mainland China. It reports third-quarter results before the US open on November 5, against consensus of $0.51 earnings per share, up 41.67% year over year, and $308.99 million in revenue, up 14.8% 24. The stock has already paid for the doubt: $54.96 at the close on October 20, down 22.92% in a month while its sector lost 2.28% 4.
The record says demand is not the problem yet
ACMR's June quarter brought in $292.92 million, up 36% year over year, with net income of $88.98 million, up 199% 6. The argument for keeping domestic orders while Lam is guided out is cost. On October 21 ACM announced a single-wafer hot sulfuric acid cleaning tool validated across more than 50 process layers at a foundry customer, recycling 70% of its sulfuric acid, roughly 400 tons per tool per year 3.
ACMR revenue grew 36% in the June quarter, before the China test
- Revenue ($M)
- Year-over-year growth (%)
Data
| Revenue ($M) | Year-over-year growth (%) | |
|---|---|---|
| Q3 '24 | 203.98 | 21 |
| Q4 '24 | 223.47 | 31.2 |
| Q1 '25 | 172.35 | 13.2 |
| Q2 '25 | 215.37 | 6.4 |
| Q3 '25 | 269.16 | 32 |
| Q4 '25 | 244.43 | 9.4 |
| Q1 '26 | 231.26 | 34.2 |
| Q2 '26 | 292.92 | 36 |
So the November 5 print answers one question: is Chinese equipment spend a durable domestic-substitution story, or a pull-forward that ends with Lam's December guide-down? Consensus already prices growth, not a slowdown. If ACMR lands near $308.99 million, China's fabs are still equipping with Chinese-listed tools. If it misses, Lam's call was the tell, not the exception. Two weeks settle it.
Consensus asks for another record quarter, not a China slowdown
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Q1 '26 | $231.26M |
| Q2 '26 | $292.92M |
| Q3 '26 (consensus) (estimate) | $308.99M |
What to watch
The EPS line carries the most information, not the top line: $0.51 is a 41.67% jump, so a miss means margin, not demand, broke first 4. The full-year bar is $2.05 per share on $1.17 billion, up 27.33% and 29.5% 4. Deep dive in below to learn more.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.