Lasertec, the only actinic EUV mask inspector supplier, raised order guidance and closed down 8.8%
The only supplier of actinic EUV mask inspectors reported first-quarter sales and profit down and raised its annual order guidance. Its shares still fell 13.8% in Friday's AI-spending selloff, deeper than toolmaker peers Advantest and Tokyo Electron.
 Vincent Jiang · 3 min read
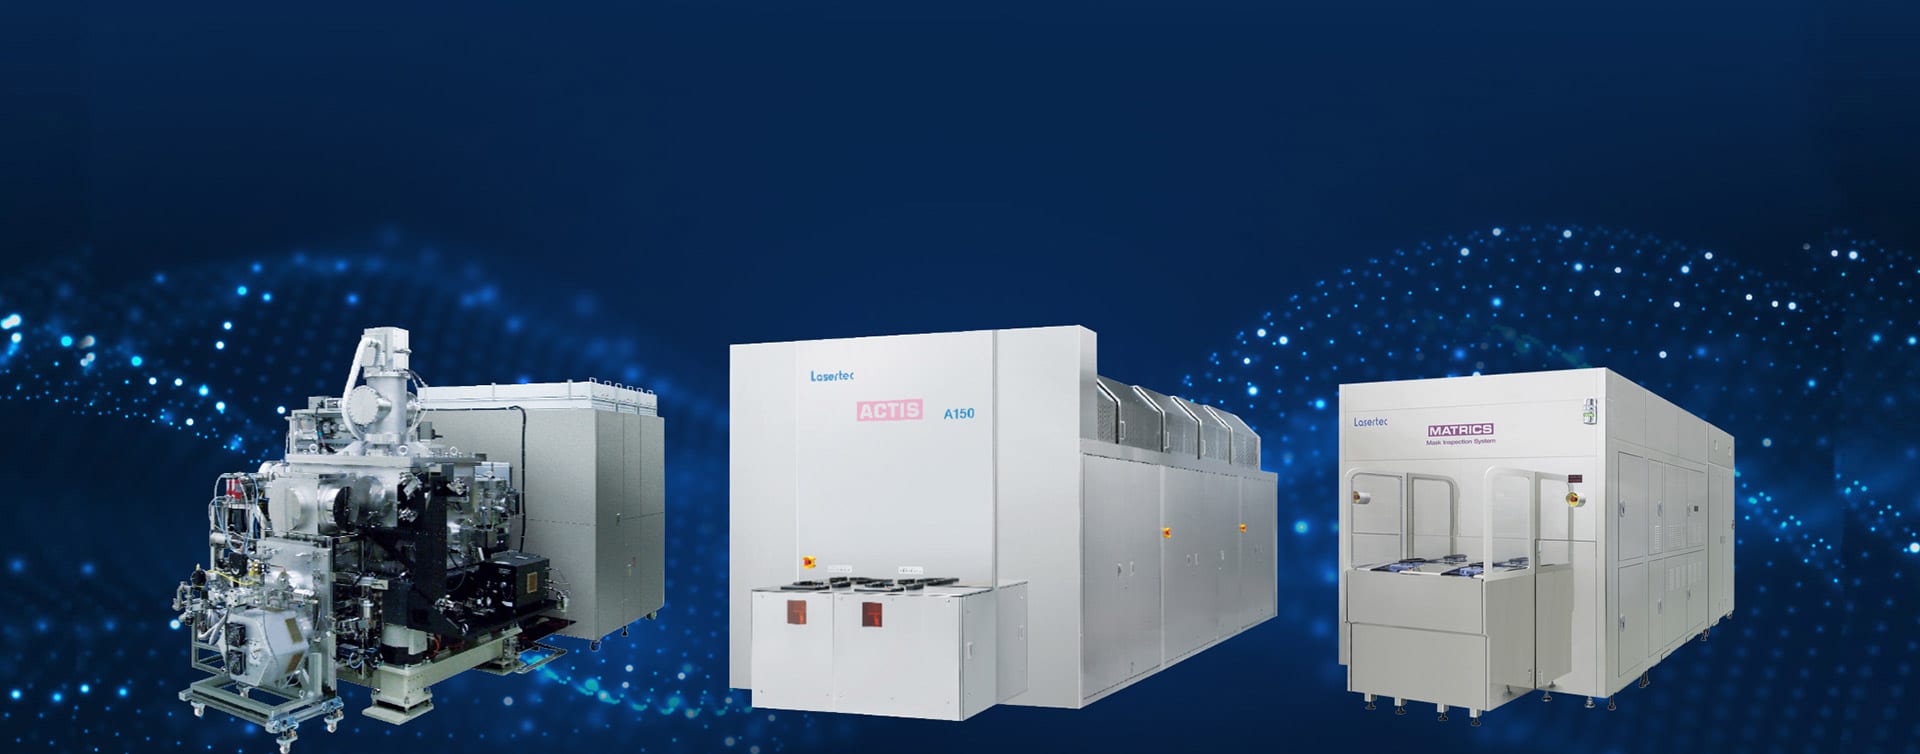
Lasertec−8.81% — Lasertec, down 8.81 percent today reported first-quarter results on Friday with sales and profit down year on year, yet it raised its annual order guidance despite the decline 12. The stock was marked down 13.8% in the Tokyo session and closed down 8.81% 13. In a Nikkei down as much as 3% on doubts about whether AI spending can pay for itself, the one company whose incoming orders had just been marked up got marked down 3.
The one order book that would show an AI slowdown first
Lasertec is the world's only supplier of actinic EUV mask inspectors, the machines that check the photomasks, the stencils from which leading-edge chips are printed. If the AI build-out were cooling, tool orders would slow first. In fiscal 2026, ended June, they did the opposite: revenue fell 8.3% to ¥230.49 billion while new orders rose 125.7% to ¥237.50 billion, leaving a ¥322.96 billion order backlog at year-end, with operating income of ¥105.26 billion on a 45.67% margin 5.
Lasertec booked more orders than revenue in fiscal 2026, and the backlog hit ¥322.96 billion
Data
| Value | |
|---|---|
| FY2026 revenue | ¥230.49bn |
| FY2026 new orders | ¥237.5bn |
| Order backlog at year-end | ¥322.96bn |
Sold, installed, accepted, then paid
The gap between those two lines is timing, not demand. Tools are sold, installed and accepted before they are paid for, so a record order year converts into invoiced sales in later quarters. Lasertec's services line already earns through that cycle: services revenue rose 36.5% to ¥58.65 billion in fiscal 2026 while semiconductor-equipment revenue fell 17.2% to ¥168.09 billion 5.
The wires split on the headline
Investing.com's headline called it a raise in annual order guidance despite the revenue decline 1; RTTNews reported that Lasertec maintained its annual outlook 2. Both are true, and the split matters: the company raised its own measure of incoming work while leaving its financial forecast untouched. Lasertec still guides to ¥290 billion in sales and ¥125 billion in operating profit for the fiscal year ending June 2027 2.
What the session actually priced
Friday's damage came from the sector, not from Lasertec's release. The trigger was American: Alphabet's−0.95% — Alphabet, down 0.95 percent today Class A shares (GOOGL) fell 12.64% the previous night on doubts about the profitability of AI spending, and Amazon and Intel reported results that showed mounting investment requirements 14.
Tokyo then marked its chip complex down as one trade: Advantest lost 9.1%, Tokyo Electron 5.6%, Ibiden 15.2% and SoftBank Group 6.7%, while Lasertec fell 13.8%, deeper than either Japanese toolmaker 3. South Korea's KOSPI dropped more than 5%, and the Bank of Japan held its policy rate at 1.25% the same morning 4.
On the day its order guidance rose, Lasertec fell deeper than its toolmaker peers
Data
| Value | |
|---|---|
| Ibiden | -15.2% |
| Lasertec | -13.8% |
| Advantest | -9.1% |
| SoftBank Group | -6.7% |
| Tokyo Electron | -5.6% |
The strongest case for the sellers is real: Lasertec's own quarter was weak, with sales and profit down 2, fiscal 2026 revenue still fell 8.3% 5, and an order raise is the company's own measure of incoming work, unaudited by anyone outside the company. But if AI capex were peaking, this order book is where it would show first, and on Friday it went the other way.
The next reading is February
Watch Lasertec's interim order count in February. Orders that keep climbing while the tape keeps selling point to a valuation reset, not a demand problem; orders that roll over would vindicate the sellers.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.