Mistral's €3 billion round funds a pivot from open models to selling compute, with Nvidia on both sides
Six days, three disclosures: a gigawatt target, a promised sixfold capacity increase, and weights that missed their own deadline. Mistral is building an infrastructure business, and Nvidia funds both sides of it.
 Richard Tang · 3 min read
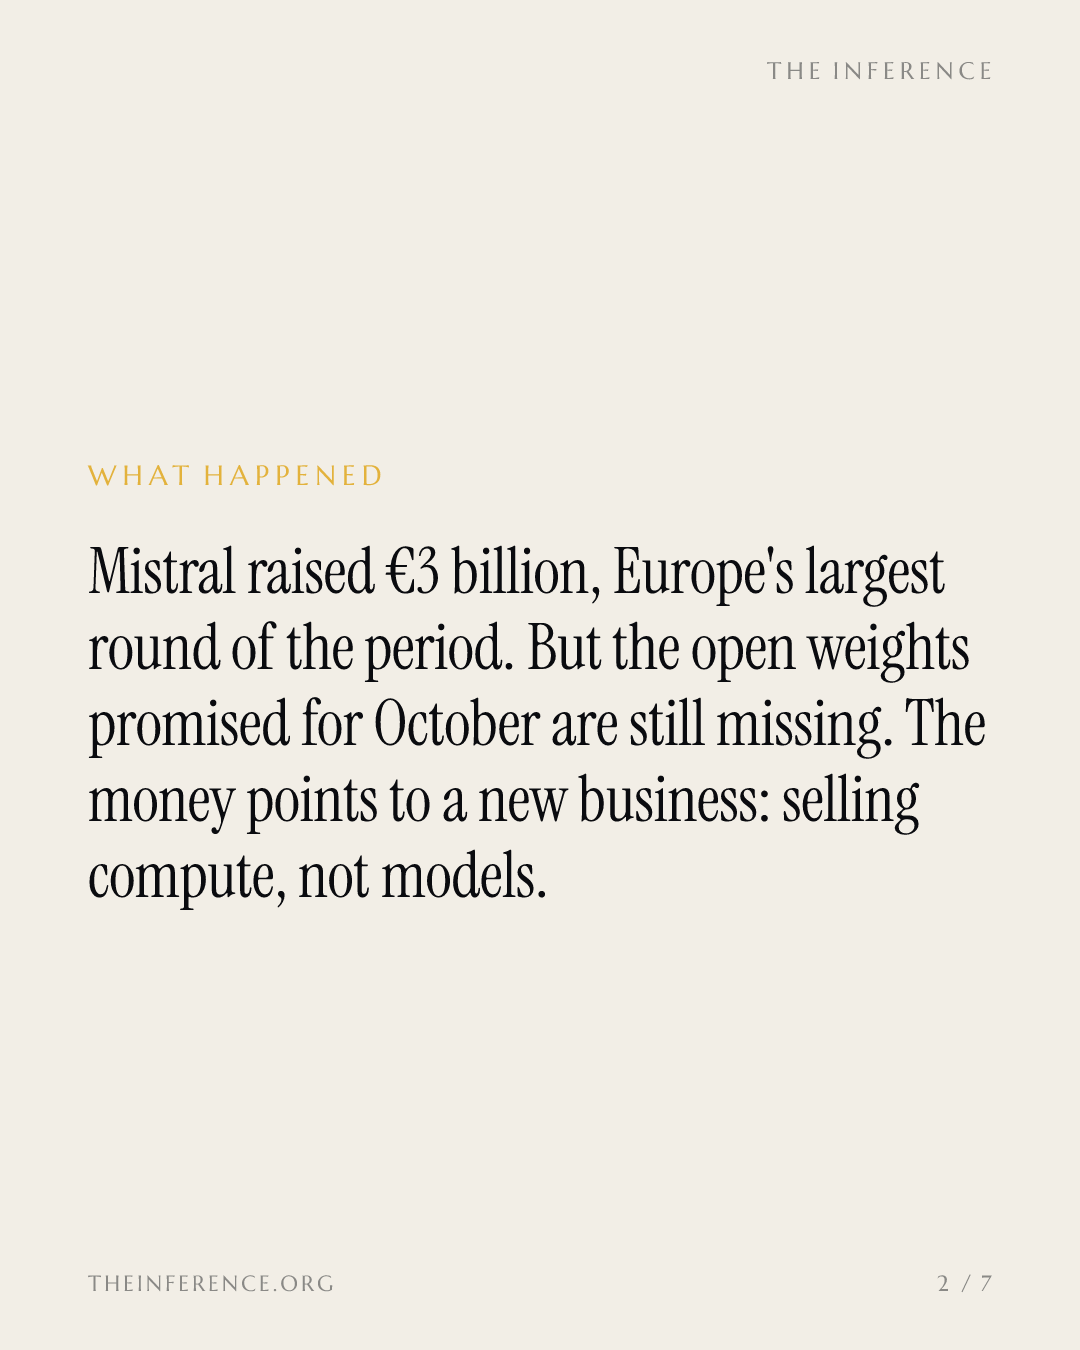
Mistral$14B — Mistral, private, latest valuation $14B is no longer pitching itself as Europe's open-model lab. In six days it disclosed a gigawatt-of-compute ambition 2, a promised sixfold capacity increase with another raise to pay for it 3, and still had not shipped the open weights it promised for the end of October 4. That combination points to a different business: infrastructure, where the model is the way to sell compute, agents and custom training to Airbus, BMW and ASML+2.01% — ASML, up 2.01 percent today, the industrial customers Mistral named at its Paris summit in May 1.
Arthur Mensch, Mistral's co-founder and CEO, made the argument himself in the Frankfurter Allgemeine Zeitung on October 24: European companies pay more than €260 billion a year to American cloud and software providers, and he wants that bill redirected 3.
The money is following the infrastructure story
Mistral's €3 billion Series D in September, at a valuation above €21 billion, was Europe's largest round of the period 1, and Tracxn, a funding-data tracker, shows late-stage rounds absorbing 53% of Europe's $61.9 billion in tech funding from about 9% of deals 6. Capital is concentrating on the company that owns the physical layer.
Selling the weights and selling the compute pull against each other
The tension is that Mistral sells two opposite things. One is Large 4, a trillion-parameter model whose weights customers could download and run without Mistral 2. The other is Mistral Compute, the infrastructure sale that needs them to stay.
On October 26 no source checked had confirmed the weights were live, and Mistral had not named their license 4. If Mistral follows rivals such as MiniMax, whose open weights carry conditions including prior authorization above $20 million in annual revenue 7, every tightening of the license makes the compute sale easier and the "open" claim weaker.
The price reinforces the point. Artificial Analysis, an independent benchmarking firm, puts the cost of running its Intelligence Index on Large 4 Preview at $1.13 per task, more than four times the cost of similar-intelligence open-weights models 8. That premium is only defensible if what the customer buys cannot be swapped out: European data residency, air-gapped deployment, custom training through Forge 1.
Mistral's input price sits far above its open-model rivals
Data
| Value | |
|---|---|
| Mistral Large 4 | 1.36 |
| Nemotron 3.5 Super VL | 0.23 |
| MiniMax M3.1 Flash | 0.15 |
Nvidia owns the plumbing either way
Nvidia+2.19% — Nvidia, up 2.19 percent today, the chipmaker, supplied the 3,800 Grace Blackwell GPUs that trained Large 4 in Mistral's own European data centers 2. It is also co-building an open-weight model with Mistral in the Nemotron Coalition 2, and selling its own Nemotron 3.5 Super VL at roughly $0.23 per million input tokens against Mistral's $1.36 45. It has separately agreed to buy Hugging Face, the open-model platform, for $12.9 billion 6. Nvidia funds the challenger and owns the plumbing either way.
The next test is not quality: Large 4 already holds 38 on Artificial Analysis's Intelligence Index, which the firm calls the most intelligent model from outside the US and China 8. What to watch is the license the weights ship under, and whether Airbus and BMW deploy the stack in production rather than pilot. If the deployments come, the sixfold build-out Mensch promised has a paying customer. If they stall, Europe will have funded a data-center operator with a model nobody had to buy.
Get Model by email, free
The AI labs, their models, and the business behind them. In our daily email, every weekday.
More about NVIDIA
NVDA · Fiscal Q2 2027Revenue rose 106% to $96.2B, 92.5% of it from Data Center, “driven by the ramp of our Blackwell Ultra infrastructure”. Gains on equity stakes of $7.8B lifted net income to $59.7B.
Show as a table
| Line | Value |
|---|---|
| Revenue | $96.2B |
| Gross margin | 75.0% |
| Operating margin | 66.2% |
| Net income | $59.7B |
| Hyperscale | $48.7B |
| AI clouds & enterprise | $40.3B |
| Data Center | $89.0B |
| Edge Computing | $7.2B |
| Gross profit | $72.1B |
| Cost of revenue | $24.1B |
| Other income | $7.8B |
| Operating income | $63.7B |
| Operating expenses | $8.4B |
| Tax | $11.8B |
| R&D | $7.1B |
| SG&A | $1.4B |