PayPal's revenue miss gives Stripe and Advent an opening below the $60.50 the board refused
The first results since the board refused Stripe and Advent at $60.50 a share: revenue missed, profit beat, and the same quarter feeds the bears and the buyers.
 Vincent Jiang · 3 min read
On October 27 PayPal−0.14% — PayPal, down 0.14 percent today, the San Jose-based payments company, reported a third quarter that could not pick a side: net revenue of $8.58 billion missed the $8.71 billion consensus, adjusted earnings of $1.45 a share beat the $1.31 estimate, and full-year adjusted earnings guidance rose to about $5.60 from about $5.38 1. Revenue grew 2.0 percent year over year 2.
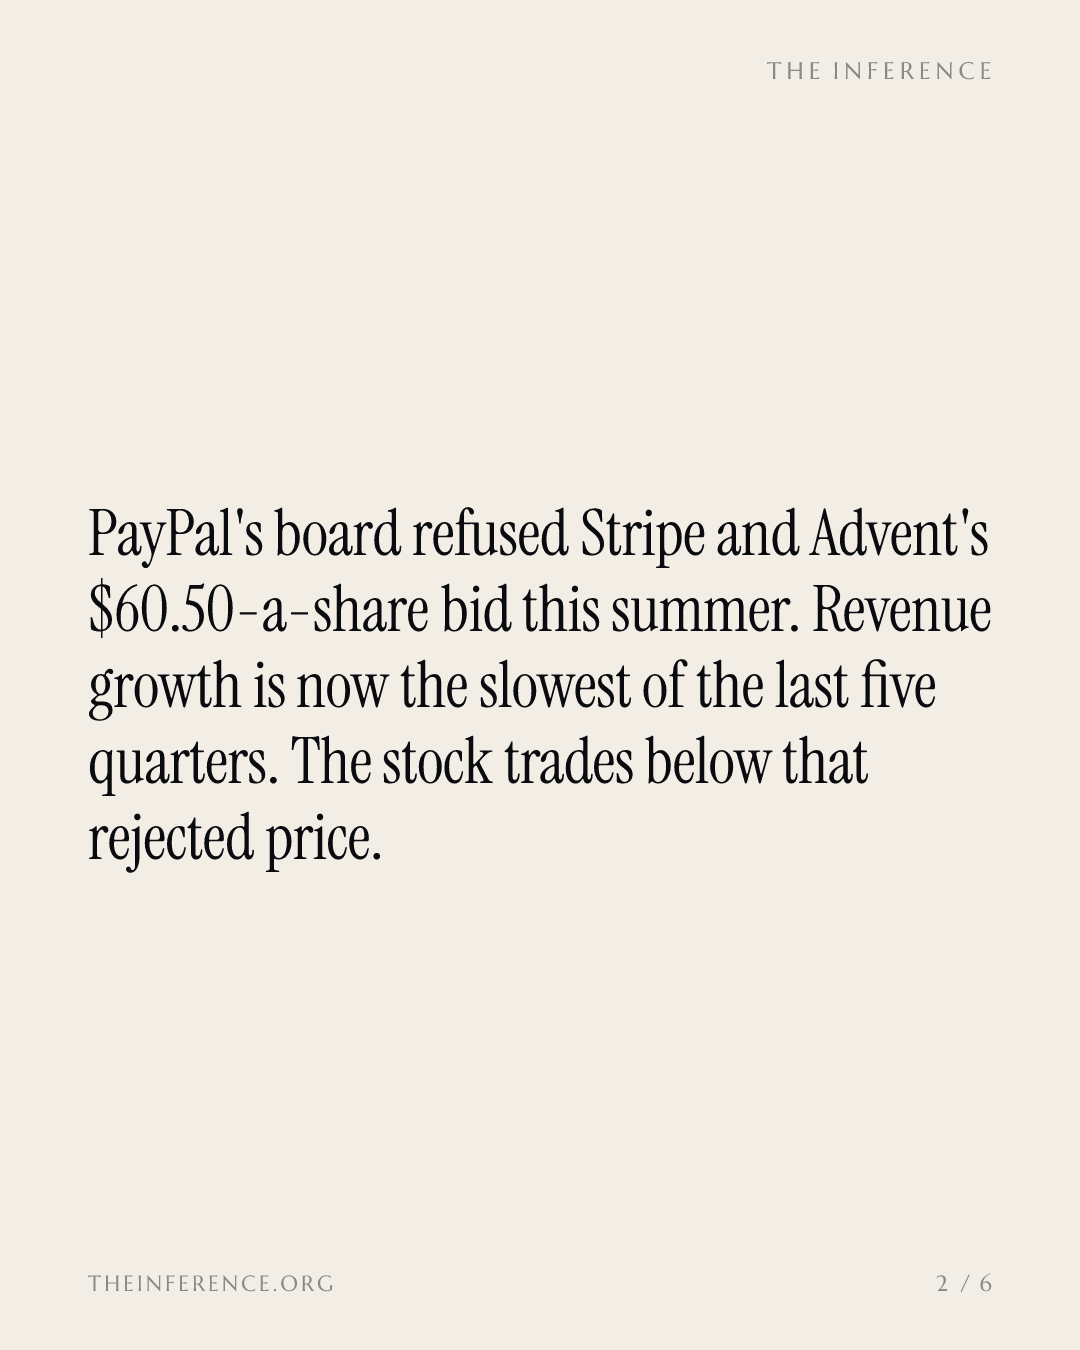
The print landed weeks after a summer of deal theatre. In July, Stripe and Advent International offered $60.50 a share in cash, valuing PayPal at more than $53 billion, a 28 percent premium over its July 14 close of $47.37 3. The board refused the price, talks resumed in mid-August, and the consortium walked away on August 28, knocking the shares down about 13 percent in a session 4.
What the buyers actually bid for
Chief executive Enrique Lores, who took over on March 1 after the board removed Alex Chriss in February 3, told investors PayPal is "collaborating with Meta−1.65% — Meta, down 1.65 percent today and other AI companies" to bring its trust proposition to agentic commerce, shopping done by AI agents on a customer's behalf 5. The prize behind the price is scale no one can build quickly: 440 million active accounts 6.
The print cuts both ways. Revenue grew 2.0 percent, and branded checkout volume has grown only 1 to 2 percent for four straight quarters, while Pay Later rose 25 percent, Pay with Venmo 43 percent and Braintree 10 percent 5. Yet non-GAAP operating margin still expanded to 18.8 percent, adjusted free cash flow reached $2.0 billion, and PayPal bought back $1.5 billion of stock in the quarter 6. GAAP net margin fell to 12.5 percent from 14.8 percent 7.
Revenue growth slid to 2.0 percent in the third quarter, the slowest in five quarters
Data
| Revenue growth, YoY | |
|---|---|
| Q4 '23 | 8.7% |
| Q1 '24 | 9.4% |
| Q2 '24 | 8.2% |
| Q3 '24 | 5.8% |
| Q4 '24 | 4.2% |
| Q1 '25 | 1.2% |
| Q2 '25 | 5.1% |
| Q3 '25 | 7.3% |
| Q4 '25 | 3.7% |
| Q1 '26 | 7.2% |
| Q2 '26 | 4.8% |
| Q3 '26 | 2% |
The street refuses to pay for either story
The market has settled the argument at no premium. The stock closed October 30 at $57.01, the mean target across 43 analysts is $57.10, and the consensus rating is HOLD 8; the bid sits about 6 percent above that close 3. After the print, Barclays−3.55% — Barclays, down 3.55 percent today downgraded PayPal to Underweight with a $53 target on October 29, while UBS and TD Cowen hold $60 and BMO $59 8.
Only the $60.50 bid stands above the street's $57.10 mean target
- Estimate
Data
| Value | |
|---|---|
| Barclays (estimate) | $53 |
| Street mean (estimate) | $57.1 |
| BMO (estimate) | $59 |
| UBS (estimate) | $60 |
| TD Cowen (estimate) | $60 |
| Stripe-Advent bid | $60.5 |
What decides it in February
Management guides fourth-quarter adjusted earnings to about $1.43 against the $1.35 estimate already reported 1, and gives 2027 guidance at the February print, with more investment planned and EPS growth targeted at a rate similar to 2026's 56. The street's mean target already prices the $5.60 floor, so the reading turns on whether the 2027 outlook beats it, or whether Lores spends the margin he has built 5. He said on the call the board remains "open to analyze objectively any option that is presented to us" 5.
The tell: whether a buyer, Stripe and Advent or anyone else, uses a 2 percent growth print to chip the price below the $60.50 the board already refused once 34.
Get Economy by email, free
How AI moves rates, banks, payments and the wider economy. In our daily email, every weekday.