ServiceNow lost a third of its value on one backlog line, and January settles the argument
Wall Street trimmed its ServiceNow targets by a fraction of last week's fall while the earnings estimates behind them barely moved. The dispute over whether AI agents shrink seat licenses now rides on one number: the current backlog print due in January.
 Richard Tang · 3 min read
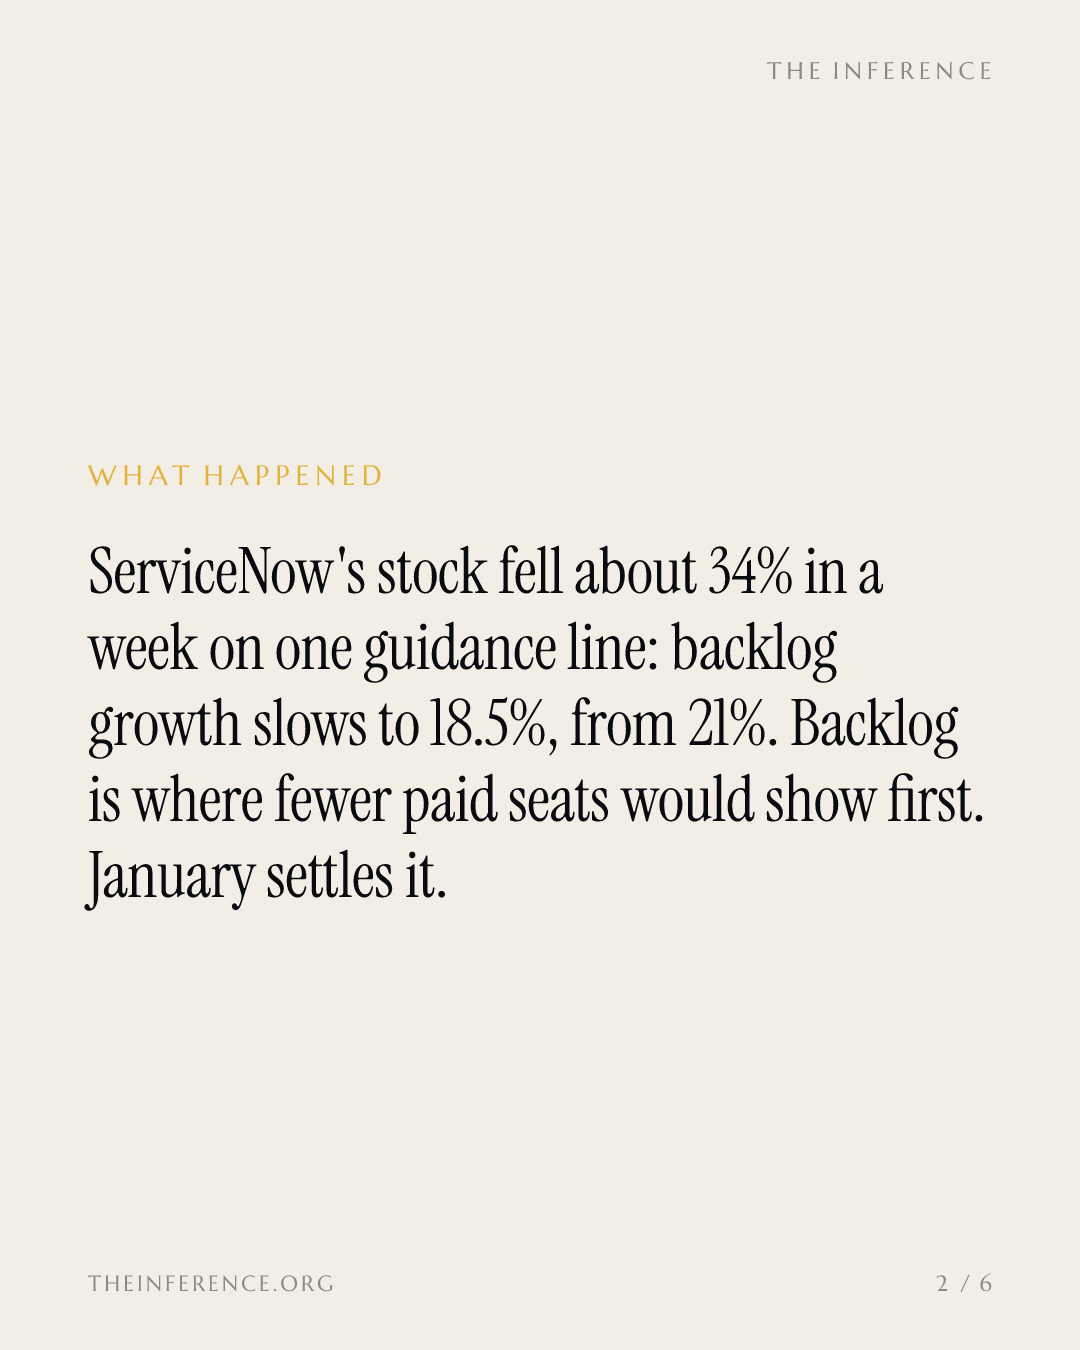
On November 3, Morgan Stanley+0.61% — Morgan Stanley, up 0.61 percent as of its last quote, Wells Fargo−0.52% — Wells Fargo, down 0.52 percent today and UBS cut their price targets on ServiceNow+0.44% — ServiceNow, up 0.44 percent today (NYSE: NOW), the workflow-software vendor that sells per-seat subscriptions to large enterprises, by roughly 7 to 11 percent 1. The cuts followed a brutal week in which the stock lost about 34% between October 23 and October 30, with 27% of that coming on October 29 alone 13. The banks moved slower than the market because the earnings estimates behind the targets barely moved. The real dispute sits elsewhere, and it has a deadline.
What broke was one guidance line. Management told investors that current backlog, the signed business that becomes 2027 revenue, would grow 18.5% in the December quarter, down from 21% in the September quarter 12. The market read that line as the first hard evidence that AI agents shrink seat licenses 3. Both camps in this argument now converge on the same test: the backlog print due in January 2.
Backlog is where a seat-shrink shows up first
The disruption thesis says agents will do work that used to require a paid seat. If that is true, revenue holds this year because contracts are already signed; the damage surfaces early in backlog, because backlog is where next year's seats get counted. That is why a two-and-a-half-point deceleration in one guided line hit the price so hard 13. Current backlog is the earliest instrument that can confirm or refute the fear, and ServiceNow, not a startup, is where the market chose to test it.
Management quantified less than half its own explanation
Management ascribed the slowdown to three causes it says will not hurt revenue: early renewals that pulled deals out of the December quarter, a public-sector shift to on-premise deals worth about 25 basis points of backlog growth, and contract provisions worth about 50, both of which still count in revenue 2.
It put figures on less than half the slowdown and gave no number for the renewal effect, while guiding subscription revenue growth to accelerate 2. Either the renewals are timing, in which case January's print snaps back, or they are masking softer demand, in which case this guide was optimistic. The company's own disclosure does not settle which.
Backlog decelerates while revenue growth accelerates
By management's own guide, backlog slows while subscription revenue accelerates
- Current backlog growth
- Subscription revenue growth
- Estimate
Data
| Current backlog growth | Subscription revenue growth | |
|---|---|---|
| Q3 actual | 21% YoY | 20.5% YoY |
| Q4 guide (estimate) | 18.5% YoY | 21.5% YoY |
The market repriced the story, not the estimates
The 2027 earnings estimate fell 4 percent 1. The stock, meanwhile, had gained 42% between June 30 and October 12 while forward estimates rose only 4%, a run that left the price vulnerable to exactly the news it got 1.
The week then took the valuation down: ServiceNow trades near 23 times forward earnings against a five-year average of 53 1. TIKR's own framing carries the condition: the stock appears undervalued only if its projected growth holds, and UBS, the one bank of the three that rates ServiceNow Neutral, warned that Wall Street's 2027 expectations may be too optimistic 1.
ServiceNow was the trigger, not the whole story
The week's selling also hit software broadly. Cloudflare+14.31% — Cloudflare, up 14.31 percent today, a web-infrastructure company, fell 14% and Datadog+3.09% — Datadog, up 3.09 percent as of its last quote, a monitoring-software company, fell 13% in the same week without reporting weak results, and Fortinet+2.01% — Fortinet, up 2.01 percent as of its last quote dropped about 20% after cutting its own full-year forecast 4. ServiceNow's earnings were the trigger, not the whole story. The three targets cut last week all sit above the $105.12 close, including UBS's $140 1.
All three cut targets still sit well above the close
The three targets cut last week all sit above the close, including the only Neutral rating
Data
| Value | |
|---|---|
| October 30 close | $105.12 |
| UBS target (Neutral) | $140 |
| Morgan Stanley target | $160 |
| Wells Fargo target | $175 |
Where observation ends
What is observable: 98% of customers renewed, total backlog is above $29 billion and growing faster than current backlog 2, the company raised its 2026 AI annual-contract-value target to $1.7 billion 1, and it lifted its full-year subscription revenue outlook alongside the guide that spooked the market 3. Enterprises are adopting, and the seat story still compounds today.
Reported revenue growth has held between 18.6% and 25.6% for twelve quarters
Data
| Revenue growth, year over year | |
|---|---|
| Q4 '23 | 25.6% |
| Q1 '24 | 24.2% |
| Q2 '24 | 22.2% |
| Q3 '24 | 22.2% |
| Q4 '24 | 21.3% |
| Q1 '25 | 18.6% |
| Q2 '25 | 22.4% |
| Q3 '25 | 21.8% |
| Q4 '25 | 20.7% |
| Q1 '26 | 22.1% |
| Q2 '26 | 24% |
| Q3 '26 | 20.5% |
What is projection: whether agents replace enough seats by 2027 to show up in signed business 2. One guidance line should not settle that, and nobody with money on it should settle it off one week's tape. Buy or fade the fear off the January print.
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.