Twilio drops 17% to $205 on a beat, and every analyst target sits above the close
Twilio raised its full-year outlook and still guided fourth-quarter organic growth down to 11-12%; a shareholder firm opened an investigation the same day, while every analyst target on the tape sits above the $205 close.
 Vincent Jiang · 3 min read
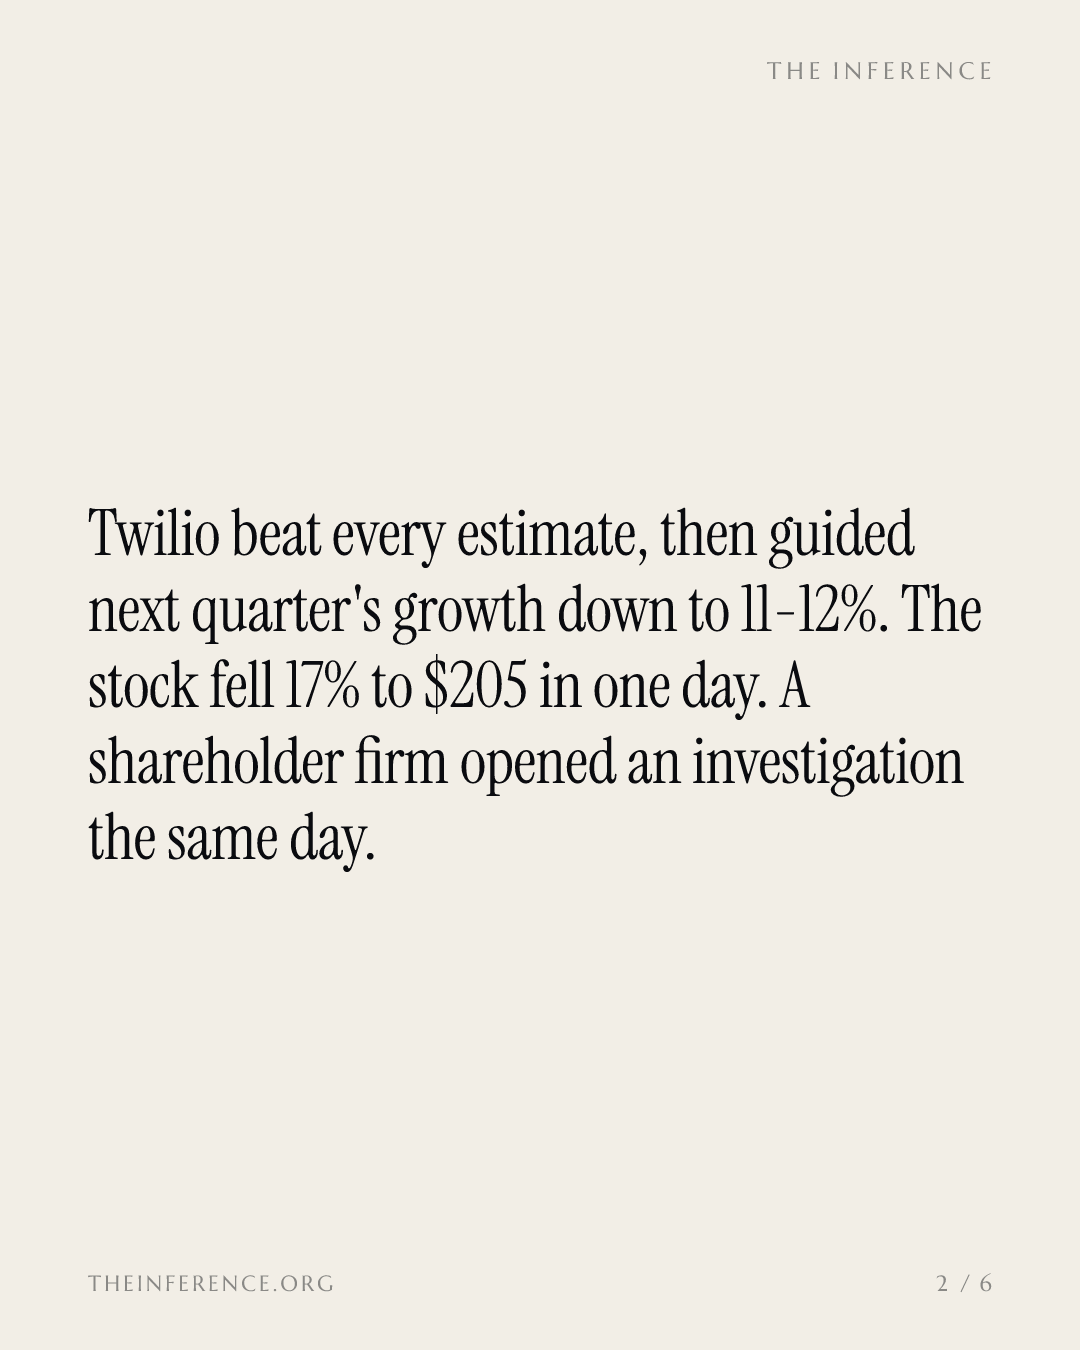
Twilio's−14.77% — Twilio, down 14.77 percent today third quarter beat on every line anyone grades. Revenue hit a record $1.56 billion, up 20% reported and 16% organic, non-GAAP earnings of $1.65 a share cleared the $1.47 consensus, and free cash flow set a record at $370 million. 123 Then the guide landed: fourth-quarter organic growth of 11% to 12%, four to five points below the rate just printed, and shares fell more than 10% in after-hours trading, dropped as much as 17% on Friday and closed at $205.03 against $241.90 the day before. 241
The charge quotes the company
Levi & Korsinsky, the New York shareholder-rights firm, opened an investigation the same day into whether Twilio's growth disclosures met federal securities laws. Its exhibits are management's own words: on May 1, 2025, CFO Aidan Viggiano, asked about a slowdown, answered "No, we're not seeing a slowdown, Mark"; on February 12, 2026, CEO Khozema Shipchandler cited "accelerating revenue growth." 5 The firm's arithmetic is the 4-to-5-point gap between the new outlook and the 16% just reported, with the slowdown sitting in Twilio's largest business. 5
Reported growth ran to 22% by mid-2026, and even the Q4 guide implies 17-17.5% reported
- Reported revenue growth, YoY %
- Estimate
Data
| Reported revenue growth, YoY % | |
|---|---|
| Q1 '24 | 4 |
| Q2 '24 | 4.3 |
| Q3 '24 | 9.7 |
| Q4 '24 | 11 |
| Q1 '25 | 12 |
| Q2 '25 | 13.5 |
| Q3 '25 | 14.7 |
| Q4 '25 | 14.3 |
| Q1 '26 | 20 |
| Q2 '26 | 22 |
| Q3 '26 | 20 |
| Q4 '26 guide (estimate) | 17.3 (17.0–17.5) |
The record moved up, not down
Here is the complication for the charge. In the same release, Twilio raised its full-year 2026 outlook: organic growth to 15% from 13% to 13.5%, free cash flow to $1.19 billion to $1.20 billion, and it pre-guided 2027 organic growth of at least 10%, above its own 7% to 8% Investor Day framework. 2
The deceleration the lawyers cite is messaging, about 60% of revenue, slowing from 18% organic growth in the second quarter to 17% in the third, which management attributed to tougher year-earlier comparisons. 2 The timing is awkward too: reported growth ran from 4% in early 2024 to 22% by mid-2026, accelerating through the stretch the quoted statements cover. 6
CFO Viggiano called the 11% to 12% guide "our strongest quarterly revenue guidance in several years" and put the company's historical beats at 2 to 4 points. 2 A disclosure case has to show what management knew when it spoke; on this tape, the slowdown is one point in one product, disclosed on the call itself.
The street reset and kept buying
The analysts who cut on October 30 cut less than the market did 73. UBS kept Buy and lowered its target to $255 from $285; JPMorgan held $300, Wells Fargo $275 and Needham $240, against a $271.73 consensus. 73 Every one sits above the $205.03 close, and the consensus implies roughly 33% upside 73. The market priced the exit rate, not the year.
Every October 30 price target sits above Twilio's $205.03 close
Data
| Value | |
|---|---|
| Needham | $240 |
| UBS | $255 |
| Consensus | $271.73 |
| Wells Fargo | $275 |
| JPMorgan | $300 |
Two dates decide it
The first is the fourth-quarter print in early 2027 2. If the 2-to-4-point beat pattern holds, organic growth lands in the mid-teens and the guide reads as prudence; if the messaging deceleration steepens, the guide reads as truth and the investigation becomes a case 2. The second is April 13-14, 2027, Twilio's Investor Day at its SIGNAL conference in San Francisco. 2 The money in play belongs to whoever bought above $205.03 before the guide, and the firm says investors who bought and sold at a loss remain eligible. 5
Get Platforms by email, free
The cloud, data and developer software AI is built on. In our daily email, every weekday.