A short seller says Iron Mountain's data center bet barely covers its interest bill. The stock rose.
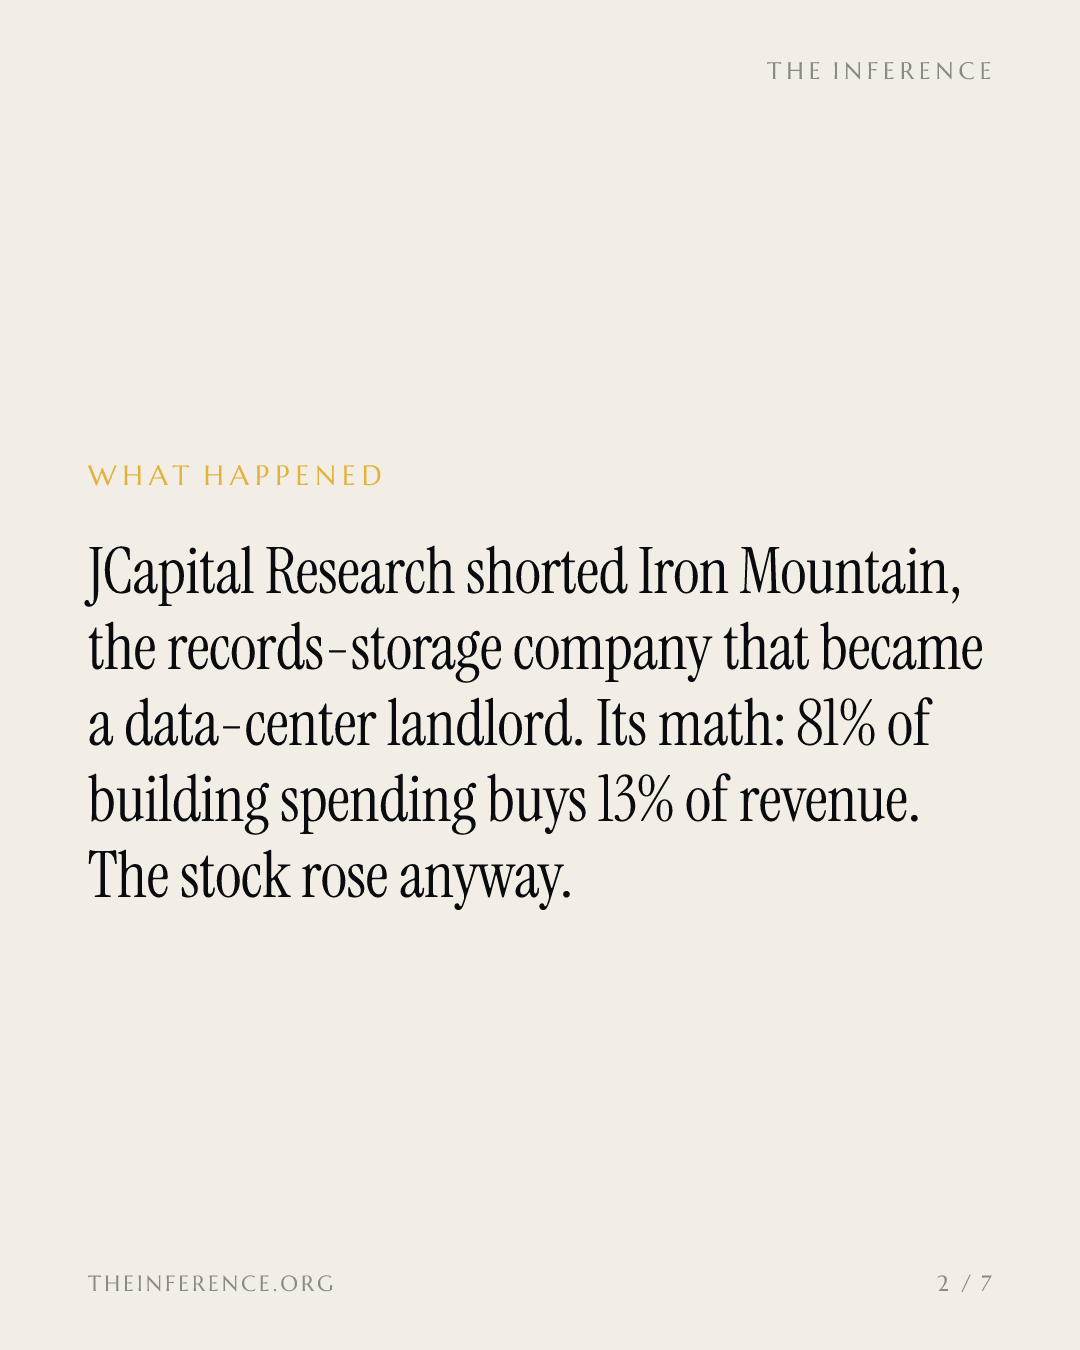
JCapital Research shorted Iron Mountain on October 28, arguing 81% of capex buys 13% of revenue at 1.7x interest cover. The filings agree with the arithmetic; the stock rose anyway.
 Vincent Jiang · 4 min read
The charge: 81% of the capex, 13% of the revenue
JCapital Research, a forensic short shop with prior fraud-adjacent calls, published its short on Iron Mountain−2.29% — Iron Mountain, down 2.29 percent today (IRM), the records-storage REIT turned data-center landlord, on October 28, 2026, under the title "Data Centers don't justify the optimism" 12. Its public section runs on arithmetic: about 81% of total capital spending was flowing into data centers as of the second quarter, while data centers bring in only about 13% of revenue 2.
By the report's count, the company holds roughly $17.3 billion in loans against $205 million of cash, borrows at an average 5.6%, and covered its interest bill 1.7 times last quarter, with net interest expense up from $488 million in 2022 to $829 million in 2025 2. JCapital also suspects Iron Mountain low-balls data center maintenance costs and depreciation, inputs that flatter adjusted funds from operations, the REIT cash measure behind the dividend 2. The full report sits behind a paywall 2.
The tape's first answer was to buy
The short was announced on October 28 1. The stock closed that session up 0.29% at $115.67 3, rose to about $118.4 the next day 45, and held near $116 at midday on October 30, down about 2%, while the Nasdaq 100 ETF (QQQ) dropped 2.8% 56.
Short interest stood at 2.44% of float on October 15, before the report, at 5.1 days to cover 6. No gap down, no borrow squeeze so far: the market has either not priced the thesis or has priced it and disagrees.
The filings concede the arithmetic
Checked against Iron Mountain's own filings, the short's numbers hold. Capex exceeded operating cash flow in all ten quarters from the first quarter of 2024 through the second quarter of 2026, and total debt climbed from $15.2 billion to $19.6 billion over the same stretch 7. A REIT must pay out most of its taxable income as dividends, which is why that gap gets debt-funded 2.
The 1.7x interest cover matches too: second-quarter operating income of $387 million against $225 million of interest expense 5. None of that is in dispute. The dispute is whether growth capex that lifted revenue 18.5% last quarter compounds into returns above 5.6% money, or stacks obligations onto a paper-storage business 24.
Capex outran operating cash flow in all ten quarters
- Capex
- Operating cash flow
Data
| Capex | Operating cash flow | |
|---|---|---|
| Q1 '24 | $0.38B | $0.13B |
| Q2 '24 | $0.4B | $0.38B |
| Q3 '24 | $0.4B | $0.25B |
| Q4 '24 | $0.61B | $0.43B |
| Q1 '25 | $0.68B | $0.2B |
| Q2 '25 | $0.55B | $0.38B |
| Q3 '25 | $0.52B | $0.27B |
| Q4 '25 | $0.52B | $0.5B |
| Q1 '26 | $0.51B | $0.34B |
| Q2 '26 | $0.58B | $0.55B |
Debt up $4.4 billion in ten quarters while cash stayed near $200 million
- Total debt
- Cash
Data
| Total debt | Cash | |
|---|---|---|
| Q1 '24 | $15.23B | $0.19B |
| Q2 '24 | $15.39B | $0.14B |
| Q3 '24 | $15.82B | $0.17B |
| Q4 '24 | $16.05B | $0.16B |
| Q1 '25 | $17.14B | $0.16B |
| Q2 '25 | $17.85B | $0.22B |
| Q3 '25 | $18.48B | $0.2B |
| Q4 '25 | $18.73B | $0.16B |
| Q1 '26 | $19.39B | $0.25B |
| Q2 '26 | $19.62B | $0.21B |
The bull ledger
The bulls bring records. Second-quarter revenue hit $2.03 billion, up 18.5%; AFFO rose 17% to $433 million, or $1.44 a share, against a declared quarterly dividend of $0.864 4. The data center, digital and asset lifecycle management businesses grew more than 50% year over year, leasing reached 110 megawatts year to date, and management raised full-year guidance to $7.94 to $8.01 billion of revenue 4.
The company pegs net lease adjusted leverage at 4.8x, its lowest since 2014 5. Wall Street rates the stock eight Buys, no holds, no sells, with 12-month targets of $132 to $155 5. A dividend newsletter had called the pullback a buy six days before the short arrived 8.
The last short seller's scoreboard
This is Iron Mountain's second forensic fight inside a year. On November 19, 2025 Gotham City Research published a short alleging adjusted EBITDA overstated 25% to 35%, true leverage of 9x against a reported 5x, and dividends uncovered by cash flow for twelve years, valuing shares at $23 to $41 9.
The stock bottomed at $77.77, then rallied to $129.49 by August 14, 2026, while short interest thinned from 3.8% of float in December to 2.44% 56. Eleven months on, shares near $116 trade at almost three times Gotham's ceiling price 59. That call was priced and, so far, rejected.
The stock trades near three times the last short seller's ceiling
Data
| Value | |
|---|---|
| Gotham floor | $23 |
| Gotham ceiling | $41 |
| IRM now | $116 |
| Street low | $132 |
| Street high | $155 |
The verdict is scheduled
Third-quarter results arrive November 5 before the open, with consensus at $0.61 of earnings on $1.99 billion of revenue 45. Three tells decide whether JCapital's call sticks: whether data center depreciation and maintenance disclosures answer the low-balling charge, whether borrow costs and options skew reprice, the move that typically comes first in episodes like this 1, and whether capex keeps outrunning cash generation 7.
Iron Mountain's newest notes pay 6.25%, against the 15% CoreWeave−11.15% — CoreWeave, down 11.15 percent today agreed to pay on its debt, as reported here on October 17; lenders have already ranked the data-center borrowers 410. The arithmetic is not in dispute. What the arithmetic means is the whole fight.
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.