Credo Doubled Sales. Now It Must Earn the Cash.
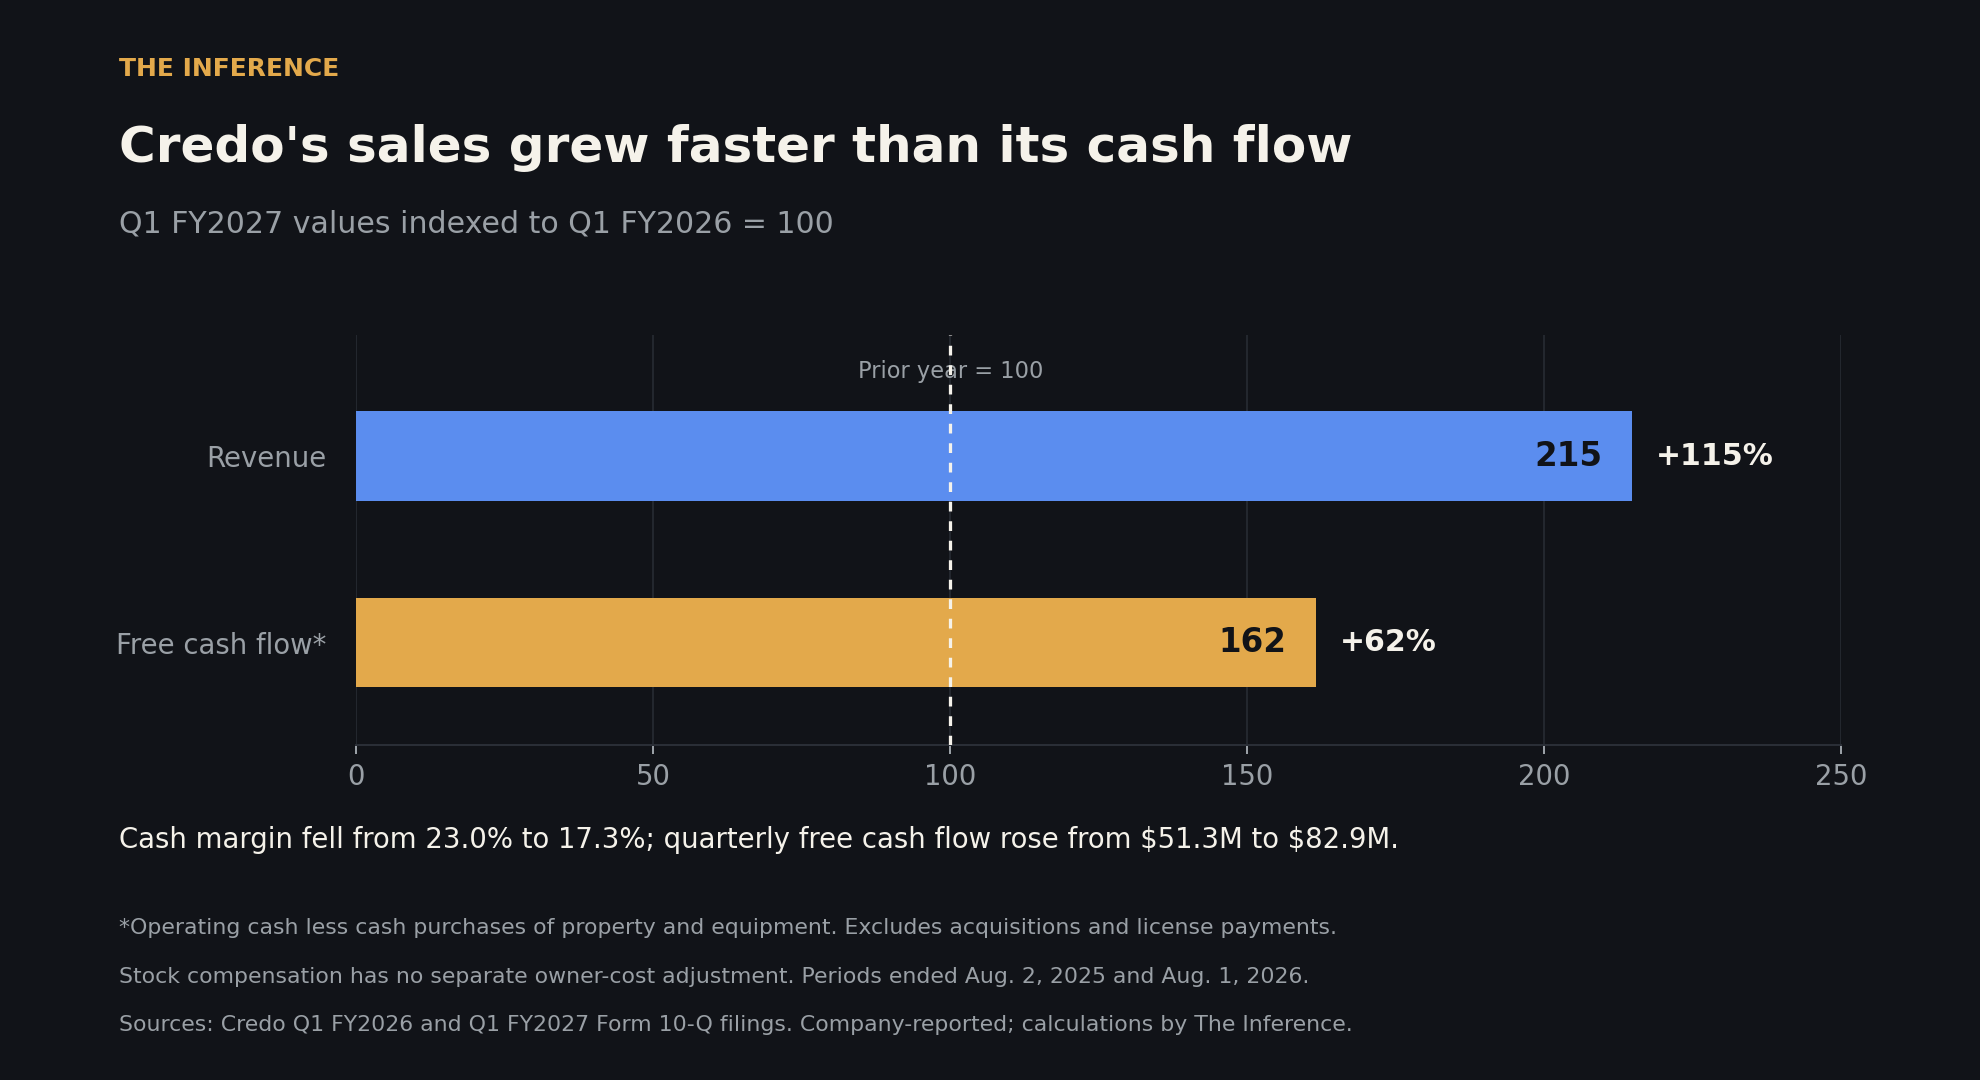
Quarterly revenue rose 115% to $479 million. Cash margin fell from 23.0% to 17.3%, and four customers account for 84% of it.
 Vincent Jiang · 6 min read
The cable protects something more expensive
Bill Brennan used Credo's−8.13% — Credo, down 8.13 percent today September 1 earnings announcement to describe a connectivity portfolio stretching from millimetres to kilometres. The ambition has numbers behind it: quarterly revenue reached $479 million, up 115% from a year earlier.1 His challenge is turning that expansion into durable returns while customers keep redesigning the connections inside AI systems.
Credo has a valuable position in AI infrastructure. At its current valuation, though, owning an essential product is only the beginning. Investors need evidence that the company can retain enough profit per connection and convert that profit into cash per share.
The economic case starts with the machines at either end of the connection. Meta's−1.65% — Meta, down 1.65 percent today engineers explain that synchronised training can allow one straggling GPU to hold up an entire cluster. Failures also impose checkpoint and restart costs. This describes why reliability matters; it does not establish Meta as a disclosed Credo customer.2
An active electrical cable, or AEC, uses chips to restore a deteriorating signal. That extends copper's useful reach beyond passive cables, which need less power but offer less signal correction. The tradeoff becomes more consequential as transmission speeds rise.3,4
Credo therefore competes on the cost of keeping a system productive. A slightly cheaper connection is poor value if it introduces enough interruptions to idle expensive accelerators.
There is evidence beyond Credo's marketing: an Arista and Broadcom−5.24% — Broadcom, down 5.24 percent today deployment guide includes a seven-metre Credo AEC among its prequalified options. Qualification provides a reason for customers to keep buying a familiar component, although that guide also lists alternatives.5
The cheapest connection is the one that keeps the expensive machines working.
Growth is arriving ahead of cash conversion
For the quarter ended August 1, operating cash of $90.2 million less $7.3 million in property and equipment purchases produced $82.9 million of conventional free cash flow, or 17.3% of revenue.6
The comparable margin a year earlier was 23.0%. Cash generation grew, but materially more slowly than sales. These are our calculations from the two periods, using the same definition.7
Working capital explains much of the gap. It absorbed $151.3 million, including $61.5 million for inventory and $54.5 million for receivables. Management attributes inventory growth to unfulfilled backlog and new product ramps. Capacity deposits also required cash. These commitments can support future deliveries; they are not evidence that customers have stopped paying.6
Still, a chip designer can outsource manufacturing and remain exposed to the cost of preparing production. If inventory converts into shipments and collections, cash margins can recover. If deployment schedules slip, Credo carries the preparation cost for longer. The next few quarters should help distinguish productive expansion from persistently heavier cash requirements.
Four customers shape the economics
Four end customers accounted for 84% of quarterly revenue, with individual shares of 33%, 28%, 13% and 10%. These are end-customer figures, distinct from the intermediaries that place orders.6
That concentration helps explain both the opportunity and the vulnerability. Winning a major platform can produce enormous volume. The same customer can delay a rollout, demand better pricing or qualify another supplier. Adding optical products does not automatically diversify the buyers.
Astera Labs−10.58% — Astera Labs, down 10.58 percent today already markets an alternative AEC platform with diagnostics and support for multiple cable manufacturers. Its existence does not prove equivalent field performance, but it prevents investors from treating the category as Credo's private market.8
Marvell−9.25% — Marvell, down 9.25 percent today and Luxshare demonstrated a more subtle challenge in April: a hybrid cable using a full signal-processing chip at one end and simpler circuitry at the other. This was a prototype, not disclosed commercial share loss. Our inference is that copper connections could multiply while some designs require less high-value silicon per connection.9
Optics expands the opportunity and the burden of proof
Brennan has acted on copper's physical limits. Credo completed its DustPhotonics acquisition in May, adding silicon photonics to its capabilities.10
The strategic logic is sound: control more of the technology that turns electrical signals into light, and offer customers solutions across more distances. At announcement, management expected its combined optical portfolio to exceed $500 million in fiscal 2027 revenue. That forecast covered transceivers, optical signal processors and photonics together. It was neither DustPhotonics' standalone sales nor a separate increment investors should add to company guidance.11
The complication is that optical architectures are changing too. Linear pluggable optics remove the signal processor from the optical module and shift correction toward the connected networking chips. The Arista and Broadcom guide describes this approach alongside conventional alternatives. More optical traffic does not necessarily mean proportionally more demand for standalone optical processors.5
Nvidia−3.89% — Nvidia, down 3.89 percent today announced production of its Spectrum-X Ethernet Photonics system in May for networks connecting larger groups of machines and facilities. That development does not establish an immediate replacement for short copper connections. The Ethernet Alliance's roadmap likewise shows copper and several optical approaches advancing together.12,13
Credo's broader portfolio is a reasonable response. The return will depend on which designs customers adopt, what Credo supplies inside them and how much margin survives the competition.
The share price already demands progress
At September 14's $150.09 close, applying the August 25 share count gives an approximate equity value of $28.2 billion.14,6
We calculate trailing conventional free cash flow of $438.6 million by taking fiscal 2026 cash flow, removing its first quarter and adding the latest quarter. That puts the stock near 64 times trailing cash flow. This uses actual trailing periods, avoiding the distortion of annualising one quarter's working-capital swing.15
For illustration, a 35-times cash-flow multiple would require about $806 million of annual cash flow to support today's equity value, roughly 84% above the trailing amount. Thirty-five times is an assumption, not a fair-value estimate. The exercise shows how much operating progress a lower future multiple could consume.
Stock compensation adds another consideration. The latest quarter included $88 million of it, about 18% of revenue. It is not a current cash payment, but issuing equity can reduce each existing share's claim on future profits. Cash-flow growth and cash-flow growth per share deserve separate attention.1
What would strengthen the investment case
The strongest counterargument is straightforward: Credo may be funding a large expansion before the cash arrives. Existing qualifications, rapid growth and additional optical products could let it spread development costs across a much larger sales base. Management's next-quarter revenue outlook of $525 million to $535 million supports continued momentum, although it remains guidance.1
Watch collections relative to sales, inventory relative to shipments, and cash generation per share. Also look for optical growth that broadens the customer base while preserving margins.
On September 15, Credo announced 1.6T optical transceivers combining its signal processor, silicon photonics and diagnostics. That makes the integration strategy more concrete. The announcement does not disclose a new customer purchase commitment; qualifications and volume purchases will determine its commercial value.16
Brennan has established that customers want more of what Credo sells. The next proof is whether supplying it leaves shareholders with a growing share of the cash.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.