Flex trades at $28.5 billion as its AI segment, up 53.9%, leaves for Axiom and $4.4 billion of debt stays
Flex's AI segment departs for Axiom at a $37.5 billion private mark while the company itself trades at $28.5 billion, with the EPC Power debt staying behind; the first post-separation guidance will say which side is right.
 Richard Tangfour-minute read
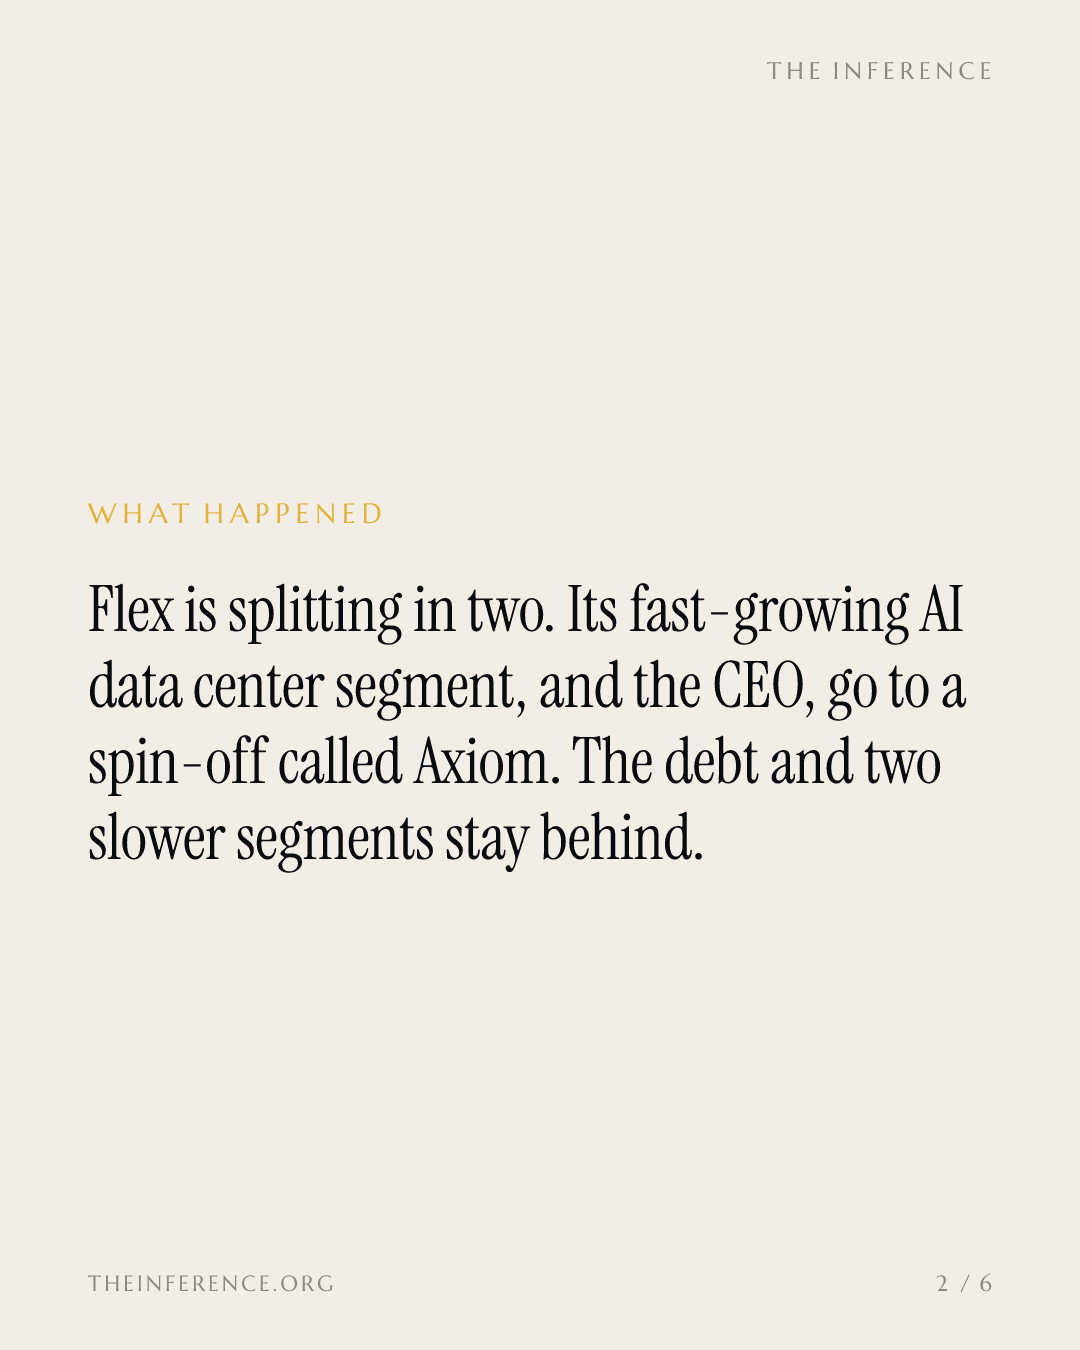
Flex−0.91% — Flex, down 0.91 percent today posted a fourth straight earnings beat on October 28, and the market barely moved, because the filing behind it splits the company in two: the growth unit and the CEO go to Axiom, the debt stays 12. The Cloud and Power Infrastructure segment, the only piece of Flex riding the AI data center buildout, grew 53.9% year over year to $2.51 billion in fiscal Q2 at a 10.7% operating margin 1. It departs for Axiom, the spin-off that General Catalyst and Koch Equity Development valued at $37.5 billion in a $2 billion preferred investment last month 34.
Yet all of Flex, Axiom stake included, trades at a $28.5 billion market cap 2. The market is pricing the rump as if it were worth roughly nothing after the $5.98 billion of total debt that, on Basis Report's reading of the filing, stays with continuing Flex 2.
Flex's highest-margin segment is the one that leaves
The best-margin segment is the one leaving
Data
| Value | |
|---|---|
| CPI (leaves for Axiom) | 10.7% |
| RMS (stays) | 6.4% |
| ITS (stays) | 5.5% |
The filing sends the growth unit to Axiom and keeps the debt
The fiscal Q2 10-Q, filed this week, shows what each side gets 1. Flex, a 149,000-person electronics manufacturing services company, is divided into three segments 12. What stays behind are Integrated Technology Solutions, at $3.31 billion of quarterly revenue and a 5.5% margin, and Regulated Manufacturing Solutions, at $2.68 billion and 6.4% 1.
The segment leaving is the smallest of Flex's three at just under 30% of revenue
- ITS (stays)3.3139%
- RMS (stays)2.6831.5%
- CPI (leaves for Axiom)2.5129.5%
Data
| Slice | Value | Share |
|---|---|---|
| ITS (stays) | 3.31 | 39% |
| RMS (stays) | 2.68 | 31.5% |
| CPI (leaves for Axiom) | 2.51 | 29.5% |
What also stays is the bill: $4.4 billion of new term and bridge debt taken on October 14 to buy EPC Power, a maker of power-conversion systems for 800-volt AI data centers 12. Basis Report's reading of the filings puts that debt with continuing Flex, not Axiom, which takes the growth narrative with it 2.
The CEO leaves with the growth unit
CEO Revathi Advaithi, who led the four-beat run, departs to run Axiom when the spin closes in calendar Q1 2027; we covered that destination alongside Basis Report's on November 4 2. What is new this week is the segment detail in the 10-Q and the debt allocation, and the arithmetic they make possible 2.
The beats were four straight, with the largest surprise last quarter, and the stock still sits near half the $156.50 consensus target at 9.9 times forward earnings 2. Chief Commercial Officer Michael Hartung sold 2,755 shares in August at $119.79 to $123.25, about 54% above today's $77.48 2.
Five straight quarters of growth have taken Flex revenue to $8.49 billion
Data
| Revenue | |
|---|---|
| Q4 '24 | $6.56B |
| Q1 '25 | $6.4B |
| Q2 '25 | $6.58B |
| Q3 '25 | $6.8B |
| Q4 '25 | $7.06B |
| Q1 '26 | $7.48B |
| Q2 '26 | $7.93B |
| Q3 '26 | $8.49B |
Buyers price the spin, skeptics price the split
Buyers of spin-arbitrage, the trade of holding a company through a separation to capture the value the market has not yet priced, point to the mark: General Catalyst and Koch Equity Development put $2 billion into Axiom at a $37.5 billion enterprise value, Bank of America−0.20% — Bank of America, down 0.20 percent today raised its target after Q2, and the departing segment is guided to grow 75% to 85% this fiscal year 2345. Skeptics point to the split: the CEO, the fastest-growing segment and the beat record all leave together, while the debt and two slower segments stay.
The checkpoint is the first post-separation guidance
A $28.5 billion market cap against a $37.5 billion mark on the piece leaving is not the market being dumb 2. It is the market declining to pay for a rump it cannot yet value. The test is legible: the first post-separation guidance from continuing Flex. If its two segments hold a double-digit beat pace without Axiom, the 10-times multiple looks like a floor; if they cannot, the August sale prices look like the more durable read 2.
The premium goes to whoever sells the power, not the boxes
Watch that guidance, and watch whether the company that turns power and compute into AI product, not the factory that makes the boxes, keeps capturing the premium. That is where the value in this buildout is being decided.
Sources: 1. Earnings Anatomy, Flex Ltd. Q2 Analysis: AI Data Center Boom, EPC Deal, and Axiom Spin-Off, November 12, 2026 — https://earningsanatomy.com/blogs/flex-ltd-q2-cloud-power-infrastructure-axiom-spinoff 2. Basis Report, Flex Posts Fourth Straight Beat Yet Stock Falls; CEO Exits, November 4, 2026 — https://www.basisreport.com/news/flex-fourth-beat-stock-falls-ceo-exits 3. Pulse 2.0, Axiom Secures $2 Billion Convertible Preferred Investment At $37.5 Billion Enterprise Value, October 5, 2026 — https://pulse2.com/axiom-secures-2-billion-convertible-preferred-investment-at-37-5-billion-enterprise-value/ 4. Interconnecting Intelligence, Flex plans to spin off its Cloud and Power Infrastructure business as Axiom Solutions International, Inc., November 10, 2026 — https://interconnectingintelligence.com/item/229/flex-plans-to-spin-off-its-cloud-and-power-infrastructure-business-as-axiom-solu 5. 24/7 Wall St., Flex (FLEX) Q2 2027 Earnings Beat Fueled by AI Data Center Boom, October 28, 2026 — https://247wallst.com/cards/flex-q2-2027-earnings-flex-01m613hb8bw4mt73trm5wh1w3q
Get Data Center by email, free
Who is building AI's data centers, and who is paying for them. In our daily email, every weekday.