Globus Medical previews an implant designed in software and placed by its robot, Q3 due November 5
FDA-cleared but not yet for sale, SCRIPT was previewed at NASS on October 14; its plans import straight into the ExcelsiusGPS robot. With Q3 results due November 5, the earnings test is whether US spine keeps taking share while the robotics business works through its leasing shift.
 Richard Tang · 2 min read
Globus Medical+0.36% — Globus Medical, up 0.36 percent today has put its first patient-specific spinal implant on display, and the interesting part is not the implant. It is the plumbing behind it. SCRIPT, previewed this week at the North American Spine Society meeting in San Antonio, is FDA-cleared but not yet for sale. The company is showing that a surgeon's plan now flows, unbroken, from software to robot. 1
The plan now imports straight into the robot
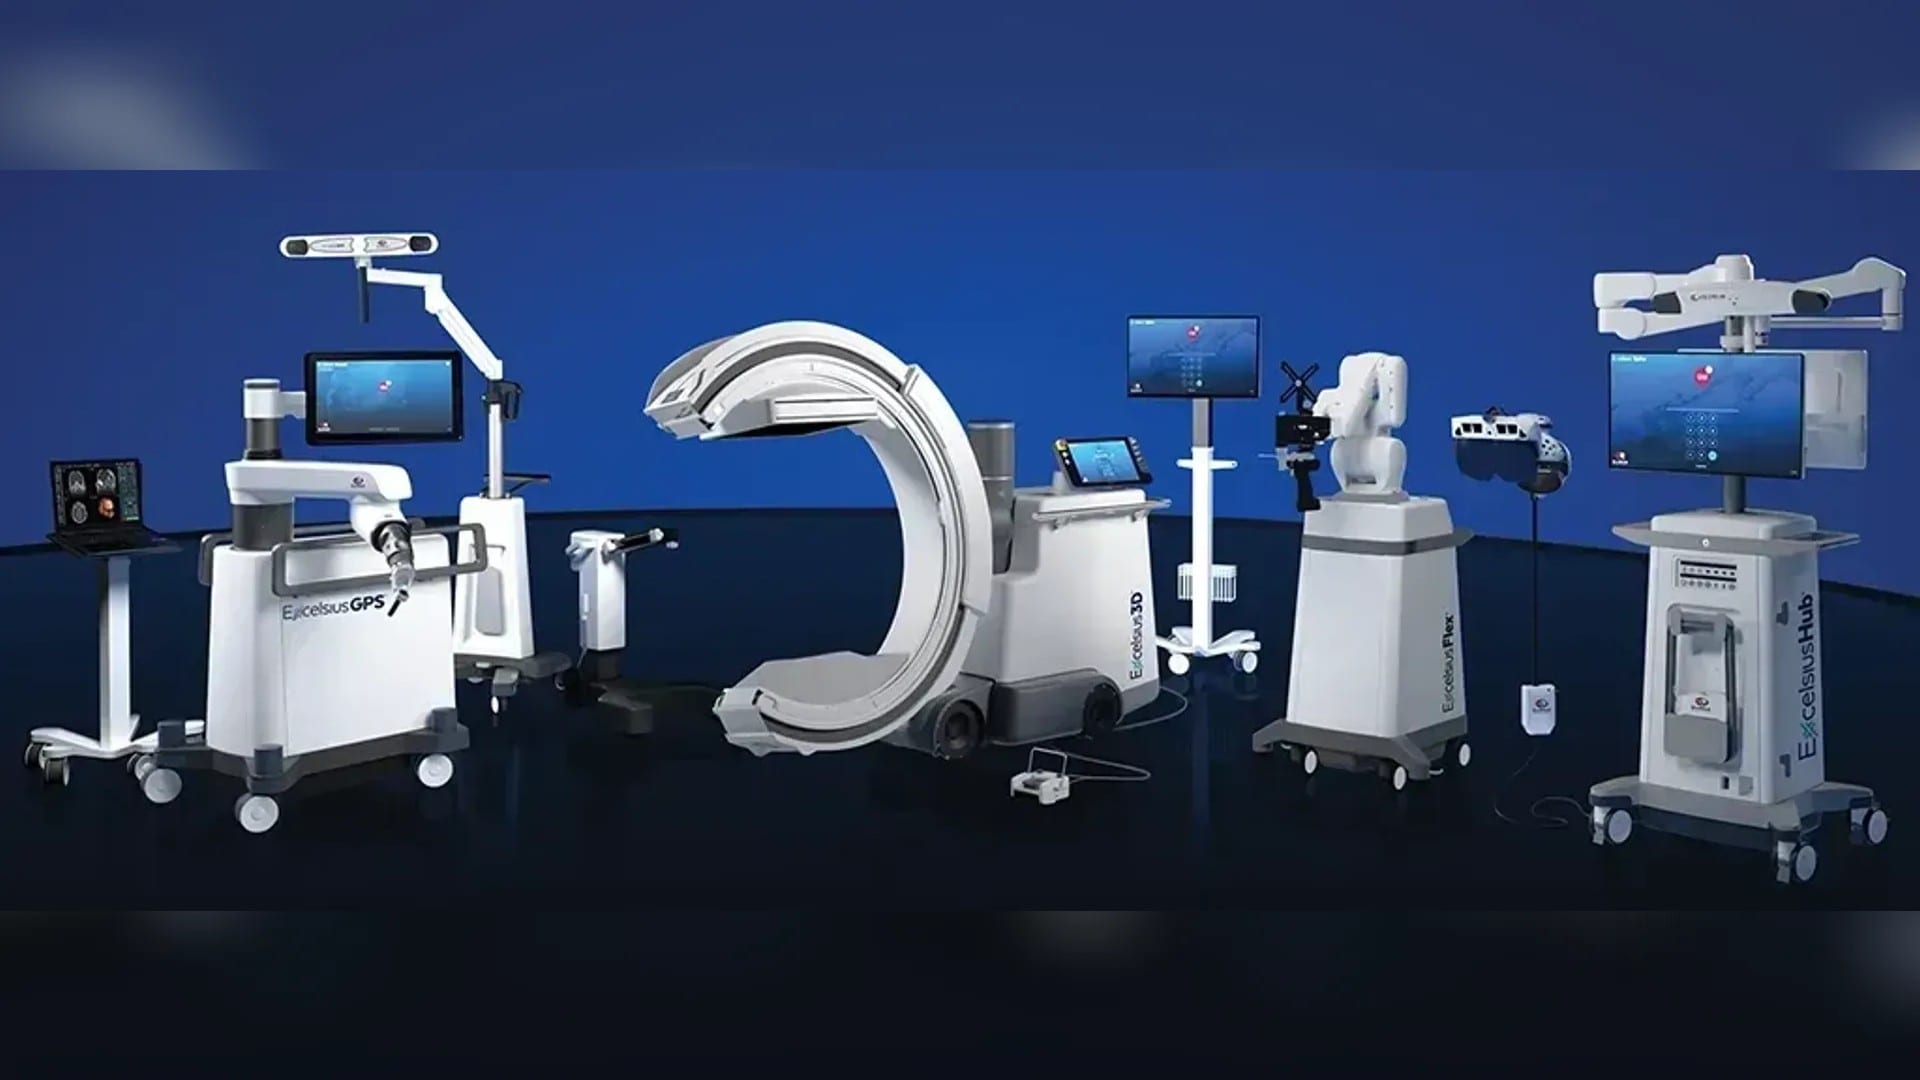
In SCRIPT Studio, the surgeon controls alignment, implant position, geometry and fixation, essentially designing the implant for that one patient. The plan then imports directly into ExcelsiusGPS, Globus's surgical navigation robot, or ExcelsiusHub. That makes Globus's robot and implant a single product rather than two purchases. 1
Lock-in is the point, and the proof is still owed
That matters for the investment case. Globus's growth rests on US spine taking share, which it did again in Q2 with 7% growth, its fifth straight quarter above the market. 3 Its enabling-technologies reported sales fell 26% on the shift to leasing even as unit deployments grew 25%, a transition the company frames as strategic rather than lost demand. 4
Q2 spine grew 7% while leasing hid 25% more robot deployments
Data
| Value | |
|---|---|
| US spine revenue growth | 7 |
| Enabling-tech reported sales | -26 |
| Enabling-tech unit deployments | 25 |
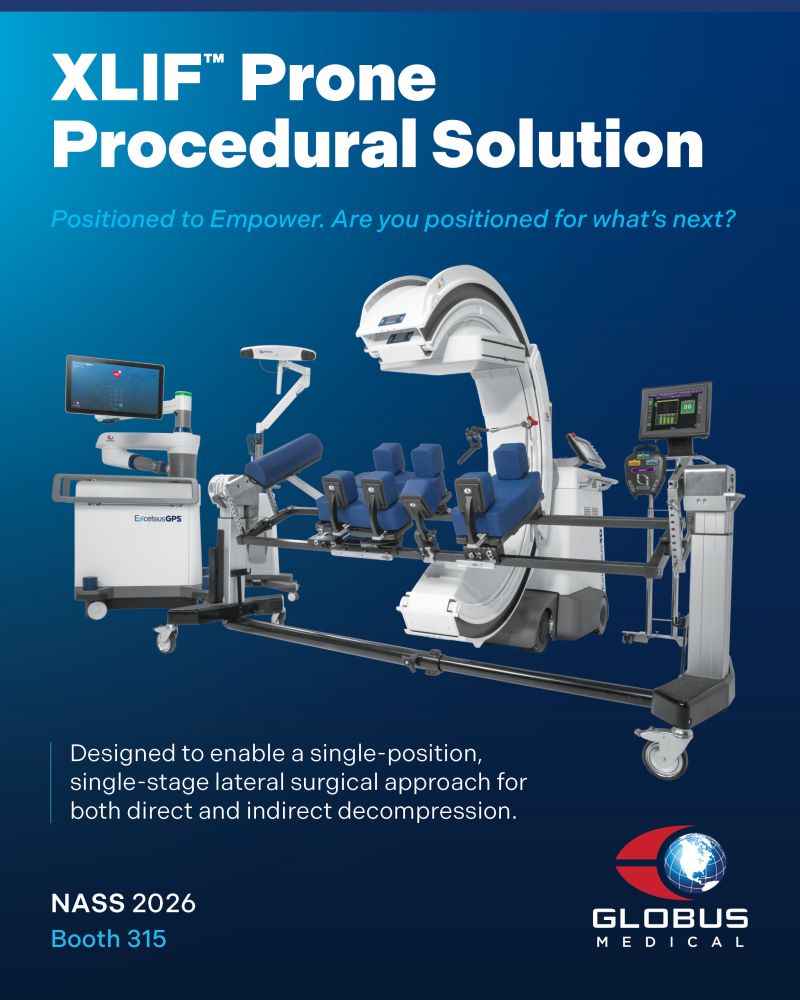
A patient-specific implant is a way to deepen a surgeon's dependence on that ecosystem, at more revenue per case, against Medtronic−0.92% — Medtronic, down 0.92 percent today and Stryker−0.52% — Stryker, down 0.52 percent today, the two largest diversified spine competitors. The XLIF Prone positioner and MaXcess Air retractor announced alongside SCRIPT extend the same packaging of positioning, access and execution. 1 If SCRIPT commercializes well, it should deepen that tie; whether it also translates into pricing power is a hypothesis no source has tested yet, and it depends on launch terms Globus has not disclosed.
No launch date, no pricing, no forecast
The open link is commercialization. The company has given no launch date, no pricing and no revenue expectation, so this is a suite demo until a surgeon's schedule proves otherwise. 1
What to watch on November 5
Q3 results land after market close on November 5, against consensus of roughly $792 million in revenue and $1.20 in adjusted EPS, up modestly from $769 million and $1.18 a year ago. 3 The lock-in thesis needs two things in that print: US spine growth holding its above-market pace, and a sign the robotics business is past its leasing transition. If both show, the SCRIPT bet starts to look like a growth story rather than a trade-show display.
Q3 consensus of $792 million would top last year's $769 million by about 3%
- Revenue
- Estimate
Data
| Revenue | |
|---|---|
| Q1 '24 | $606.67M |
| Q2 '24 | $629.69M |
| Q3 '24 | $625.71M |
| Q4 '24 | $657.29M |
| Q1 '25 | $598.12M |
| Q2 '25 | $745.34M |
| Q3 '25 | $769.05M |
| Q4 '25 | $826.42M |
| Q1 '26 | $759.85M |
| Q2 '26 | $789.61M |
| Q3 '26E (estimate) | $792M |
Get Health by email, free
AI in medicine, pharma and biotech. In our daily email, every weekday.