Guosheng put 6.2 billion yuan into Hua Hong's parent; the listed chipmaker gets the capacity, not the cash
Guosheng Group's cash increase lifts Hua Hong's parent to 19.7 billion yuan of registered capital and its indirect stake in the listed chipmaker to 10.2%, with control unchanged. The new capacity reaches the listed register; the cash never does.
 Vincent Jiang · 2 min read
The check cleared one register above the shareholders who own the risk. Shanghai Guosheng Group led a 6.2 billion yuan cash increase into Huahong Group, the parent of Hong Kong- and Shanghai-listed Hua Hong Grace (1347.HK, 688347.SS), lifting the parent's registered capital to 19.7 billion yuan from 13.5 billion, per an exchange filing on October 8 1. The stock answered with a 1.1% slip to HK$94.55 1.
The cash stops one register short
Guosheng's direct stake in the parent jumps to 41.7% from 15.3%, and its indirect holding in the listed shares rises to 10.2% from 3.8%, with Shanghai SASAC adding 19.7 million yuan and control unchanged 12. The listed company issues no shares and books none of the cash. The rest lands in Wuxi, where the Fab 9B joint venture's registered capital rose more than 4,000-fold to US$4.17 billion this month after Hua Hong itself paid US$2 billion in September for 51%, with the state Big Fund and local capital holding the rest 1.
Scarcity started paying a year ago
What the listed register owns is a young margin recovery. Q2 revenue hit a record US$717.5 million, up 26.8% year on year, gross margin reached 16.5%, up 5.6 points, and President Bai Peng told the August 13 call that orders run at 1.5 to 2 times capacity and price rises should run into 2027; the Q3 guide is 16 to 18% 5. At the top of the market, SMIC guided 26 to 28% on 93.7% utilization as AI squeezes global capacity and mature orders shift to China 36.
Gross margin has climbed from 10.9% to 16.5% in a year, guided 16 to 18 next
- Gross margin
- Estimate
Data
| Gross margin | |
|---|---|
| Q2 2025 | 10.9% |
| Q1 2026 | 13% |
| Q2 2026 | 16.5% |
| Q3 2026 guide (estimate) | 17% (16–18%) |
The other side says substitutes
Morningstar still calls Hua Hong's processes commoditized, with near-perfect substitutes one supplier away, which caps pricing power 4. Counterpoint sees TSMC's overflow lifting second-tier fabs and wafer prices rising structurally 7. Both hold while fabs are full; neither prices a new one opening.
55,000 wafers a month, state-funded
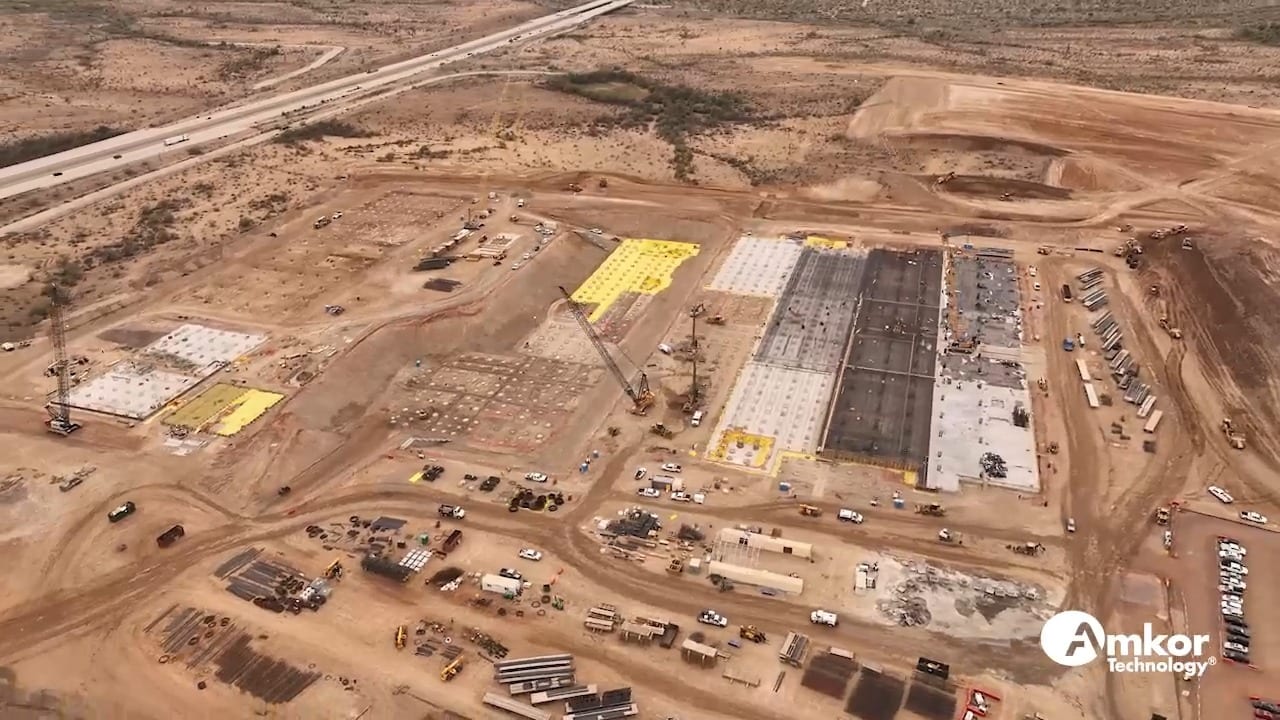
Fab 9B, started in March, adds 55,000 wafers a month of power, analog and embedded-storage capacity, about 30% more in Wuxi, ramping over three years at roughly US$1.5 billion of capex a year 15, inside a US$6 billion three-year build 8. Bai says US export controls have not touched the Wuxi equipment list 1. Whether AI demand absorbs those wafers or subsidized supply breaks the recovery is the one number no filing carries; the Q3 print decides the near term, the 2027 ramp the rest. Scarcity is the dividend, and Beijing just ordered its replacement.
Deepdive
AI-generated from this story and its cited sources. Not investment advice.