HubSpot cut free email sends 85% and moved Starter onto credits 12 days before earnings
Twelve days before its earnings print, HubSpot cut the Free plan's email sends 85% and folded Starter into the shared Credits pool it can tighten with one lever. UBS downgraded on the same evidence, and options price a 12% verdict.
 Vincent Jiang · 3 min read
The free plan's 2,000 monthly emails are now 300
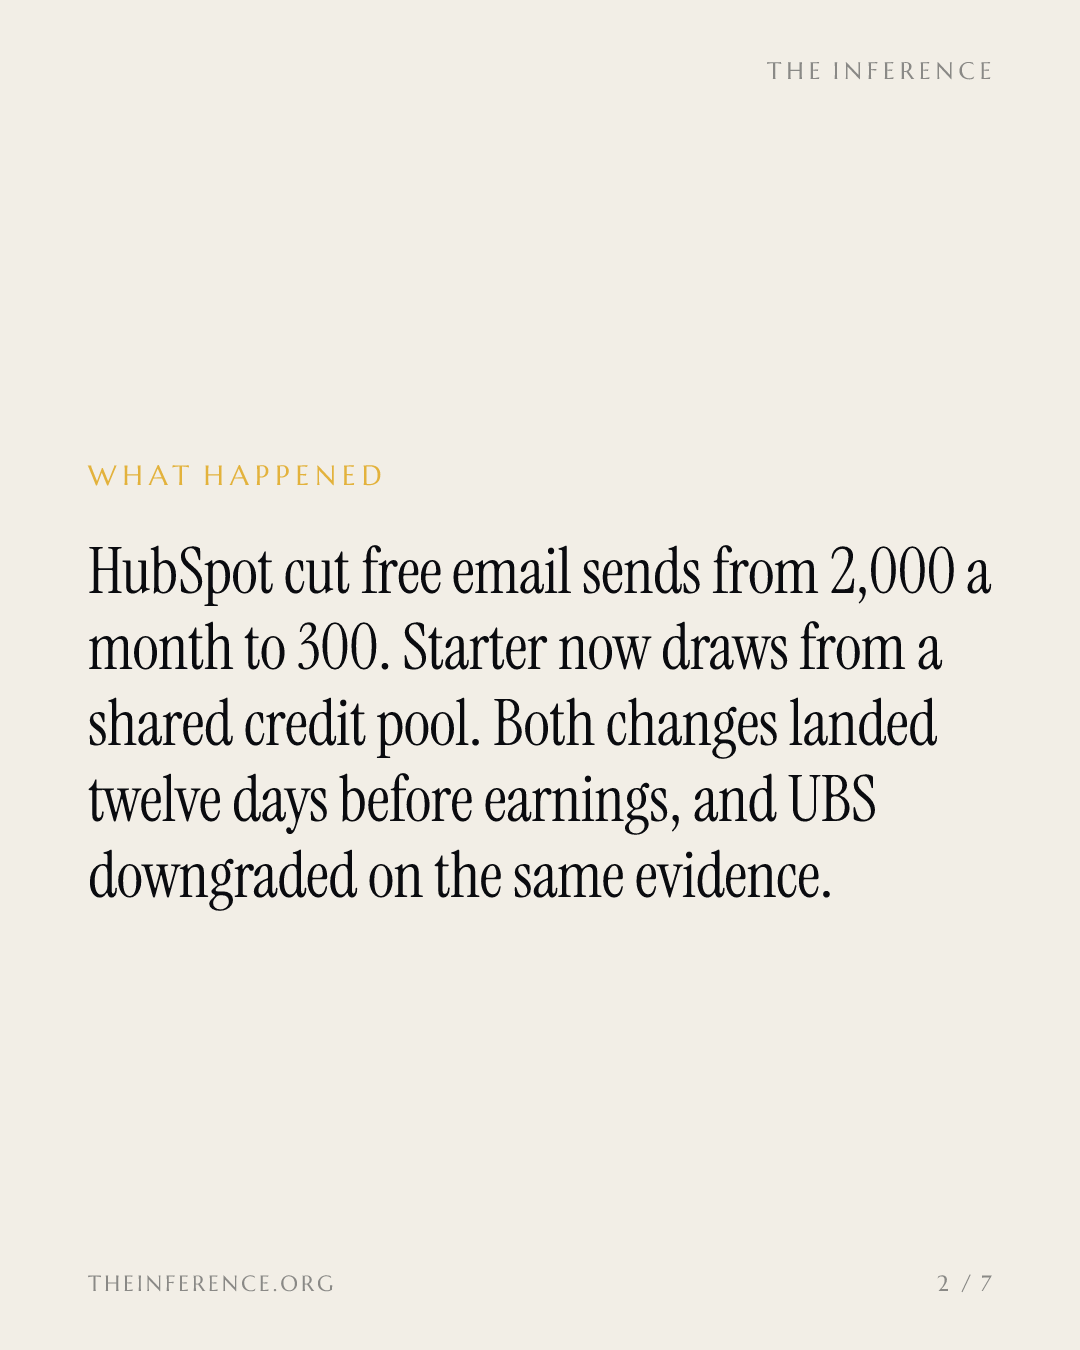
HubSpot's−3.93% — HubSpot, down 3.93 percent today pricing tracker PricingSaaS logged two changes to the company's pricing tables on Oct 23 1. The Free plan's monthly email allowance fell from 2,000 sends to 300, an 85% cut 1. Starter's email volume lost its own contact-tier-scaled limit and now draws from the shared Credits pool HubSpot stood up on Oct 3, 2025 with a flat 500-credit allocation 1. It is the third pricing-page change in 90 days; on Sep 18 HubSpot capped Sales Hub Starter automation at 50 workflows 1.
The first change squeezes. A free user sending 2,000 emails pays nothing but fills the funnel, so the cut forces an upgrade or an exit 1. The second change is structural: folding email into Credits turns a fixed entitlement into a consumable budget competing with every other metered action, one lever HubSpot can tighten later instead of several separate caps 1. The direction is industry-wide. Credits metering drove 243 pricing changes across 175 companies in the last 180 days, 12.1% of the 2,014 changes PricingSaaS tracks 1.
Options price a 12% verdict for Nov 4
Options on HubSpot shares imply a 12% move on the Nov 4 earnings report 2. Three days earlier, UBS downgraded the stock to Neutral from Buy, lifting its target to $310 from $290 3. Analyst Taylor McGinnis's channel checks found uneven small-business demand, nascent AI monetization, and partners warning that the shift to consumption pricing could pressure average selling prices near term 3. Only 5% to 10% of customers are buying additional credits 3. UBS cut its fiscal 2027 growth forecast to 13% from 14.5%, below the Street's roughly 14% 3.
UBS cut its fiscal 2027 growth forecast below the Street
Data
| FY27 growth, cc | |
|---|---|
| UBS prior | 14.5% |
| Street | 14% |
| UBS revised | 13% |
The entry tier is where those checks land. HubSpot's revenue still compounds: $911.7 million in the June quarter, up 19.8% year over year, on a 4.8% operating margin, per its SEC filings 4. The June quarter's 19.8% growth is the slowest in four quarters 4. What the print has to show is not the funnel but the meter: whether Starter and Free users upgrade against an 85% smaller allowance, and whether credit attach rates climb off UBS's 5% to 10% 3.
Revenue still climbs, but the June quarter grew at the slowest rate in four
Data
| Revenue | |
|---|---|
| Q1 '24 | $617M |
| Q2 '24 | $637M |
| Q3 '24 | $670M |
| Q4 '24 | $703M |
| Q1 '25 | $714M |
| Q2 '25 | $761M |
| Q3 '25 | $810M |
| Q4 '25 | $847M |
| Q1 '26 | $881M |
| Q2 '26 | $912M |
The other side, stated fairly
UBS still raised its target and sees long-term monetization in usage 3.
HubSpot frames credits as user control: account-level spending limits with initial caps 50% above monthly allocations, unused seats exchangeable for credits, and an EMEA overhaul from Oct 1 that replaced contact tiers with email-send pricing for new customers 5. Chief Customer Officer Jon Dick: "Nobody should have to miss out on getting the most out of AI because they don't know what the bill will be" 5. Both sides agree the bill is moving from seats to actions, as we argued when the 660 job cuts landed 6.
What to watch on Nov 4
The tell is credit attach rate and Starter upgrades, next scheduled reading Nov 4 23. The pricing page moved first. The print decides who pays.
Get Applications by email, free
How AI is changing the software people and companies use. In our daily email, every weekday.