Ibiden says AI-server substrate demand grows 5.4 times by 2030, and its shares fell 15% anyway
Ibiden expects demand for the boards under AI accelerators to outrun industry supply through 2030, and its own shares still fell hard on the day. AT&S, left off Nvidia's paid-capacity list, must answer with two cash numbers on November 5.
 Richard Tang · 3 min read
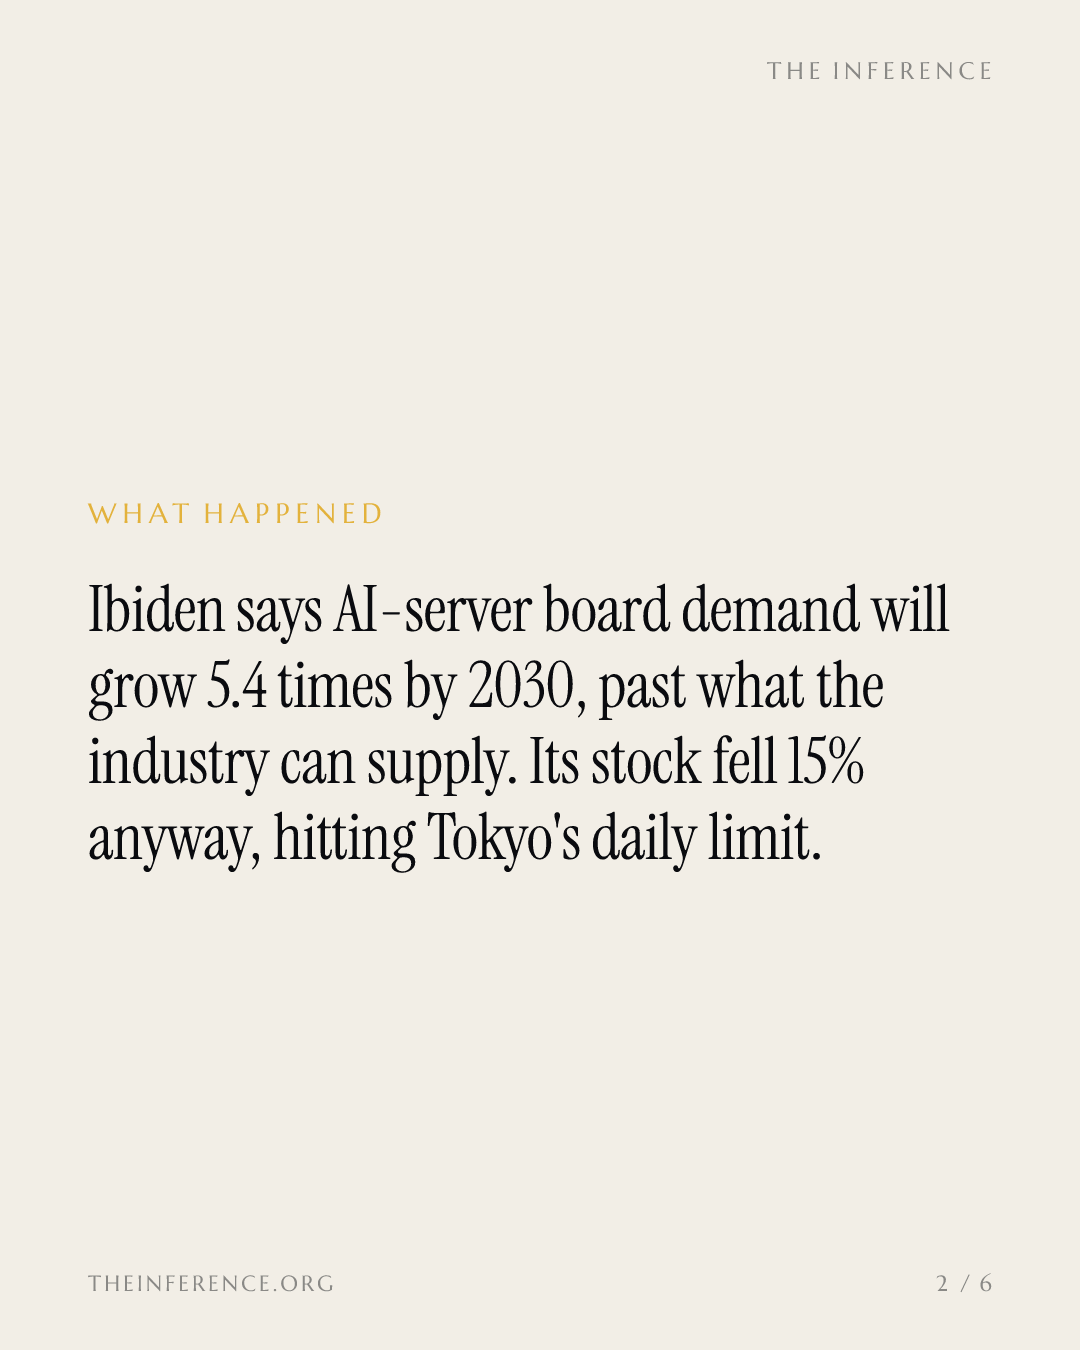
Ibiden−15.21% — Ibiden, down 15.21 percent today (Tokyo: 4062), the Japanese maker of the boards AI accelerators sit on, said on October 30, 2026, that demand for AI-server substrates will grow 5.4 times by 2030 and that total demand will significantly exceed what the industry can supply 12. Ibiden had just raised its full-year profit forecast on AI-server orders, and its shares still fell 15%, enough to hit the Tokyo exchange's daily price limit 1.
The open question is no longer whether the substrate shortage is real; it is who can finance a share of it, and the next answer comes from AT&S (Vienna: ATS) on November 5 3.
Bigger boards are driving the shortage
AI accelerators are assembled as chiplets on packages that keep growing, so each accelerator consumes more board. Ibiden's presentation shows substrate sizes rising from 80 by 80 millimetres to 130 by 130 by 2030, with layer counts rising in step 1. Most of the extra demand comes from each board getting bigger and denser rather than from more chips.
Most of the 5.4x growth in AI substrate demand is bigger boards, not more chips
- Estimate
Data
| Value | |
|---|---|
| AI accelerator market (estimate) | 1.8x |
| Production load per board (estimate) | 3x |
| Substrate demand (estimate) | 5.4x |
Nvidia's counter, signed at GTC Berlin on October 21 with Ibiden, Samsung Electro-Mechanics and Unimicron, lifts contracted substrate supply about 2.5 times over three years; the list, which we reported on October 24, does not include AT&S 56. Ibiden is adding about ¥150 billion of plant at Gama, but mass production there starts in fiscal 2029, and capacity of this kind takes two to three years from money to qualified output 15. One of the two plans is wrong, and everything built on substrates inherits the difference.
The risk at AT&S is cash, not demand
AT&S expanded its Kulim plant in Malaysia in June on agreements with AMD and one other unnamed technology company, a €1.5 to 2.0 billion project it says is fully financed by long-term customer commitments 7. It lifted its revenue-growth forecast to 45 to 55% at the same time 7.
The balance sheet is thinner than the order book: customer prepayments stood at €907 million at June 30 8, and the June quarter produced €39.9 million of operating cash flow, a fraction of the company's debt 9. A stock trading far below the €242 high it set this year 4 is being priced on its balance sheet, not on its orders.
Back to positive free cash flow, just as the big spending starts
- Free cash flow
- Estimate
Data
| Free cash flow | |
|---|---|
| FY2022 | €107.6m |
| FY2023 | -€624.6m |
| FY2024 | -€205.4m |
| FY2025 | -€490.6m |
| FY2026 | €235.4m |
| FY2027E (estimate) | €424.6m |
The AI line nobody models
AT&S also disclosed on October 21 that Infineon, the German power-chip maker, had given it a Best Value Creation award for embedding technology in power modules for AI servers, after more than ten years of cooperation 34. No revenue is attached. But Infineon is investing €1.1 billion through 2034 in power chips for AI data centers at Villach and has begun shipping rack power-delivery products 11, and embedded modules are how that silicon reaches a rack. It is the AI business at AT&S that sits outside every earnings model.
Two cash lines decide the discount
Two lines in the November 5 half-year report decide the discount: customer prepayments holding above their June 30 level, and operating cash flow stepping up from the June quarter and staying there 89.
While the prepayments keep coming, AT&S owns a scarce substrate business. If they stop, it owns a fab it cannot fill.
Above both lines, AT&S is the cheapest listed exposure to a shortage Ibiden dates to 2030, against a €308 consensus target 10. Below them, the 45% discount to the peak is the right price 10. The shortage runs for years; the constraint has moved to the balance sheet, and the reward now sits with whoever can carry it.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.