Micron names Hanmi Semiconductor a top supplier again, countering Morgan Stanley's HBM bonder sell case
Micron named Hanmi Semiconductor a top supplier for the second straight year, the only Korean company on a list with Applied Materials and Lam Research. With the third-quarter print due November 6, the customers' own verdict is now the strongest counter to the sell case.
 Richard Tang · 2 min read
Micron−6.27% — Micron, down 6.27 percent today just told its suppliers who it cannot do without, and it named Hanmi Semiconductor−5.81% — Hanmi Semiconductor, down 5.81 percent today twice in a row. At Micron Supplier Day 2026 in Boise on October 20, the American memory maker gave Hanmi its Outstanding Supplier Performance Award for the second consecutive year, and Hanmi was the only Korean company on a winner list that includes Applied Materials−7.21% — Applied Materials, down 7.21 percent today and Lam Research−11.10% — Lam Research, down 11.10 percent today 12. The award is Micron's own evaluation of quality, innovation and collaboration, not Hanmi's marketing, so it cuts against Morgan Stanley's−1.69% — Morgan Stanley, down 1.69 percent today sell case that Hanmi's HBM equipment franchise is a one-customer story priced for perfection.
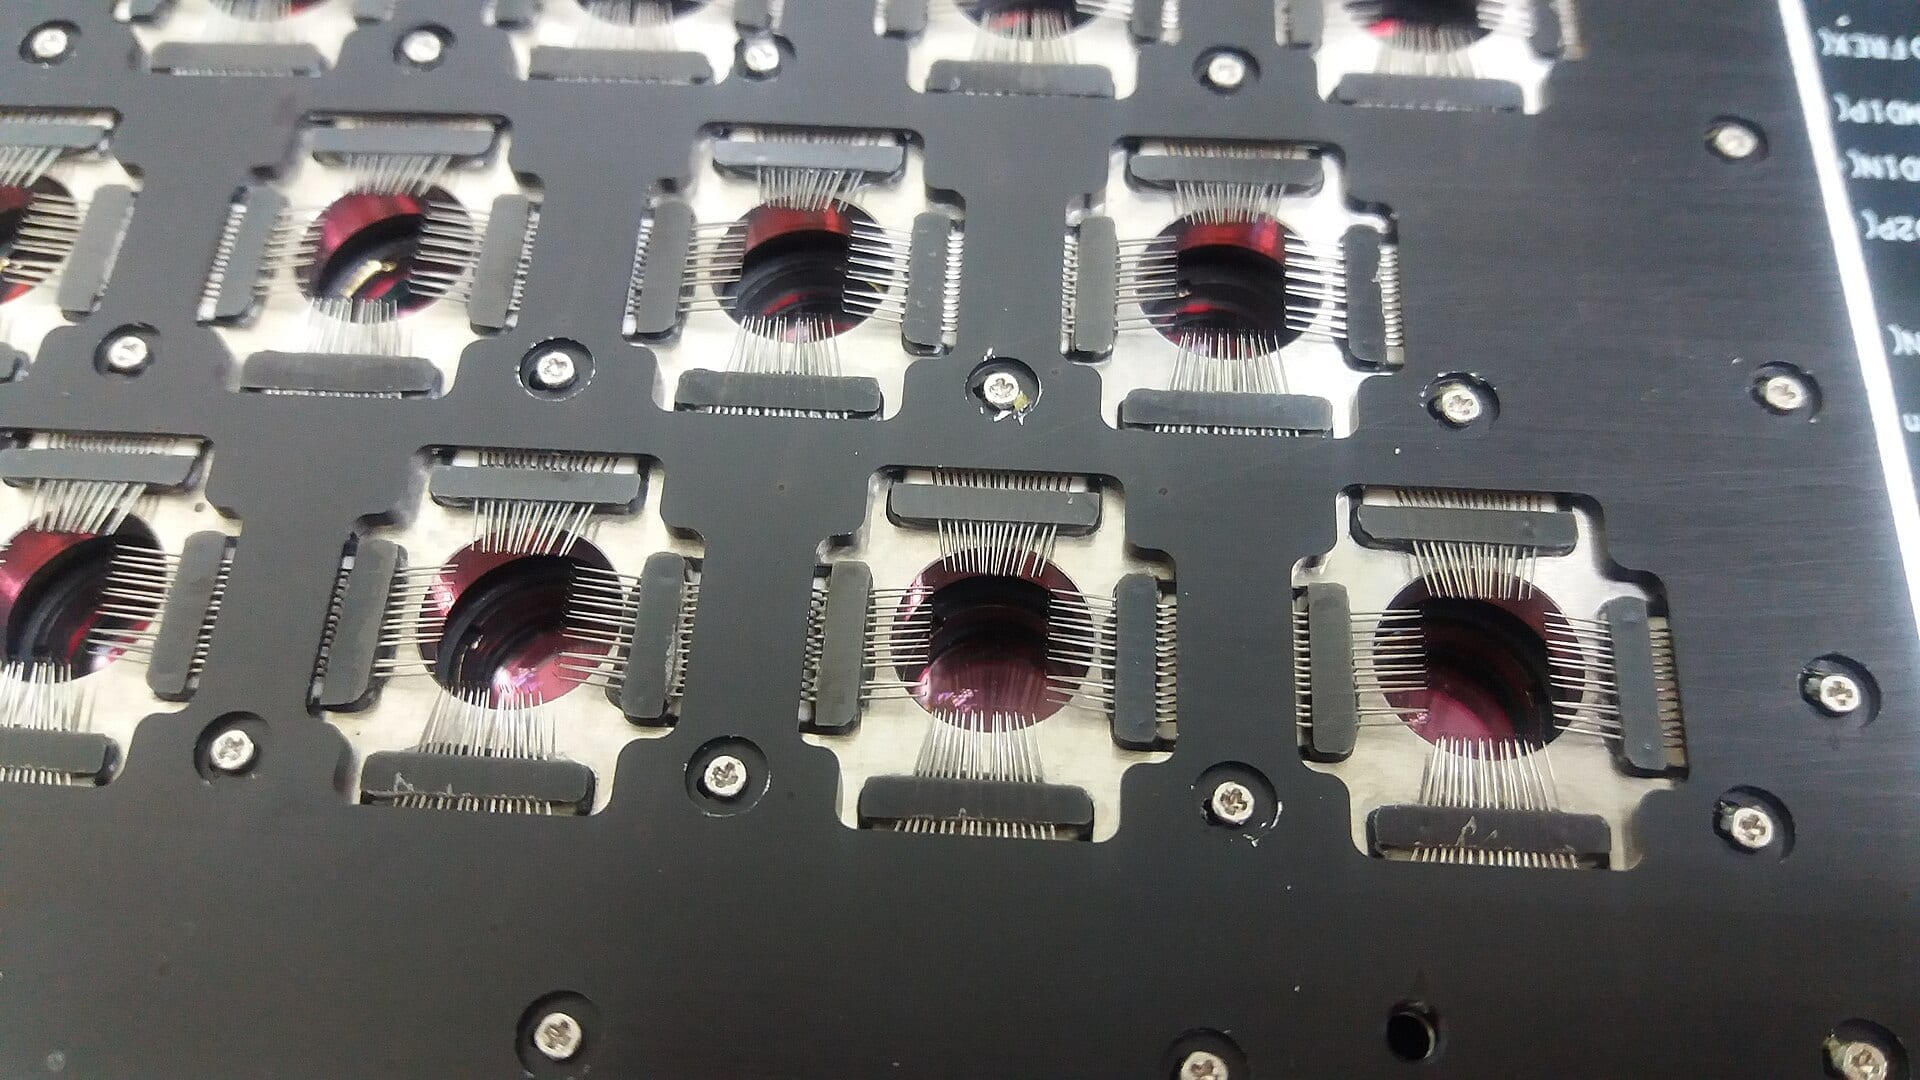
The machines are the reason. Hanmi's TC bonders stack DRAM dies vertically with heat and pressure, the step that turns DRAM into HBM, the memory stacked next to AI accelerators. Hanmi holds the number one global share in that field and launched TC Bonder 4, the industry's first HBM4 mass-production bonder, in 2025 12.
US fabs are where the bonders go next
Micron is building memory fabs in Idaho and New York, and SK hynix−7.15% — SK hynix, down 7.15 percent today broke ground on an HBM packaging plant in Indiana targeting mass production in 2029, so US-bound HBM capacity is exactly where Hanmi's bonders go next 4.
That is why chairman Kwak Dong-shin opened Hanmi USA in San Jose this month, the company's fourth overseas base, to station engineers next to those fabs 4. Vice chairman Kim Min-hyun collected the award while the company showed five new 2.5D packaging tools at SEMICON West and started an eighth factory in Incheon 13. The customers are confirming the capability; the gap between capability and revenue is being closed by these builders, and the reward question is what the shares already price.
What the shares already price
The market says a lot is priced: the stock sat at KRW 212,000 on October 19 against a KRW 267,143 average target, and consensus splits 3 buys against 4 sells 3. Execution is the test, and the figures in hand point the right way: second-quarter revenue reached KRW 251.2 billion, up about 40% year on year, with operating profit up 51%, plus a fresh KRW 44.2 billion SK hynix order 3.
Revenue, profit and order book all point the same way into the November 6 print
Data
| Value | |
|---|---|
| Q2 revenue | 251.2 |
| Q2 operating profit | 130.3 |
| SK hynix order | 44.2 |
| Incheon factory | 130 |
The checkpoint is November 6, when third-quarter numbers land 3. If deliveries keep the second-quarter pace, the customers' judgment stands and the sell case weakens further; if they slip, the valuation argument takes over. Learn the equipment layer either way: whoever masters the machines that make HBM is building the AI supply chain's load-bearing wall.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.