UMC missed consensus at 92% utilization and added $3.2 billion of capex, with the stock up 147.5%
The mature-node foundry missed consensus and asked its board for another US$3.2 billion of capex, while 45% of its nine-month pre-tax profit came from outside operations. The 2027 price rise management promised is still only a negotiation.
 Vincent Jiang · 3 min read
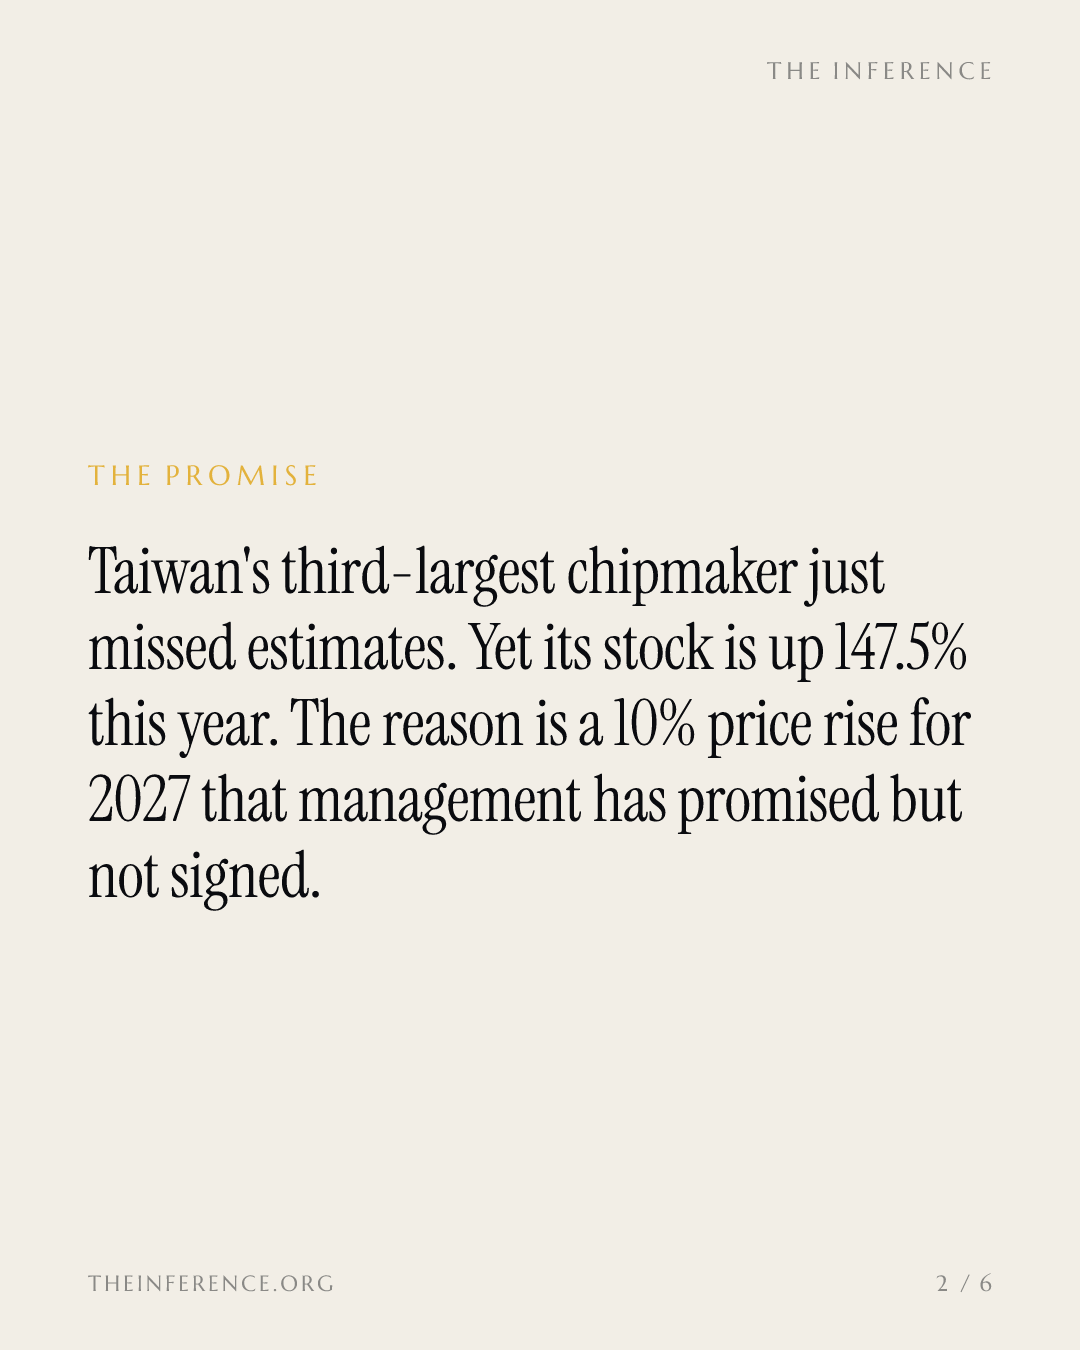
Taiwan's third-largest foundry just asked investors to pay for a price rise that has not been signed yet. On October 28, United Microelectronics−3.73% — United Microelectronics, down 3.73 percent today reported third-quarter revenue of NT$74.24 billion, or US$2.32 billion, up 25.6% year on year but short of the US$2.35 billion analysts expected, and earnings per ADS of US$0.21, a cent below consensus 123. The ADR fell in Wednesday trading 3.
The fab is full, and that part is real
The quarter itself was strong where it counts. Utilization hit 92%, up from 85% in the second quarter and 78% a year earlier, on record wafer shipments of more than 1.2 million 12-inch-equivalent wafers 13. Gross margin reached 34.0%, operating margin 25.1%, and 22nm hit a record 18.3% of wafer sales on display-driver, automotive-radar and Wi-Fi tape-outs 13.
UMC fab utilization climbed from 78% to 92% in a year
Data
| Value | |
|---|---|
| Q3 2025 | 78 |
| Q2 2026 | 85 |
| Q3 2026 | 92 |
Margins have climbed for four straight quarters but sit below the 2023 peak
- Gross margin
- Operating margin
Data
| Gross margin | Operating margin | |
|---|---|---|
| Q3 '23 | 35.9% | 26.8% |
| Q4 '23 | 32.4% | 22.6% |
| Q1 '24 | 30.9% | 21.4% |
| Q2 '24 | 35.2% | 24.5% |
| Q3 '24 | 33.8% | 23.3% |
| Q4 '24 | 30.4% | 19.8% |
| Q1 '25 | 26.7% | 16.9% |
| Q2 '25 | 28.7% | 18.4% |
| Q3 '25 | 29.8% | 18.8% |
| Q4 '25 | 30.7% | 19.8% |
| Q1 '26 | 29.2% | 18.5% |
| Q2 '26 | 32.5% | 21.8% |
The filing says what the wire did not
For the first nine months, pre-tax profit was NT$81.74 billion but operating income was NT$44.87 billion 1. NT$36.9 billion, 45% of pre-tax profit, came from outside the fab, largely a second-quarter non-operating gain 14. Third-quarter net income of NT$16.43 billion fell 61.2% from the second quarter on that same swing 14. On operating earnings alone, nine-month EPS is roughly NT$3.57, about US$0.56 per ADS, so the US$19.46 ADR trades near 26 times the operating run-rate, not the mid-teens the headline implies 14.
A 10% price rise nobody has signed
Chief executive Jason Wang wants 2027 to be the turn: at least 10% higher blended average selling prices, year on year, with negotiations at a late stage but not concluded 12. To serve it, the board approved another US$3.2 billion of capex on top of the earlier US$5 billion plan, for silicon photonics, capacitor and modulator capacity that only starts ramping in late 2028 12.
Our October 23 reporting already noted CFO Chitung Liu's stake falling 28.4% in September and US$526.4 million of insider sales without a single buy; what is new since is the October 28 print itself, the revenue miss and this fresh US$3.2 billion approval 5.
What could sink the promise
Management itself flagged the offsets: rising raw-material costs and heavier depreciation will keep gross margin below earlier peaks 2. And the demand mix cuts against the promise. Consumer is about 32% of revenue today while AI will be only 25% of revenue in three years, and management sees PC demand declining with budget smartphones weaker still 235. The AI legs, silicon photonics and advanced packaging, cannot carry the stock until the late-2028 capacity lands 2.
The test is dated. The first 2027 ASP guidance arrives with the January earnings call 5. Until customers sign, the price rise is a promise, and a stock up 147.5% this year is priced on the promise 5.
Get Chips by email, free
How AI demand is reshaping chipmakers, memory and the fabs behind them. In our daily email, every weekday.